Learning costs without running into real problems is one thing. Actually using them to make decisions is another.
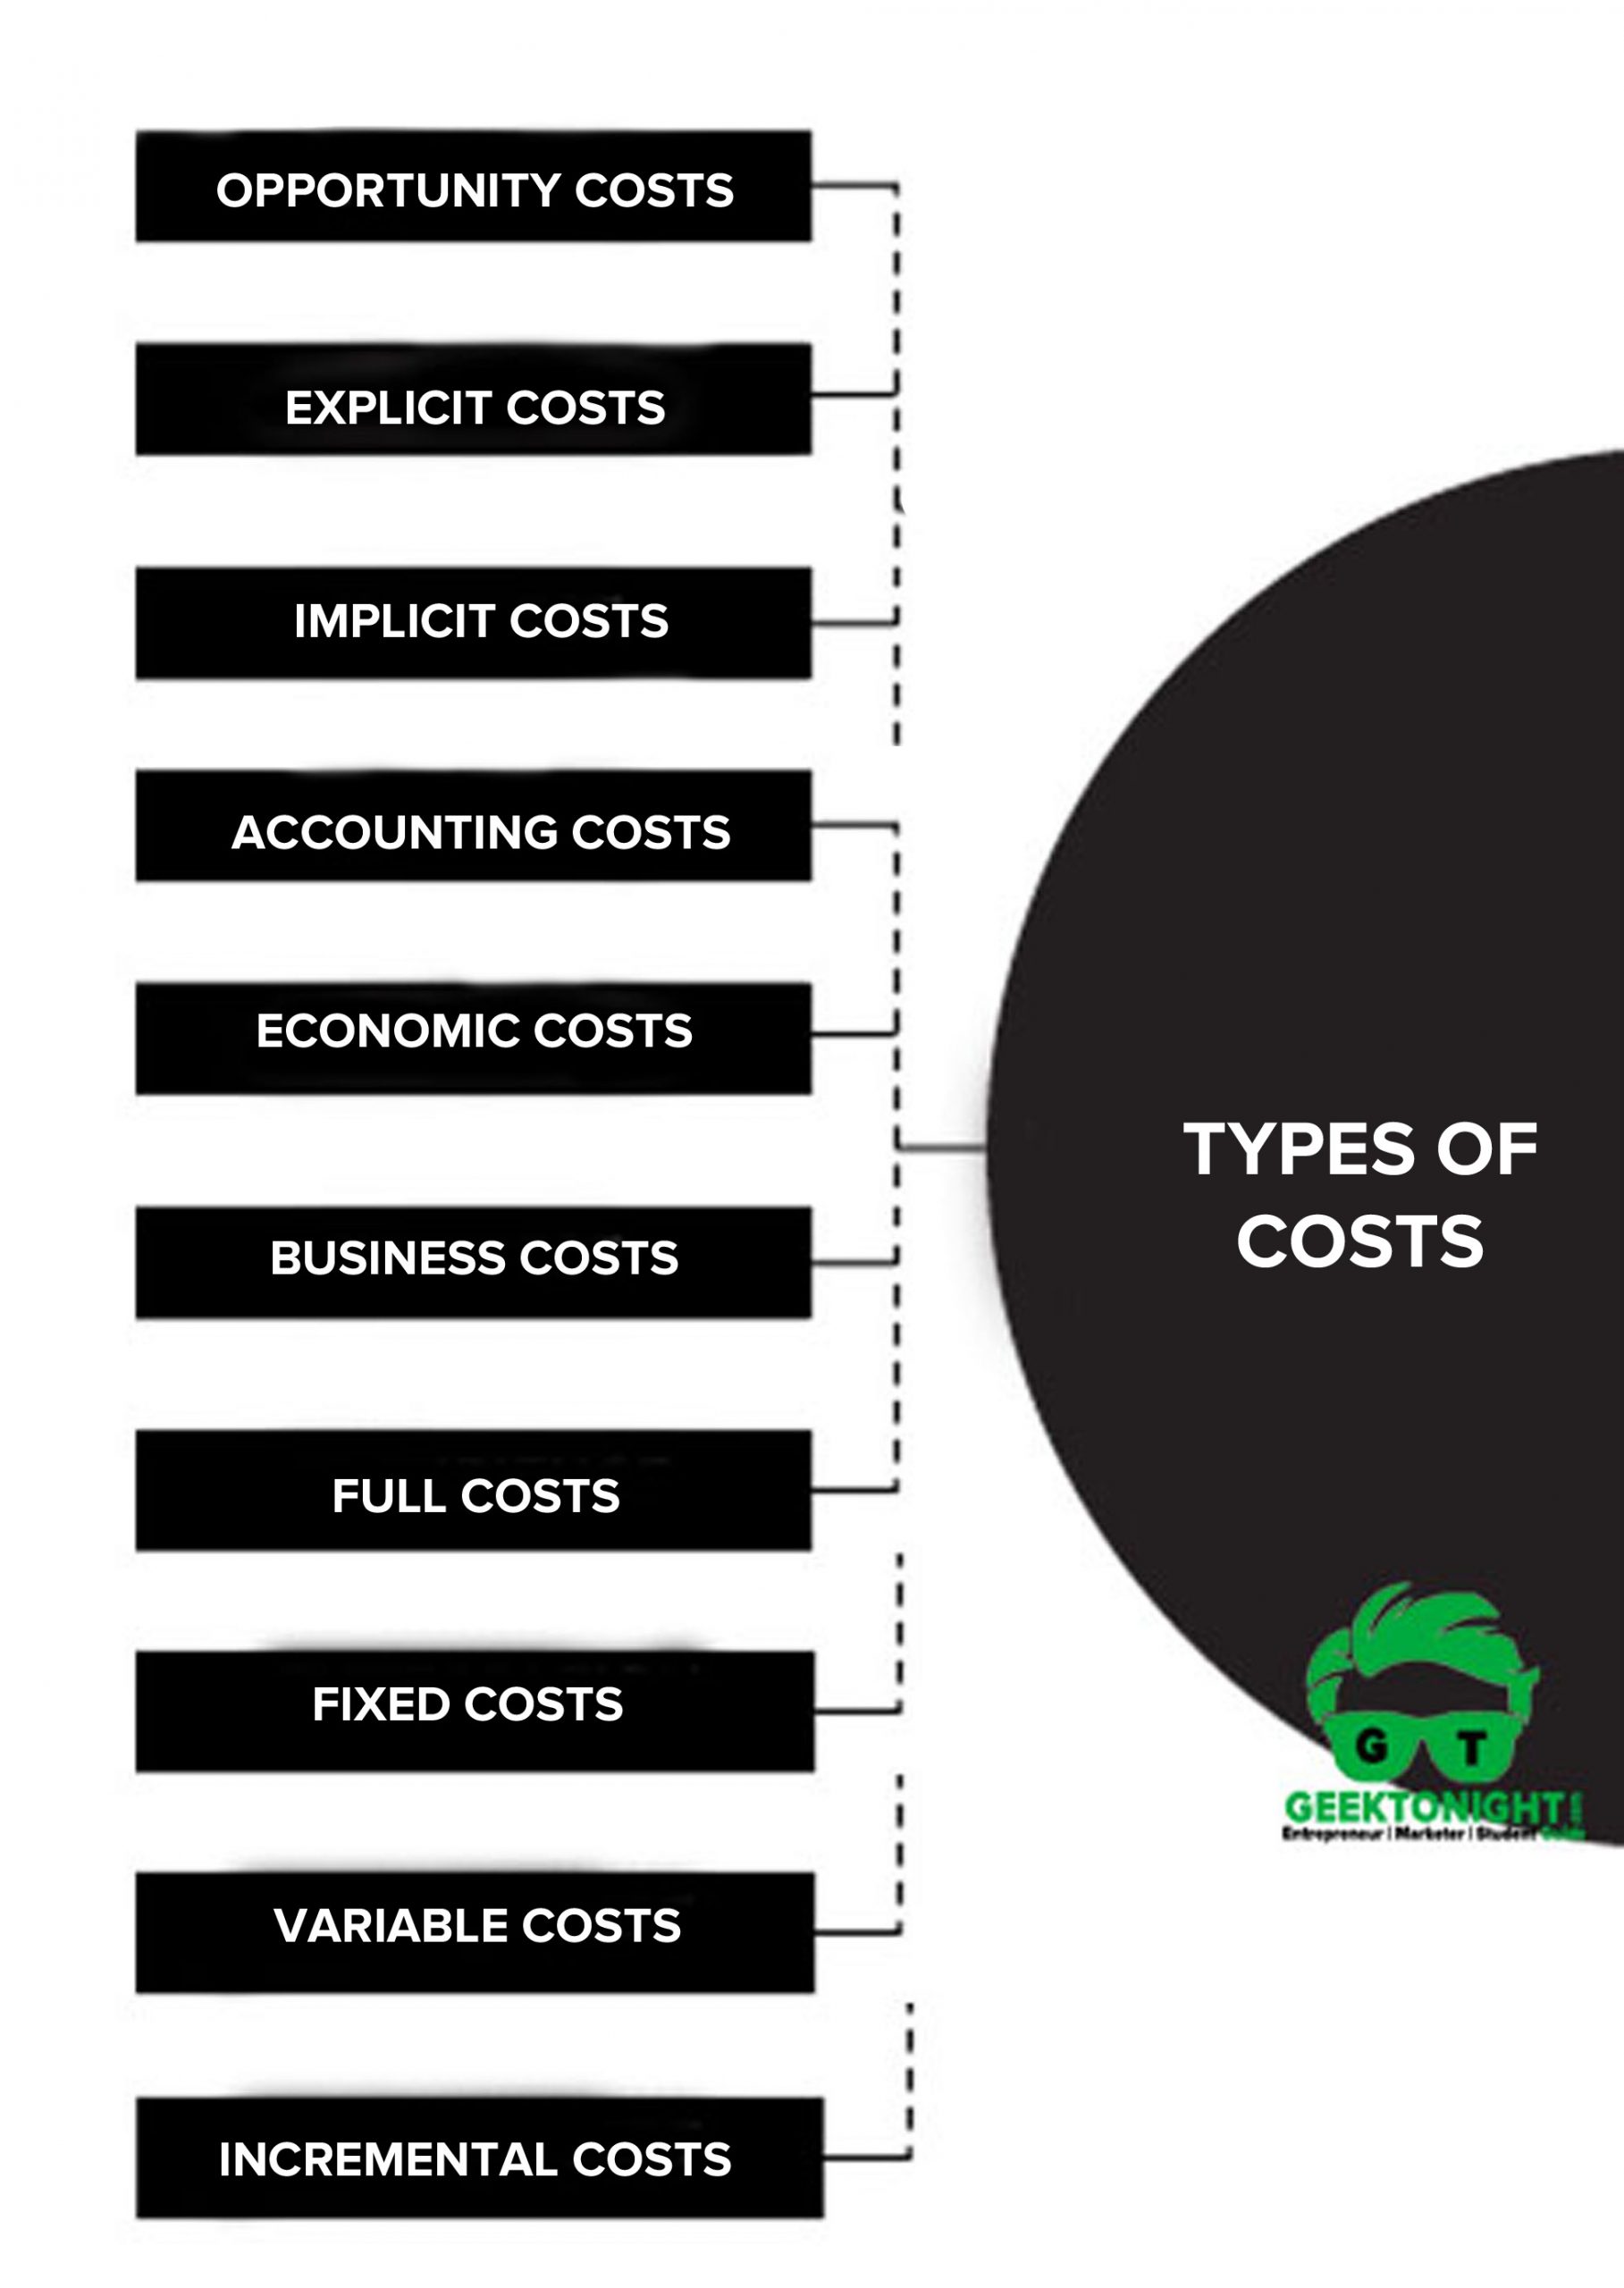
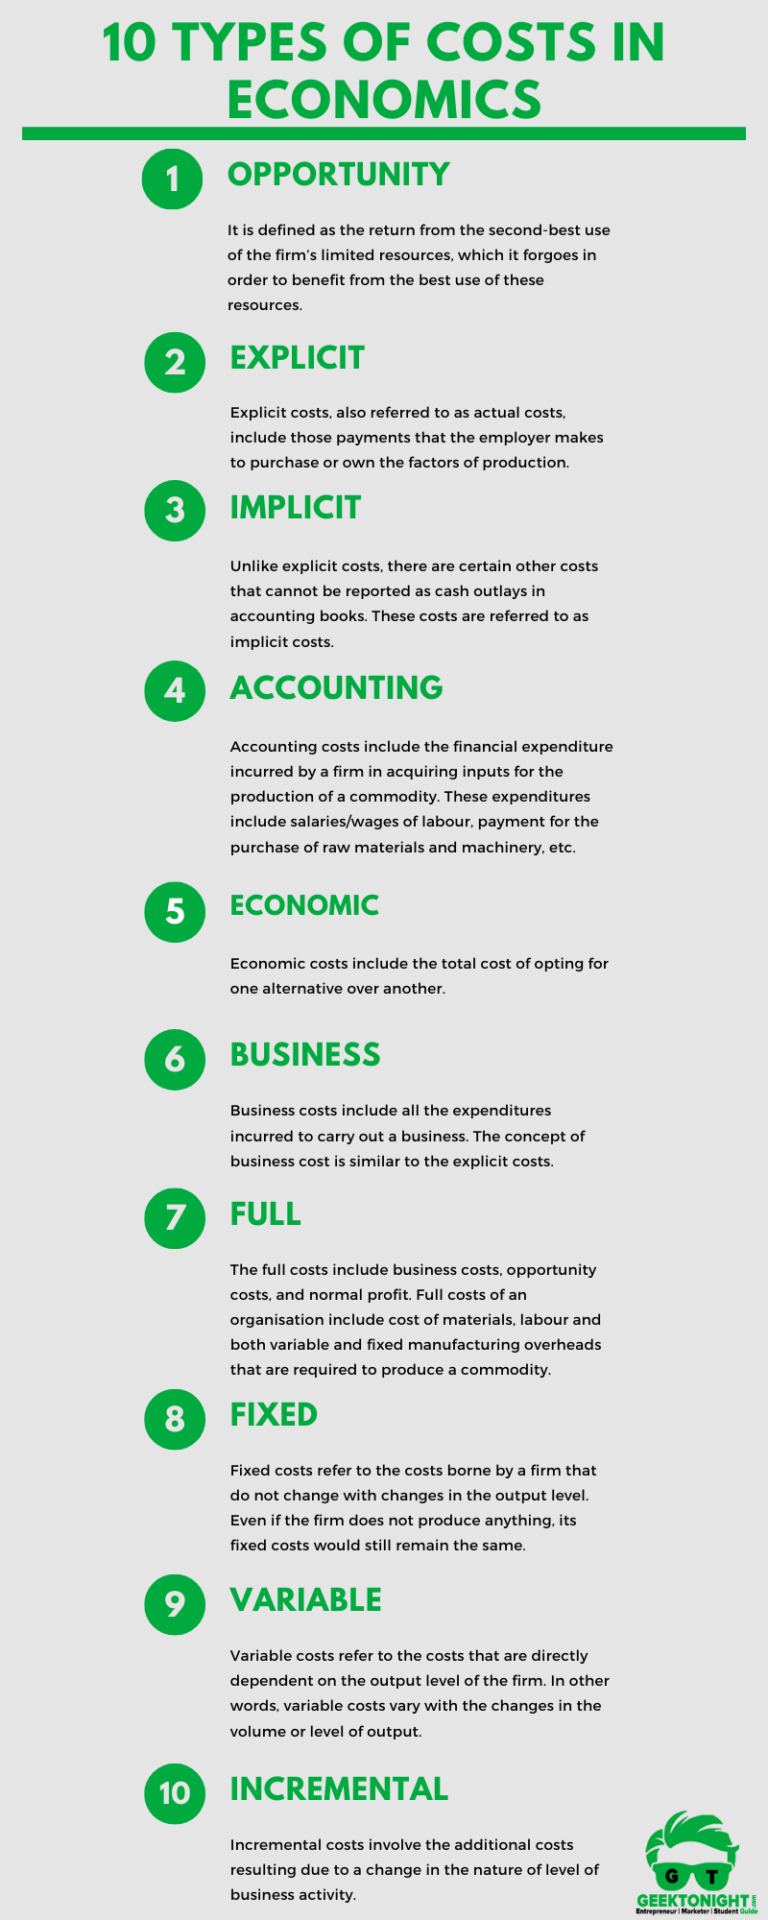
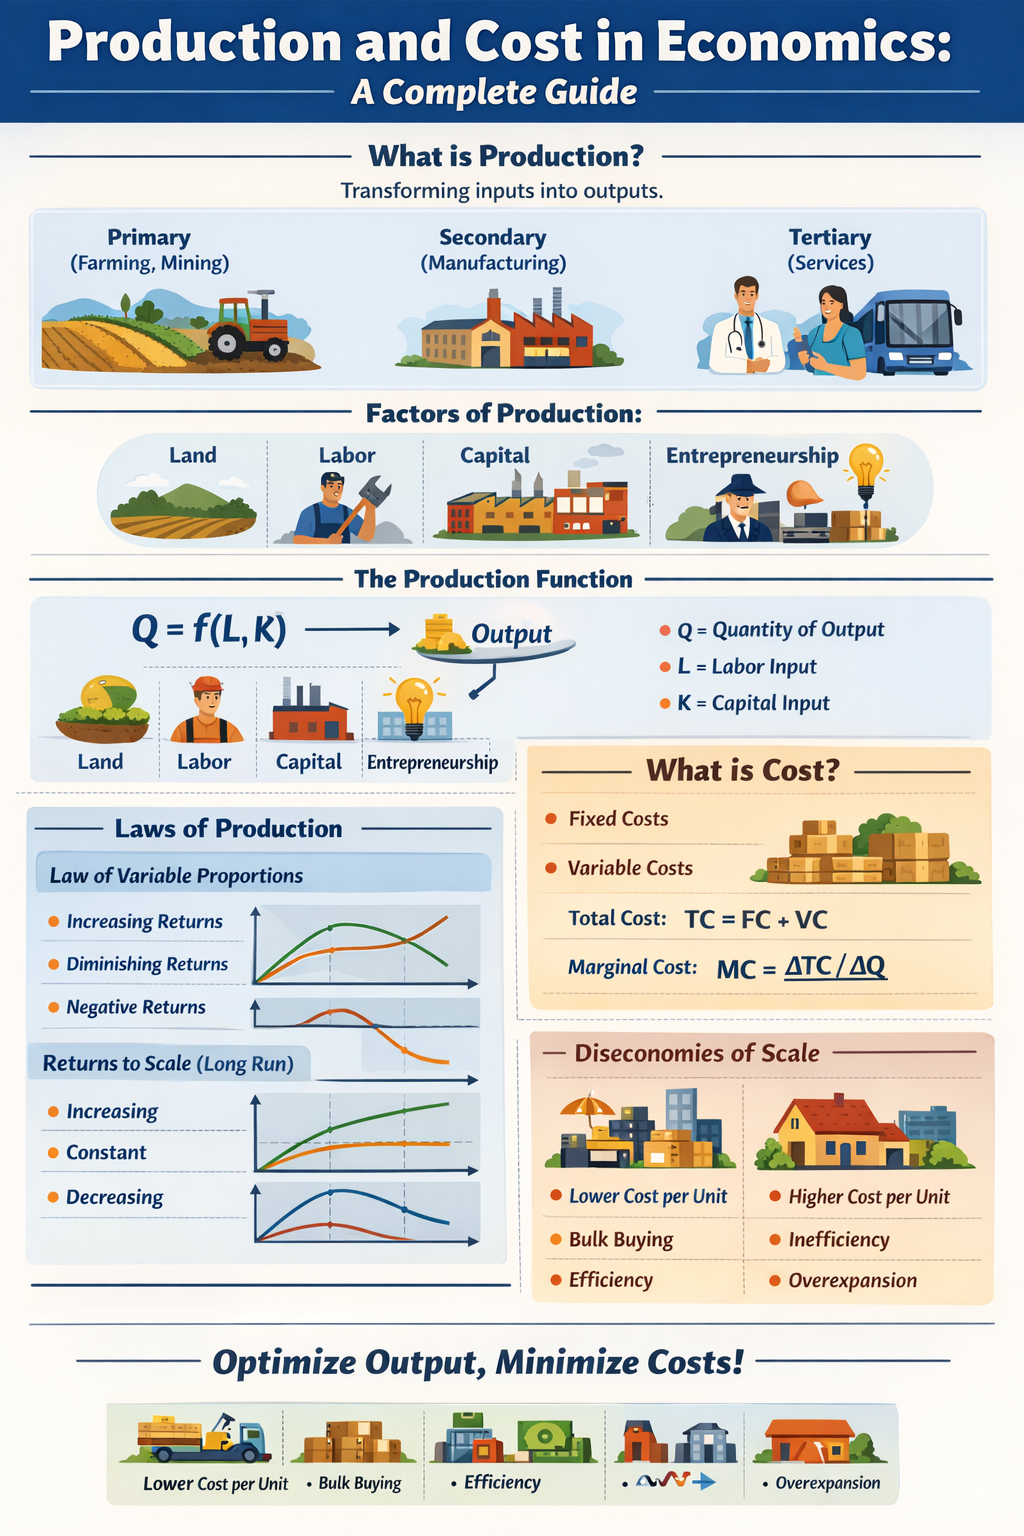
I spent about four years doing cost accounting for a small manufacturing operation before I ever truly understood what the textbooks were trying to tell me. We had the spreadsheets, the formulas, the standard diagrams with total cost curving upward. What we did not have was clarity on which costs actually mattered when the phone rang at 3pm and someone wanted five hundred units tomorrow morning. That is when you learn that Types Of Cost Of Production In Economics is not just a list of definitions you memorize for an exam. It is a set of tools that either help you breathe easier or make you panic harder, depending on how honestly you look at them. Fixed costs are the ones that do not care if you produce anything at all. Rent, insurance, the salary of the person who answers the phones whether the line rings once or a thousand times. Variable costs move with every unit you make. Materials, hourly labor, the electricity that runs the machines. Total cost is just those two added together, and average cost is total divided by output. Marginal cost is the cost of making one more unit. Sunk cost is money you already spent and cannot get back, which means it should not influence future decisions even though humans struggle to ignore it. Short run versus long run is where most people trip up. In the short run, at least one input is fixed. Maybe you own the building but you can rent more warehouse space. In the long run, everything is variable. You can sell the building, relocate, retool the entire line. The distinction matters because it changes which costs you can actually control when something goes wrong.
What nobody tells you about marginal cost
Most intro classes present marginal cost as this clean curve that dips then rises. The truth is messier. In my experience, marginal cost often stays flat for a surprisingly long stretch while you have idle capacity, then jumps all at once when you hit a bottleneck. I remember one week when our assembly line was running at sixty percent. Adding another shift meant overtime pay, which pushed the marginal cost up by nearly forty percent even though the physical cost of materials barely changed. The textbook curve did not capture that jump. What captured it was knowing where the real constraint lived in the process. Another counter-intuitive point: marginal cost can fall even as total cost rises. This happens when you spread setup costs over more units. A mold costs the same whether you make one part or ten thousand, so the marginal cost per unit drops dramatically at first, then eventually rises again when you hit capacity limits. The relationship between total and marginal is not as straightforward as the graphs suggest.
Sunk costs and why you should ignore them
The concept is simple. Money spent is gone. Do not let it dictate future spending. The practice is hard. I once watched a project manager justify pouring another fifty thousand into a failing product line because the company had already invested two hundred thousand. The logic was backwards. The two hundred thousand was irrelevant. The only question that mattered was whether the next fifty thousand would earn more than it cost. It did not. We killed the project the next day. The sunk cost was already a loss. Throwing good money after bad would have made it worse. This is the part that causes real damage in businesses. Opportunity cost is closely related but easier to overlook. When you commit resources to one thing, you are giving up whatever those resources could have done elsewhere. The cost is not what you spent. It is what you lost by not spending it differently.
Get the Full Details
How I actually use these concepts on a day to day basis
When I need to decide whether to take on a rush order, I look at marginal cost first. If the price covers the variable costs and contributes something toward fixed overhead, I take it. If it does not cover variable costs, I walk away unless there is a strategic reason. Fixed costs are not my problem in that moment. They are the problem of keeping the lights on regardless of what I decide about this order. For pricing decisions, I use average total cost as a floor, not a target. Setting price equal to average total cost sounds safe, but it ignores the fact that demand may not support that volume. Sometimes you price below average cost to move inventory that would otherwise sit idle and cost you storage fees. The loss on the unit is smaller than the loss from letting it sit. One edge case I ran into involves shared inputs. A single machine can produce part A or part B. The cost of running the machine is fixed, but the materials differ. Allocating the machine cost between the two products is arbitrary. I stopped trying to split it evenly and started looking at contribution margin for each product separately. The allocation distortion disappeared once I treated the machine as a capacity constraint rather than a cost to divide.
Where this framework breaks down
The textbook model assumes you know your costs precisely. In reality, cost estimation is often guesswork wrapped in spreadsheets. Indirect costs like supervision, quality control, and maintenance do not attach cleanly to individual units. You allocate them using some base like direct labor hours or machine hours, but the choice of base is subjective and changes the answer. Different bases give different product costs, and none of them is objectively correct. The model also assumes rational decision makers. Humans are not rational. We throw money at losing projects because we do not want to admit a mistake. We keep a product line alive because it has been part of the company for twenty years, even though the numbers show it consumes more resources than it generates. Understanding the theory does not fix that behavior. It just gives you a better vocabulary for arguing against it. Another limitation: these categories work best for manufacturing. Service businesses, software companies, and platform businesses have cost structures that do not fit neatly into fixed and variable buckets. A SaaS company might have high fixed costs for engineering salaries and near-zero marginal costs for each new customer. The framework still applies, but the intuition you bring from a factory floor will mislead you if you do not adjust for the different cost drivers.
The practical takeaway
Memorize the definitions. They appear on every exam and they surface in every boardroom conversation. Then spend time understanding where the lines blur. The most useful skill is not calculating average cost correctly. It is recognizing which costs are relevant to the decision at hand and which are noise. Fixed costs are irrelevant for short-term pricing. Sunk costs are always irrelevant. Variable costs are usually relevant. Marginal cost tells you where the next dollar of revenue goes. Knowing the difference between those four statements has saved me more money than any formula ever did.