Financial Ratios in Practice
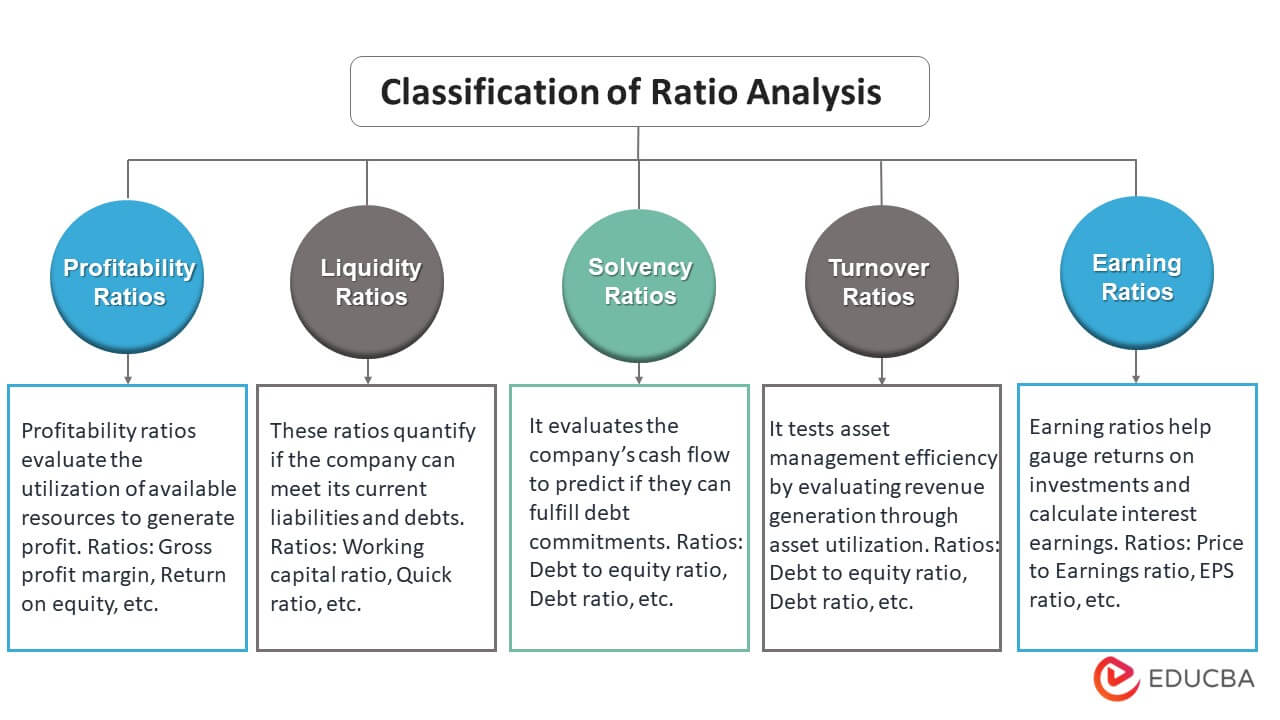
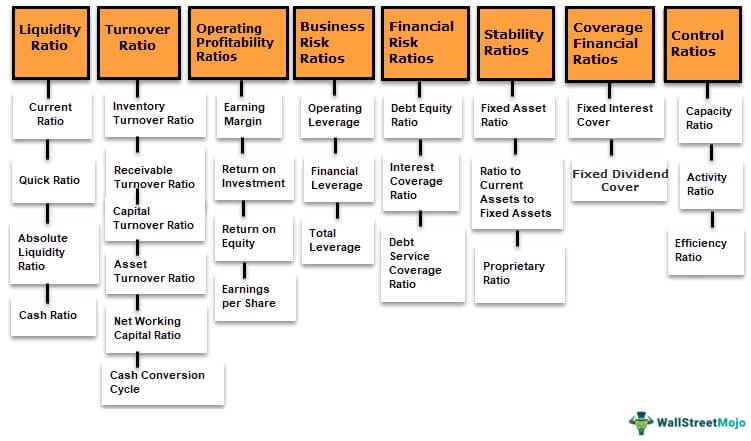
You pull a balance sheet and income statement off your desk, run through a handful of calculations, and you get numbers that tell you whether a business is solvent, profitable, efficient, or sitting on a debt time bomb. The whole exercise is built around Types Of Financial Ratios, and it's been the backbone of credit analysis and equity research for decades. I'm not going to walk you through a textbook definition of every single ratio. There are too many of them, and most people only use about eight or nine in any given month. What I'll do is show you how to actually use them when something goes wrong. Liquidity ratios measure whether a company can meet its short-term obligations. Profitability ratios measure whether it generates earnings relative to revenue, assets, or equity. Leverage ratios show how much debt is carrying the business. Efficiency ratios tell you how well assets are being deployed. These four buckets cover almost everything you'll encounter. The ratios within each bucket overlap, and knowing which ones to prioritize matters more than memorizing every formula. Here's a quick example that shows how they connect. Take a mid-market manufacturing company with current assets of 2.4 million, inventory of 680 thousand, current liabilities of 920 thousand, total assets of 8.6 million, total debt of 4.1 million, annual net income of 740 thousand, and revenue of 12.3 million. The current ratio is 2.61, the quick ratio is 1.87, the debt-to-equity ratio is 1.24, the return on assets is 8.6 percent, and the asset turnover is 1.43. On paper this looks acceptable. But paper numbers don't always match operational reality.
Liquidity ratios tend to get the most attention because they're the first thing lenders check. Current ratio above 1.5 is generally safe, quick ratio above 1.0 is better, and working capital staying positive over multiple quarters is the real signal. Profitability ratios are where most beginners make mistakes. A high gross margin means nothing if operating expenses eat it all. Net profit margin matters more for sustained businesses, but it can be manipulated through one-time charges or accounting choices. Return on equity is useful until a company loads up on debt, which artificially inflates ROE while increasing risk. Return on invested capital is the cleaner metric because it strips out the capital structure and focuses on operating performance. Efficiency ratios reveal how management is using what it has. Days sales outstanding tells you how fast customers pay. Days inventory outstanding shows how quickly product moves. Days payable outstanding indicates how long the company takes to pay suppliers. Combining these three gives you the cash conversion cycle. A lower cycle means the business funds itself faster. A negative cycle is rare but possible for companies like Amazon or Walmart that collect cash from customers before paying suppliers.
Types Of Financial Ratios
People often group ratios by textbook definition, but that's not how analysis actually works. In practice, the classification matters less than the question you're trying to answer. Are you assessing default risk? Focus on debt service coverage, interest coverage, and leverage. Are you evaluating operational health? Cash conversion cycle and asset turnover are your starting points. Are you looking at whether management is creating value? Look at return on invested capital versus the cost of capital, not just net margin or ROE in isolation. One detail most guides skip is how seasonal businesses distort these ratios. If a company pulls most of its revenue in Q4, a snapshot balance sheet taken in March will show a bloated receivables position and understated cash, making profitability and liquidity ratios look worse than they are for the full year. The fix is simple: use trailing twelve months income statement data paired with average balance sheet figures across the same period. Trailing twelve months eliminates the seasonal noise and gives you a result that actually reflects ongoing operations. Another detail people miss is that financial ratios assume consistent accounting policies. If one company uses FIFO inventory valuation and another uses LIFO, their gross margins and current ratios aren't directly comparable. This was the exact problem I ran into last year during a cross-border acquisition review. The target company in Southeast Asia had a current ratio of 1.82, which looked perfectly healthy at first glance. When I aged the receivables line item and found that 41 percent of current assets were tied up in invoices older than 90 days, the ratio collapsed into something entirely different. Those receivables weren't performing. I adjusted the working capital by writing down the aged portion based on historical write-off rates for that market, which dropped the effective current ratio to about 1.31 and changed the entire credit recommendation. Without that adjustment, we would have approved financing on weakened collateral.
Get the Full Details
Interest coverage ratio is another area where the surface number can be dangerously misleading. A company reporting EBIT of 3.2 million against interest expense of 800 thousand shows a coverage ratio of 4.0, which sounds comfortable. But if 60 percent of that EBIT comes from a single commodity-linked contract that is about to expire, the coverage ratio will drop sharply once that revenue resets. I always stress test leverage metrics against revenue decline scenarios before relying on them. A 20 percent revenue drop is enough to turn a comfortable 4.0 coverage ratio into something close to breakeven. Debt-to-capital and debt-to-equity are frequently confused, and the distinction matters. Debt-to-capital uses total debt plus equity in the denominator, while debt-to-equity uses only equity. When equity is small, debt-to-equity spikes even if the overall capital structure is moderate. For private companies with thin equity bases, debt-to-capital gives a more stable reading across periods. That said, both ratios treat all debt equally, which is another limitation. Operating leases, pension obligations, and deferred tax liabilities are real commitments but often sit outside the debt line on the balance sheet. Adjusting for those gives you a clearer picture, especially in capital-intensive industries. Gross margin trends are easier to read than single-period snapshots. A flat gross margin over four quarters isn't inherently bad, but a declining trend combined with rising receivables usually means the company is discounting to move product or extend credit to risky customers. Revenue growth without margin expansion is another red flag. Growth funded by deteriorating unit economics eventually runs out of runway. The cash conversion cycle captures this dynamic early because it shows when growth stops translating into cash.
Return on equity deserves a closer look because it decomposes cleanly into three parts: profit margin, asset turnover, and equity multiplier. A company can improve ROE by getting more efficient, by pricing better, or by taking on more debt. The third path is the dangerous one. When ROE rises solely because the equity multiplier increases, leverage is doing the work, not operations. Splitting ROE into those components takes about two minutes and prevents a lot of misreadings. The cash flow statement is where ratio analysis often hits a wall. Earnings can be shaped by depreciation schedules, stock-based compensation, and amortization. Cash flow from operations is harder to manipulate, but it still requires context. A company might show strong operating cash flow while investing heavily in working capital. That pattern is sustainable only as long as growth continues. Once growth slows, the working capital draw reverses and cash flow can deteriorate quickly. I always compare operating cash flow to net income over a rolling four-quarter window. If the gap widens beyond 20 percent in either direction, I dig into the line items instead of accepting the headline number.
When ratios stop working
There are situations where financial ratios produce noise instead of signal. Distressed companies with falling asset bases distort efficiency metrics because the denominator shrinks faster than income. Pre-revenue companies have no earnings to ratio against anything meaningful. Holding companies and investment firms report asset values that don't map to operating performance. In those cases, traditional ratios are either irrelevant or actively misleading. Cash burn rate, runway, and capital deployment metrics replace them. Another boundary case is heavily regulated utilities and infrastructure operators. Their capital intensity and rate-base dynamics make standard leverage and efficiency ratios behave differently than they do in competitive industries. Comparing a utility's return on equity to a software company's return on equity is pointless. Industry-specific benchmarks exist for a reason, and they matter more than cross-sector ranking tables. For most other businesses, a focused set of ratios applied consistently does the job. I typically work with current ratio, quick ratio, interest coverage, debt-to-capital, gross margin, net margin, return on invested capital, asset turnover, and cash conversion cycle. That covers the main risks without turning analysis into a spreadsheet exercise. Anything beyond that is usually marginal unless you're underwriting a leveraged transaction or digging into forensic accounting. Then you pull in the rest.