Joint ventures are messy until you understand which structure actually fits your situation
I've sat through more JV negotiations than I care to count, and the biggest mistake I see is people picking a structure before they understand what they're actually trying to accomplish. The agreement type follows the business objective, not the other way around. When I started out, I watched two companies sign a contractual joint venture thinking it would give them the flexibility they needed, and three years later they were still arguing over who owned improvements to shared equipment. That's the thing nobody warns you about.
Types Of Joint Venture Agreements
There are really three main structures, and each one carries different liability, tax, and operational consequences that most people gloss over in the early meetings.Corporate joint ventures create a brand new legal entity—usually an LLC or corporation—that both parent companies own shares in. This is the cleanest structure for liability purposes because the JV itself becomes the liable party, not the individual parents. I once worked on a mining JV where the corporate structure saved one of the parents from an environmental liability that would have been personally devastating. The tradeoff is that you're dealing with double taxation in some jurisdictions unless you elect S-corp status, and the administrative overhead is real. You're running a separate company with its own board, its own compliance requirements, its own accounting stack. It typically takes 4 to 6 weeks to get incorporation paperwork sorted and the operating agreement finalized, assuming both sides aren't dragging their feet on capital contribution schedules. Partnership joint ventures operate under a partnership structure where the parents share profits, losses, and management directly. This avoids the double taxation problem entirely since partnership income flows through to the parents' own tax returns. But the liability exposure is the catch. In a general partnership setup, each parent can be held liable for the entire partnership's debts, not just their portion. I learned this the hard way when a retail JV partner's vendor went bankrupt and the creditors came after our parent company for the full amount because the partnership agreement didn't have a clear indemnification clause. We spent about eighteen months in litigation sorting it out. Limited partnerships offer some protection but require at least one general partner who carries unlimited liability, which creates its own set of governance problems. Contractual joint ventures are the most flexible and the most dangerous if you don't draft them properly. The parties agree to collaborate on a specific project without creating a new entity. Everything runs through individual contracts—supply agreements, service agreements, IP licensing. This works well for short-term projects where you want speed and simplicity. A construction company and a technology firm might team up for a single smart-building installation without forming a separate company. The downside is that there's no liability shield. If something goes wrong, you're dealing directly with each other's balance sheets. I saw a software JV collapse because the contractual agreement didn't specify who owned the code written during the partnership. Both companies claimed it, and the project stalled for two years while lawyers sorted it out.
There's a fourth category that doesn't get enough attention: the equity joint venture with management rights. This is common in international markets where foreign companies need a local partner to operate but want to retain operational control. The foreign parent might own 49% while the local partner owns 51%, but the management agreement gives the foreign parent day-to-day decision-making authority. It's a workaround for regulatory restrictions, and it works when both sides understand the arrangement clearly. It falls apart when the minority owner starts making unilateral decisions about capital expenditures or hiring without going through the agreed governance process. My rule of thumb is that any JV with a management rights structure needs a very detailed board composition clause and explicit veto rights on material decisions. The structure you pick should be driven by four questions, not the other way around. How long will this venture last? What level of liability exposure are you comfortable with? Do you need a separate balance sheet for financing purposes? How deeply do you want to integrate operations between the two companies? If you're looking at a project that runs less than two years and involves minimal ongoing operations, a contractual JV is usually sufficient. You can draft the core agreement in about two weeks with reasonable legal fees, and you avoid all the incorporation overhead. If you're planning something that could run five to ten years and involves significant capital investment, you want a corporate structure. The upfront cost is higher—incorporation, operating agreement, ongoing compliance—but the liability protection and financing flexibility pay for themselves over time.
Get the Full Details

One thing that catches people off guard is the exit strategy. Most JV agreements I review spend about 80% of their pages on how to start and run the venture and maybe five pages on what happens when things go wrong. That's backwards. I always recommend spending at least as much time on the exit provisions. Right of first refusal, drag-along and tag-along rights, valuation mechanisms for buyouts, non-compete scope after dissolution. I had a client who structured a manufacturing JV without a clear buyout valuation method, and when the venture didn't work out after four years, the two parents couldn't agree on what the company was worth. The valuation ended up being determined by court-appointed arbitrators who had no industry knowledge, and the result cost both sides significantly more than a pre-agreed formula would have. Another counter-intuitive point: having equal ownership isn't always better. A 50/50 split sounds fair but creates deadlocks on every material decision. I've seen joint ventures paralyzed for months because neither side would budge on a budget decision, and the deadlock provision in the agreement required mediation before arbitration before anything could move forward. The median resolution time was about fourteen months. A 51/49 split with clear governance rules—where the majority owner has tie-breaking authority on operational decisions but the minority owner has veto rights on fundamental changes like selling the business or changing the core product—tends to work better in practice. You can also use weighted voting on different decision categories rather than a flat ownership percentage controlling everything. The intellectual property question is where mostJV agreements fail, especially in technology partnerships. Who owns the background IP that each party brings? Who owns the foreground IP created during the partnership? What licenses are granted, and do they survive termination? I had a client who contributed proprietary code to a JV and the agreement said the JV would own all derivative works. The other party then used that derivative code to build a competing product six months after the JV dissolved, and our client had no legal recourse because the IP clause was too broad and didn't include sunset provisions or field-of-use restrictions.
Confidentiality clauses in JV agreements also need to be specific about duration and scope. A standard NDA-style confidentiality provision that says "confidential information must be kept confidential" is useless when the JV relationship ends and one party wants to use the other's trade secrets in a competing venture. I always include explicit post-termination obligations with a defined time limit—typically two to three years—and carve-outs for information that becomes publicly available through no fault of the receiving party. Data ownership deserves its own section in modern JVs, especially when either party handles customer data. GDPR and similar regulations mean that data processing agreements need to be part of the JV structure from day one, not added as an afterthought. I've seen JVs in the healthcare and fintech spaces stall because the parties couldn't agree on who controlled the data and under what conditions it could be shared with third parties. The workaround I've used successfully is to establish a data governance committee with representatives from both parties and a neutral third-party data steward who makes decisions when the committee deadlocks. It adds about 10% to the initial setup cost but prevents massive disputes later. When it comes to actual document drafting, the single most important section is the dispute resolution clause. Most JV disputes get resolved through the courts because the agreement either had no dispute resolution mechanism or specified litigation as the default path. Court proceedings in commercial disputes average 18 to 24 months and can run several hundred thousand dollars depending on complexity. Arbitration is faster—typically 6 to 12 months for a straightforward case—but it's not cheap, and the arbitrators' fees can add up quickly. Mediation is the cheapest option and resolves about 60% of commercial disputes without needing to go further, but it only works when both parties are willing to compromise, which isn't always the case when a JV is failing.
A tiered dispute resolution clause that requires mediation first, then arbitration if mediation fails, is the standard I recommend. Specify the arbitration rules (AAA, ICC, or a regional body), the number of arbitrators, the governing law, and the seat of arbitration. For international JVs, pick a neutral seat like London, Singapore, or Geneva rather than letting it default to either party's home jurisdiction. The location matters more than people realize because arbitration awards are enforced under the New York Convention, and some jurisdictions are more favorable to certain types of enforcement outcomes than others. Here's a practical example that illustrates why structure matters. A regional hospital system and a national health tech company wanted to develop a custom patient scheduling platform. They chose a contractual JV because they wanted to move fast and avoid the overhead of a new entity. The agreement covered IP ownership, revenue sharing, and data governance, but it didn't specify what would happen if one party wanted to terminate early. Two years in, the hospital system wanted out because the platform wasn't generating enough revenue, and the tech company refused because they had already invested heavily in development. Without a clear exit clause, they were stuck in limbo for eight months. The tech company eventually bought out the hospital's interest at a price neither side was happy with because there was no pre-agreed valuation formula. A corporate JV with a standard buy-sell provision would have resolved this in weeks instead of months. The tax implications vary significantly by structure and jurisdiction, so this is where you absolutely need specialized counsel rather than trying to DIY it. Corporate JVs can elect different tax treatments depending on the entity type and the parties' circumstances. Partnership JVs avoid entity-level taxation but require careful allocation of items across partners, especially when contributions are unequal. Contractual JVs mean each party reports their own share of income and deductions on their existing tax returns, which is simpler but doesn't provide the liability separation that a corporate structure offers.
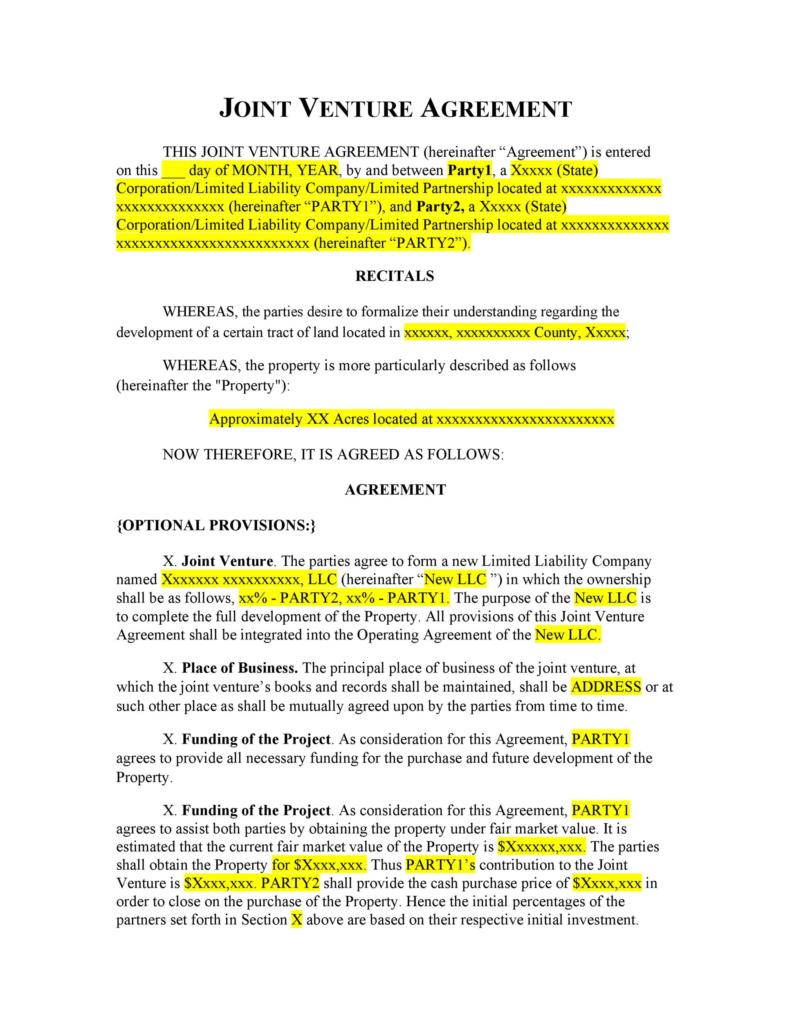
If you're drafting your own JV agreement template, start with a term sheet that covers the essential business terms before you send it to legal. Getting the economics right—capital contributions, profit distribution, management rights, exit mechanisms—is something you can't fix with better wording later. I've reviewed agreements where the legal drafting was impeccable but the underlying economics were fundamentally broken, and the parties spent more money trying to litigate around the bad deal than they would have saving the deal in the first place. The most practical advice I can give is to assume the relationship will end badly and draft accordingly. Not because you expect it to, but because the alternative is figuring out an exit strategy through a series of awkward conversations while the venture is already falling apart. A well-drafted JV agreement makes the breakup as routine as the partnership, and that's exactly how it should work.