The thing nobody tells you about retirement account planning
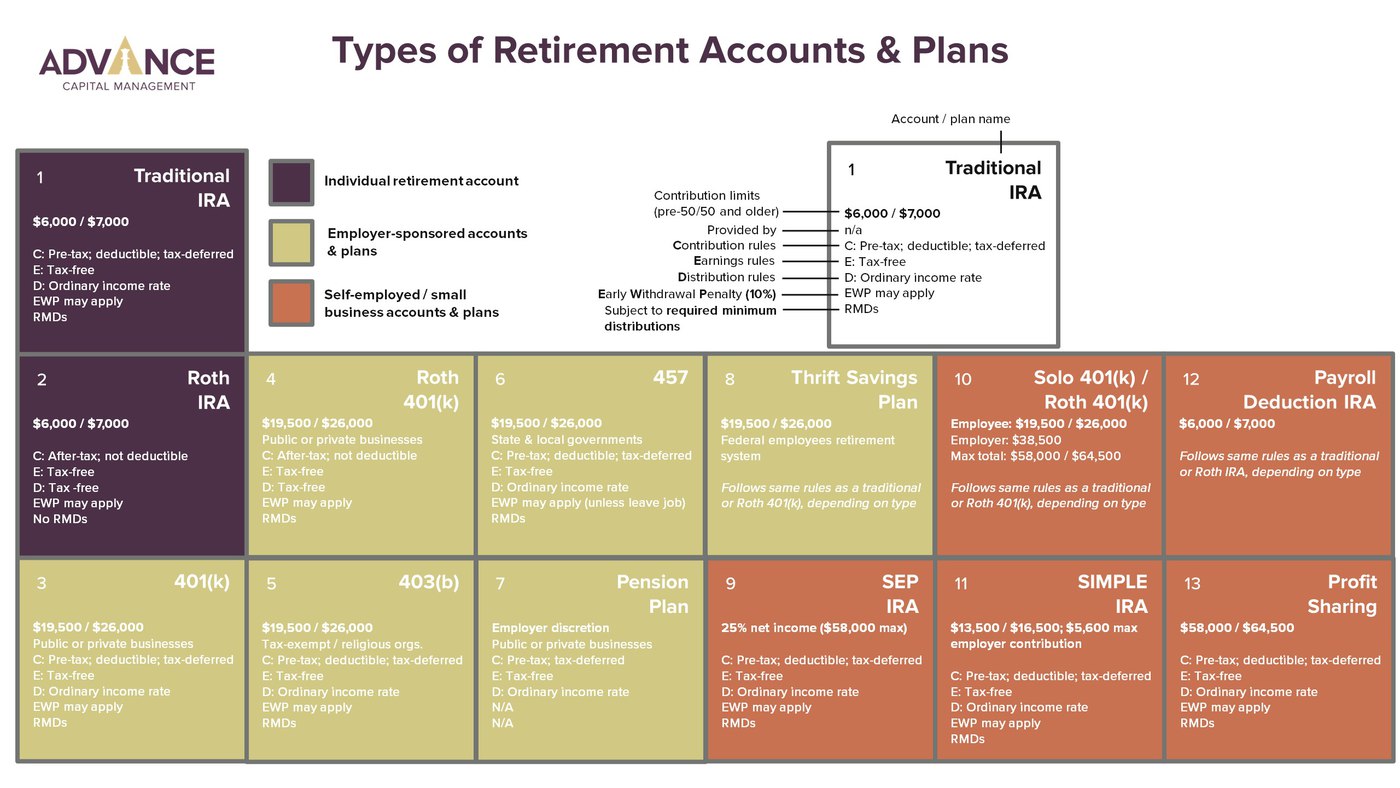
I spent about three years doing retirement plan setups for small business owners before I stopped caring about perfect spreadsheets and started using actual working tools. The problem is that most people don't realize there are at least five fundamentally different types of retirement accounts, and each one has its own contribution limits, tax treatment, and eligibility rules that change almost every year. A Types Of Retirement Accounts Worksheet is what you need when you're trying to figure out which combination makes sense for your situation instead of guessing based on advice you found on a financial blog. Here's what most people miss. You can contribute to multiple retirement accounts at the same time, and the limits don't all stack on top of each other the way you'd think. The $23,000 employee deferral limit for a 401(k) in 2025 is completely separate from the $7,000 IRA limit. But if you also have a SEP-IRA or a Solo 401(k) as a self-employed person, those employer contribution limits operate in a totally different bracket. I once had a client who maxed out his 401(k) and then assumed he couldn't do anything else tax-advantaged. He was leaving about $60,000 on the table because he didn't understand how the employer-side contributions worked for his Solo 401(k).
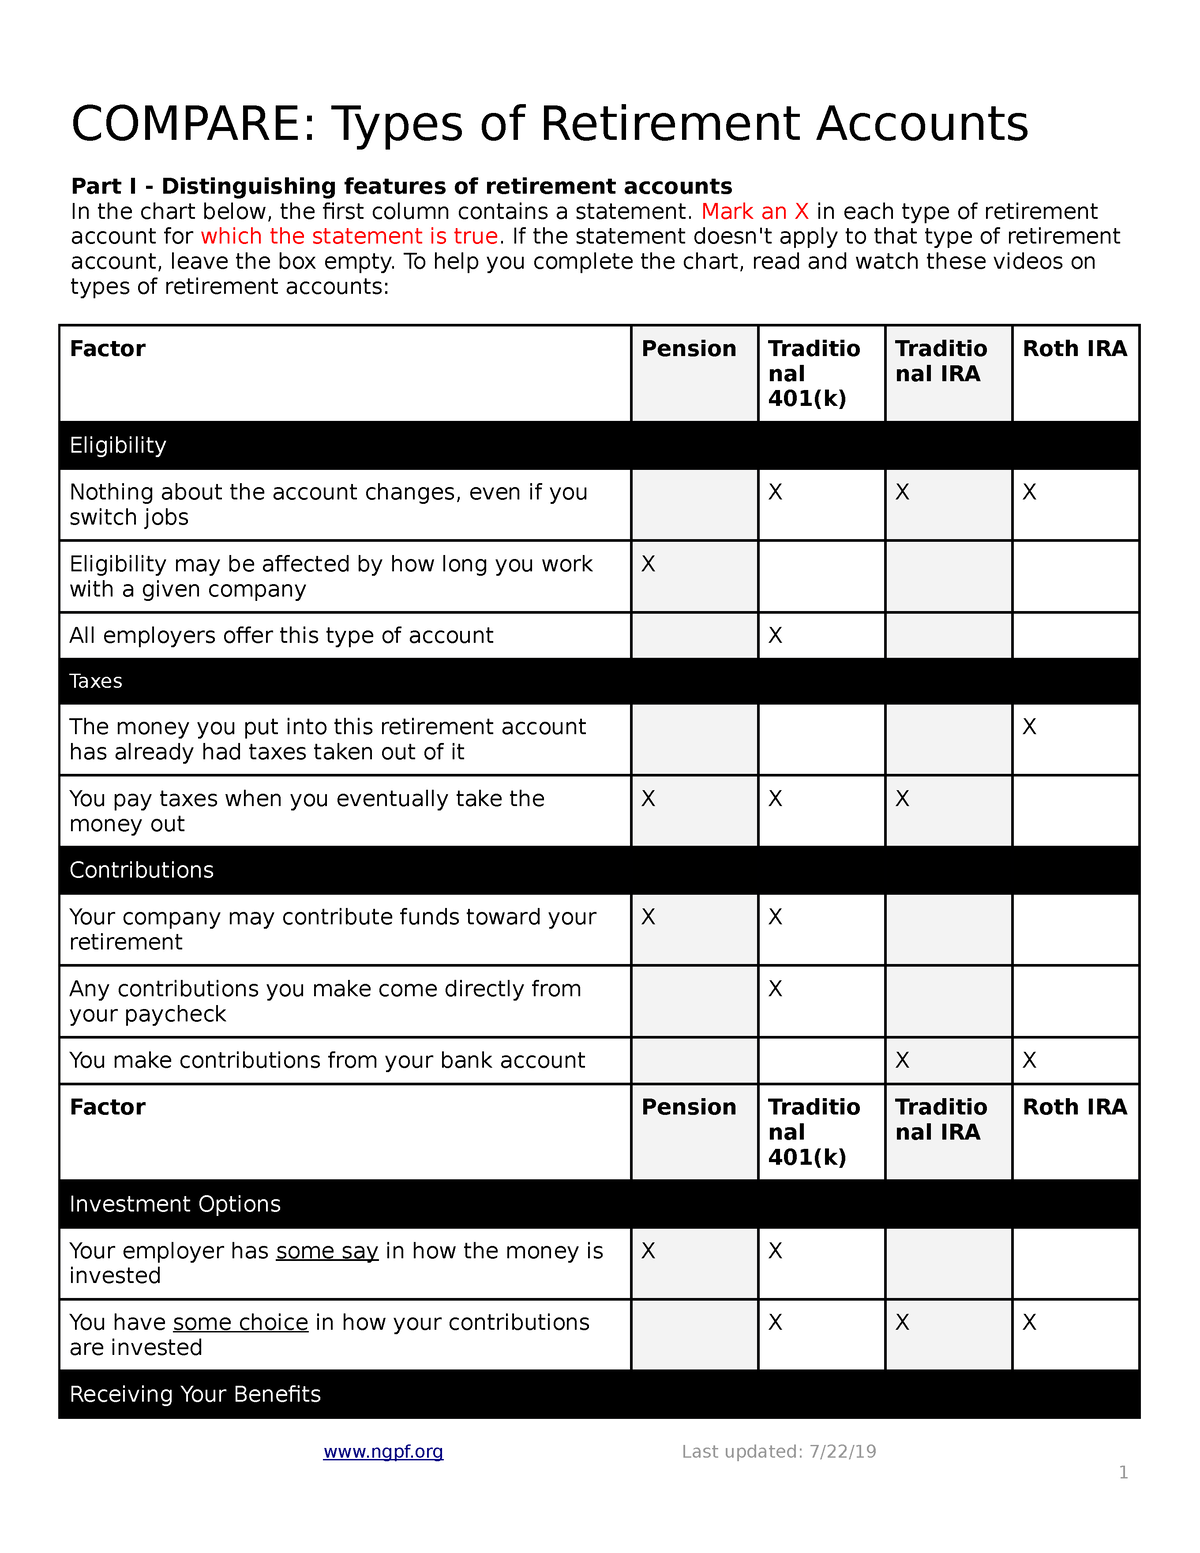
Types Of Retirement Accounts Worksheet
The basic worksheet you need covers four categories: pre-tax employer-sponsored plans, Roth employer-sponsored plans, individual retirement accounts, and catch-up provisions for people over 50. Start by listing your income level, your employment status, and whether your employer offers a retirement plan. Those three variables determine which accounts you're even eligible for. If you make $145,000 as a single filer and your employer has a 401(k), you can still contribute to a Roth 401(k) with no income limit. But your ability to deduct traditional IRA contributions phases out once your Modified Adjusted Gross Income hits certain thresholds depending on whether you or your spouse has access to a workplace plan. The worksheet should also include a section for self-employed retirement options because that's where the math gets weird. A Solo 401(k) lets you make both employee deferrals and employer profit-sharing contributions, but the total combined limit is $69,000 for 2025 if you're under 50, or $76,500 if you're 50 or older including catch-up. A SEP-IRA only allows employer contributions up to 25% of compensation or $69,000, whichever is less. The difference matters because the Solo 401(k) gives you that extra employee deferral layer that a SEP doesn't. I ran into a specific problem last year with a client who ran a side consulting business. She had a traditional IRA, a Roth IRA, and a 401(k) through her full-time job. She wanted to open a Solo 401(k) for her side income but was confused about whether she could still contribute to her existing 401(k). The answer was yes, but the interaction between her pre-tax 401(k) deferrals and her Solo 401(k) employer contributions created a pro-rata issue that most people overlook. The workaround was to roll her old 401(k) from a previous employer into her IRA first, eliminate the pre-tax balance, and then run the Solo 401(k) contributions cleanly without triggering the pro-rata rule on conversions. It took about twenty minutes to fix once you know what you're looking for.
How to actually use a retirement account comparison tool
Don't just fill in the numbers and move on. The useful part of a worksheet is seeing how the accounts interact with each other in your specific tax situation. If you're in the 24% marginal bracket now and expect to be in the 22% bracket in retirement, a traditional 401(k) makes mathematical sense. But if you're already in the 24% bracket and expect to be in the 32% bracket because of required minimum distributions or changed tax law, the Roth conversion strategy becomes worth examining. The worksheet should let you model both scenarios side by side. One counter-intuitive thing about retirement accounts that beginners consistently miss: having a large traditional IRA balance can silently eliminate your ability to do backdoor Roth conversions. The pro-rata rule applies to all your traditional, SEP, and SIMPLE IRAs combined. If you have $80,000 in a pre-tax IRA and you contribute $7,000 to a backdoor Roth, you're not converting just $7,000. You're converting a proportionate share based on the total balance across all your traditional-style IRAs. That proportion could be 92% taxable and you'd owe taxes on most of that conversion in a single year. The fix is to use a mega backdoor Roth strategy through your 401(k) if your plan allows after-tax contributions, or simply let the pre-tax IRA sit and do the backdoor Roth only after you've rolled everything into an active employer plan. The other thing most worksheets don't mention is the order of withdrawal in retirement. It matters more than people think. If you withdraw from taxable accounts first, your tax-deferred accounts keep growing and your required minimum distributions stay smaller for longer. This is called sequential spending and it's one of the most underutilized strategies in retirement planning. A good worksheet will show you the after-tax outcome of different withdrawal sequences, not just the contribution phase.
Get the Full Details

What a basic Types Of Retirement Accounts Worksheet should include
Your worksheet needs fields for current age, expected retirement age, current marginal tax rate, expected retirement tax rate, annual income, spousal income if applicable, existing retirement account balances, employer matching details, and self-employment income if relevant. That's about eight to ten variables and they should map directly to the contribution limits for each account type for the current tax year. Include a column that calculates your total potential tax-advantaged savings across all available accounts. Most people only think about their 401(k) limit and forget about the IRA, the Roth IRA, and any self-employed plan they could also use. For a self-employed person making $120,000 with no employees other than a spouse, the total could be roughly $69,000 in a Solo 401(k) plus $7,000 in a Roth IRA, which is $76,000 in tax-advantaged space. If you only looked at the 401(k) limit in isolation, you'd be off by more than half. Here's the limitation that nobody likes to hear: a worksheet is only as good as the assumptions you feed into it. It cannot predict future tax law changes, investment returns, or your personal circumstances at retirement. The 2025 contribution limits are already higher than 2024 limits in most cases, and they'll likely rise again. If your worksheet hardcodes 2024 numbers, it's already outdated. Make sure whatever tool you use pulls current IRS limits or at least has a clear date stamp so you know when the data is stale.
I found that the most practical approach is to build a simple spreadsheet with separate tabs for each account type, link them to a summary sheet that shows your combined picture, and update the IRS limit tables once a year. It takes about an hour to set up properly and then maybe fifteen minutes each year to refresh. The alternative is paying a financial advisor two hundred dollars an hour to do the same thing, which is reasonable if you need ongoing advice, but unnecessary if you just want to understand your options. The bottom line is that retirement account planning is not a one-decision problem. It's a series of decisions that compound over decades, and the differences between choosing a traditional 401(k) versus a Roth 401(k) versus a Solo 401(k) can amount to tens of thousands of dollars depending on your income trajectory. A proper worksheet strips away the confusion and shows you exactly what you're eligible for and what each choice costs or saves you in real after-tax dollars.