The Numbers Most People Get Wrong
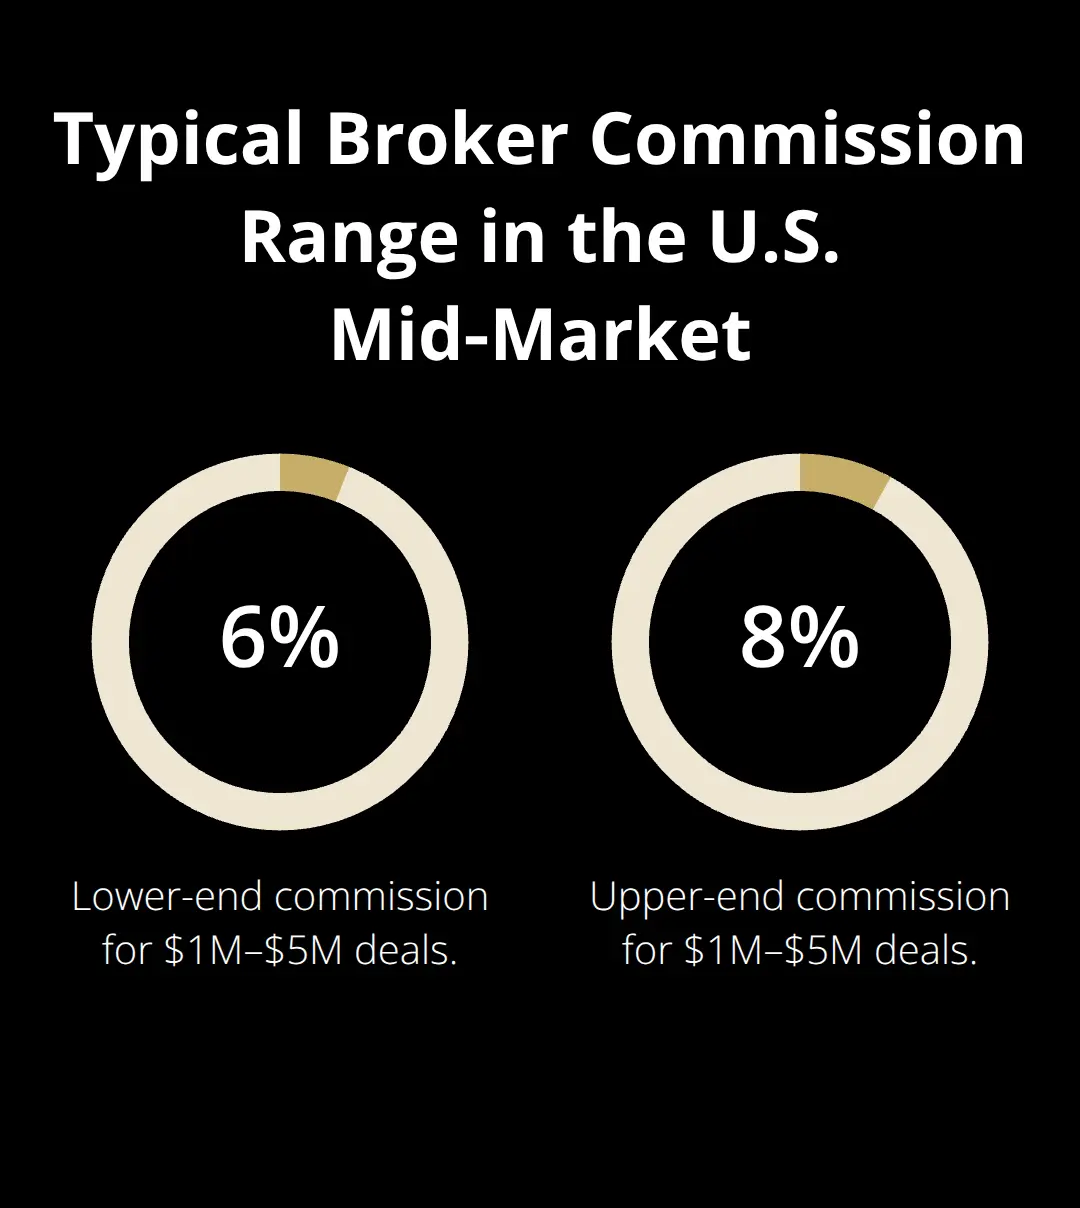
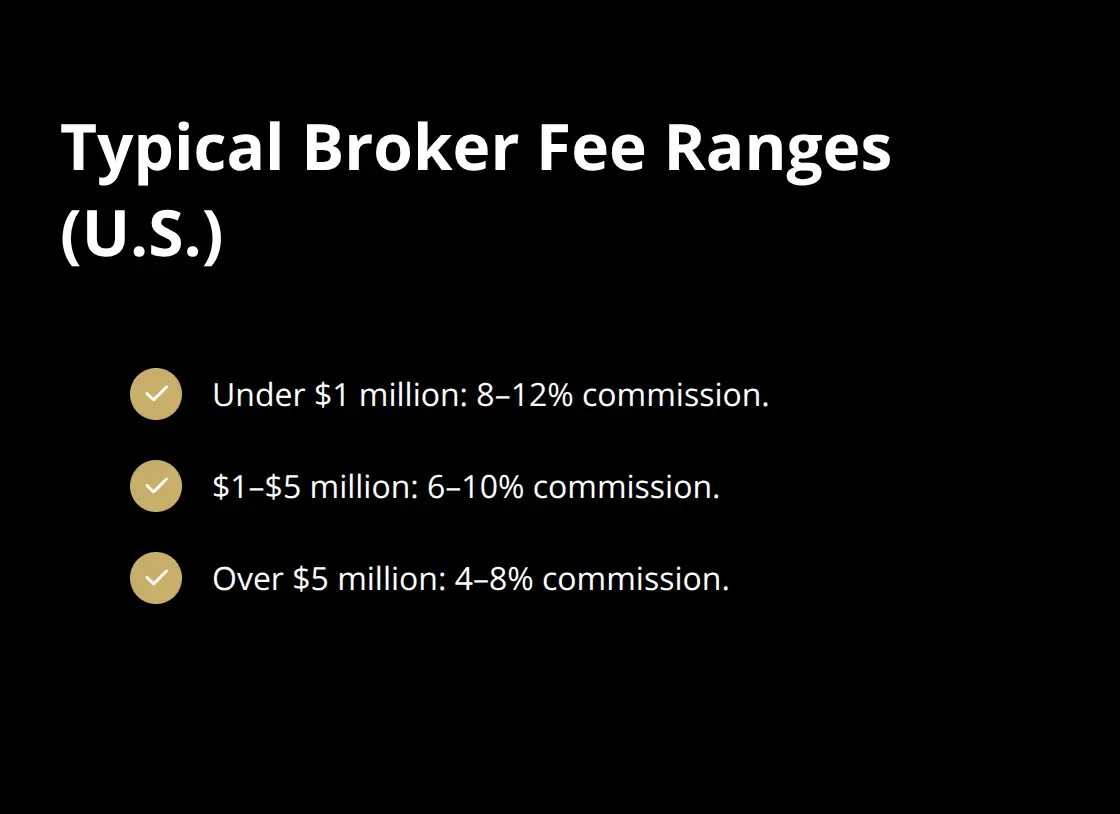
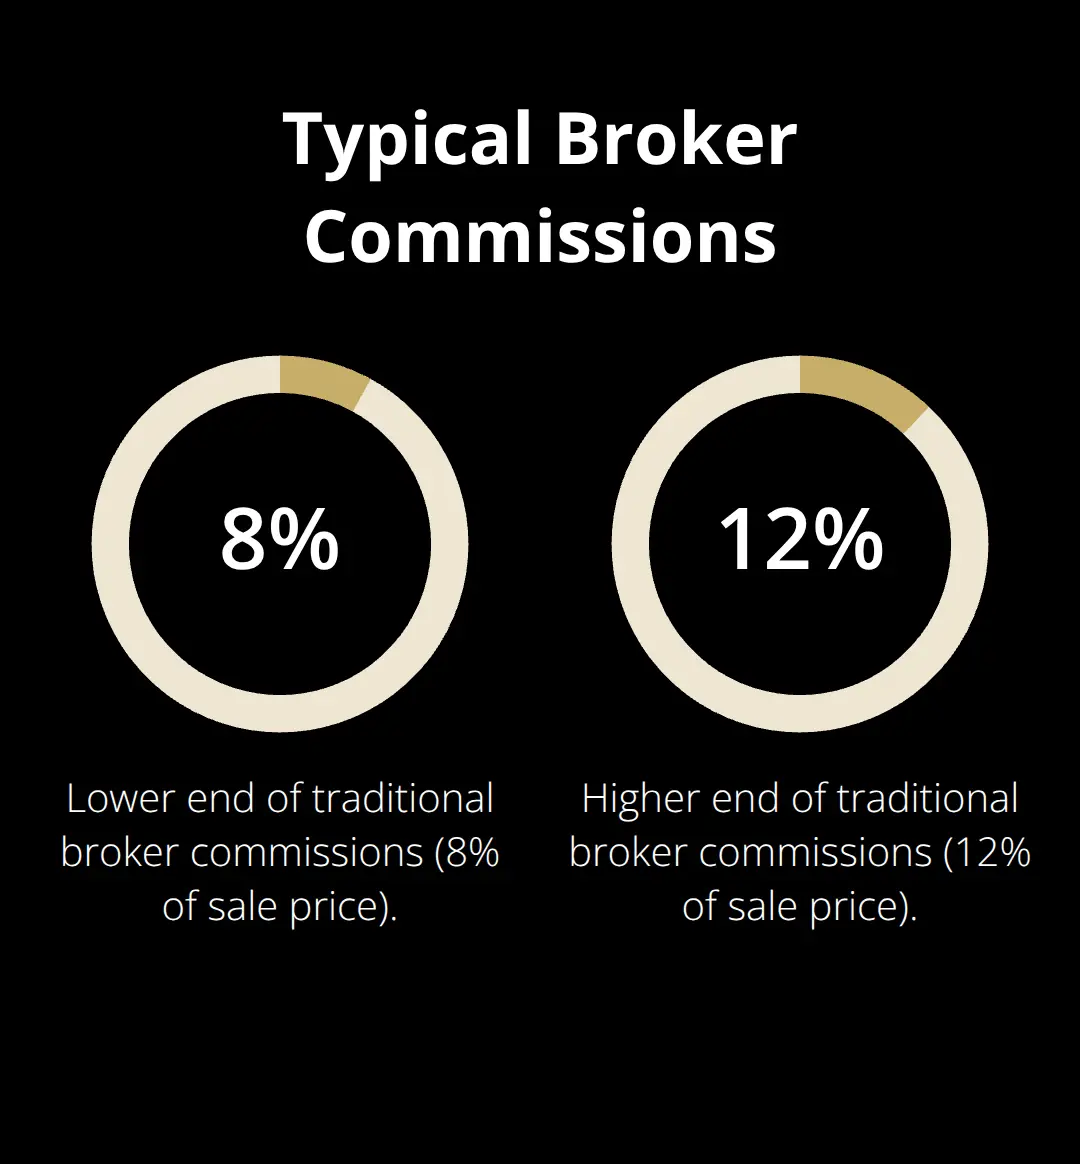
A typical business broker commission in the lower middle market runs about 8 to 12 percent of the final sale price, but that range is where the real conversation starts. Brokers charging flat percentages above $1 million tend to compress. I've seen deals where the commission drops to 5 or 6 percent once the purchase price crosses that threshold, and honestly it's more about deal economics than generosity. The broker still has to do the same work whether the business sells for $800,000 or $3 million, so at some point the percentage model breaks down. The standard structure is a listing agreement that sets the commission percentage, usually between 8 and 12 percent for small businesses under $1 million. Larger deals often shift to a sliding scale or a capped percentage. What most sellers don't realize is that the commission isn't necessarily negotiable the way you might think when a broker already has the property, the buyer database, and the operating agreement locked in. It's negotiable, but timing matters enormously. Ask before you sign, not after you've already listed. I had a dental practice owner once who signed with a broker on a flat 10 percent commission for a $2.4 million sale. Two weeks into the marketing period, a prospective buyer came in through a direct referral from the dentist's own former assistant. The broker hadn't done anything beyond the initial listing and the standard confidentiality agreement. We ended up renegotiating the commission down to 6 percent on that portion of the sale price because the broker's active involvement was minimal. The broker agreed, though I should note he also tried to argue that the confidentiality agreement itself was sufficient work. It wasn't close to sufficient, but that's the kind of pushback you'll get.
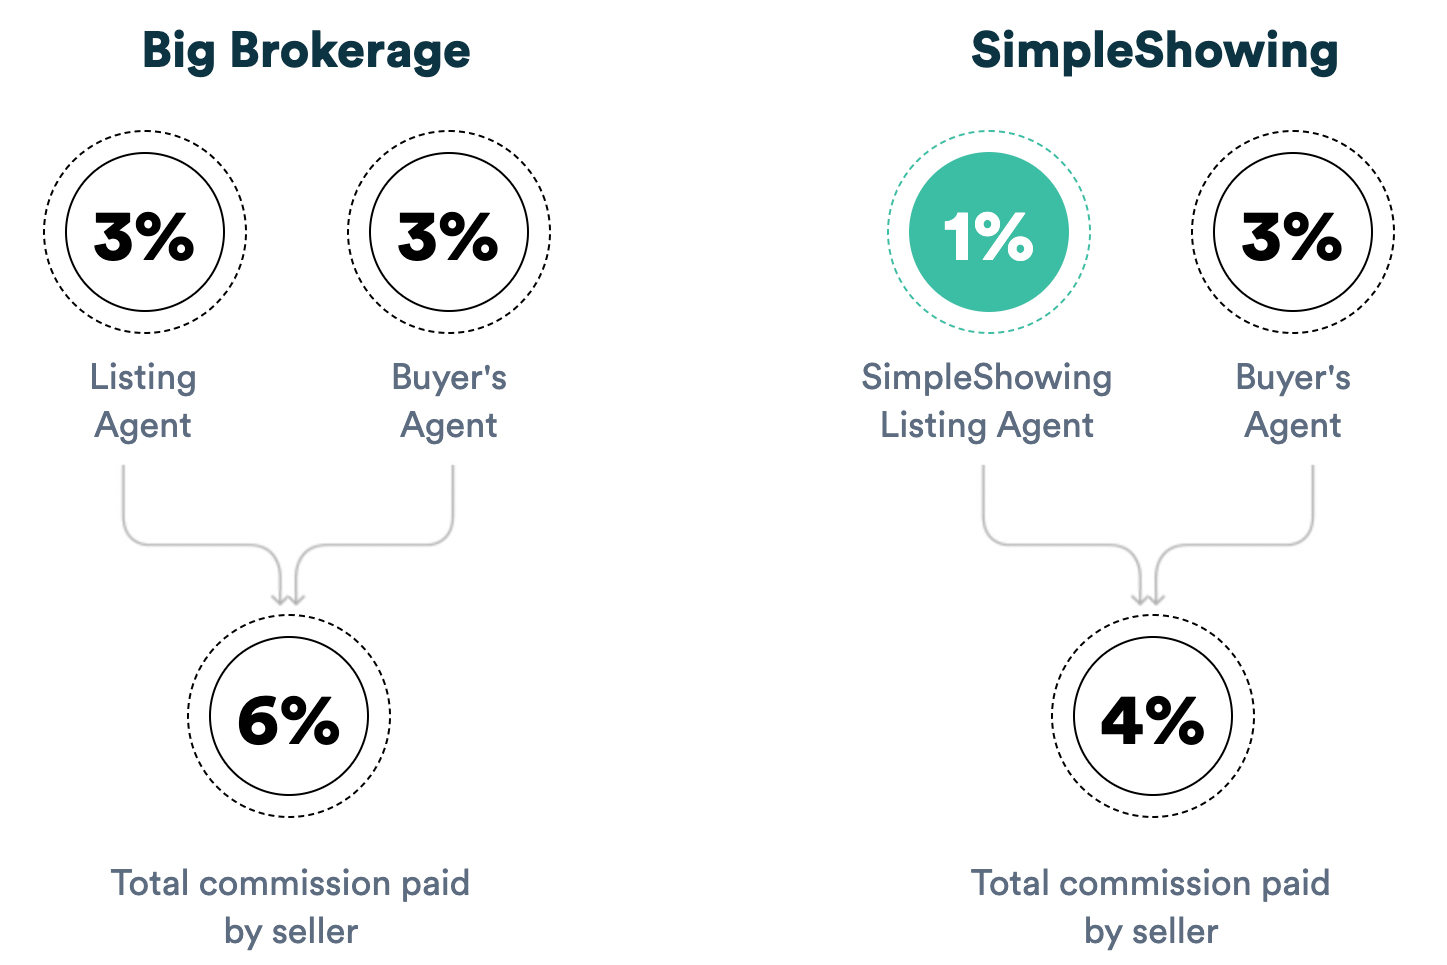
There are a few counter-intuitive things about how this works that aren't in any of the broker prospectuses. First, the commission is almost always paid by the seller, not the buyer. That's not a universal rule, but it's the overwhelming norm in the small business space. Second, the commission is typically non-refundable once a ready, willing, and able buyer is produced through the broker's efforts. This means even if the deal falls apart because the seller can't deliver clean financials, the broker still gets paid. I've seen this happen twice in ten years, and both times it was because the seller had cooked the books slightly and the buyer's due diligence found discrepancies. The broker had already delivered a buyer. The commission was owed regardless. The third thing most people miss is that brokers often double-end deals, meaning they represent both the seller and the buyer. In that scenario, the total commission might be 10 percent split between the two sides, but it's still 10 percent coming out of the seller's proceeds unless the agreement explicitly states otherwise. Some brokers will offer a slight discount for dual agency, maybe moving from 10 to 9 percent, but it's rarely worth it for the seller to push on this because the broker still has to share half with the other side anyway.
Breaking Down the Fee Structure
Below $500,000 in sale price, expect a flat 10 to 12 percent. The broker needs to cover their overhead on deals that don't generate huge absolute dollars. A 10 percent commission on a $300,000 sale is only $30,000, and after marketing costs, due diligence support, and the months of negotiation that usually follow, that's tight. Above $1 million, the percentage drops. At $1 million you're looking at roughly 8 percent. At $2 million it might be 7 percent. At $5 million you could be negotiating toward 5 or 6 percent, and sometimes flat fee arrangements become viable. The key term to understand here is the broker's listing agreement, specifically the commission clause. There are three common structures: a flat percentage of the final sale price, a graduated scale that decreases as the price increases, or a hybrid where a base percentage applies but there's a bonus kicker if the sale exceeds a certain price threshold. The bonus kicker is less common than you'd think, but I've seen it in several veterinary clinic sales where the broker got an extra 1 percent if the sale closed above a certain EBITDA multiple. Another thing that trips people up is whether the commission includes or excludes the value of inventory and equipment. In most standard agreements, the commission is calculated on the total deal value, which includes the business goodwill, the equipment, the inventory, and any working capital adjustments. This means a business with heavy equipment can have a significantly larger commission payout than one that's mostly intangible. I once worked with a manufacturing company where the equipment alone was worth 40 percent of the deal, and the seller was horrified to learn the broker was taking 10 percent on the equipment sale as well. The broker's position was technically correct based on the contract, but it was also a fair point that the broker's work wasn't concentrated on selling individual machines.
Get the Full Details
When the Commission Doesn't Apply
There are scenarios where a broker won't get paid, and understanding these matters more than most sellers realize. If the seller finds their own buyer without any broker involvement, no commission is owed. The problem is proving that the buyer wasn't introduced by the broker at any point during the marketing period. Brokers will argue that they built the network that made the sale possible even if the specific buyer came through a different channel. This is why the listing agreement should include a tail provision, also called a protection period, that specifies what happens if the seller finds a buyer within a certain window after the agreement expires. The typical protection period is 12 to 24 months, but I've seen some brokers try to push for 36 months, which is unreasonable for a business sale cycle. Twelve months is standard and fair. Another scenario where commission gets contested is when the deal falls through due to financing issues that the broker could have helped prevent. If the broker failed to pre-qualify buyers or didn't verify lender commitments, some sellers have successfully argued that the broker breached their duty of care. These arguments are difficult to win without documented evidence, but they're worth keeping in mind. I should be blunt about the limitations here. The broker commission model has real downsides. For one thing, it creates a misalignment of incentives. The broker gets paid the same percentage whether the business sells for $800,000 or $850,000, but the seller loses $50,000 in that scenario. This means the broker has less motivation to push for that extra $50,000 than the seller does. It's a structural problem that exists in every commission-based brokerage model, and it's why some sellers choose to negotiate a lower percentage with a performance bonus instead. That approach aligns incentives better, but not all brokers will agree to it.
Getting the Best Deal on Commission
If you're listing a business, shop around. Get at least three written offers from different brokers, and compare not just the commission percentage but what's actually included in that fee. Some brokers charge 12 percent but include valuation services, marketing photography, and buyer screening at no extra cost. Others charge 10 percent but bill you separately for each of those services. The total cost might end up being higher with the seemingly cheaper broker. Here's a practical workaround I use: negotiate a tiered commission where the percentage steps down at certain price milestones. A broker might agree to 10 percent on the first $500,000, 8 percent on the next $500,000, and 6 percent on anything above that. This structure keeps the broker motivated at every level because they still earn more on a higher sale price, and it protects you from paying 10 percent on a deal that somehow closes well above the expected range. I've used this approach successfully on three separate transactions over the past five years, and every broker I've proposed it to has accepted it without much resistance. They seem to prefer it over a flat lower percentage because the upside potential remains. Another practical tip is to avoid signing exclusive listing agreements for longer than six months. Longer exclusivity periods give brokers less urgency to close quickly, and they also make it harder for you to switch brokers if the marketing isn't producing results. Six months is plenty of time for a properly priced and marketed business to attract serious buyers. If it's not selling in six months, the issue is likely pricing or condition, not the broker's effort.
What Happens After the Sale
The commission is usually due at closing, but the timing of when it's earned versus when it's paid can create complications. Some brokers will demand partial payment upfront to cover marketing expenses, typically 1 to 2 percent of the projected commission. This is standard practice and not something you should fight on. However, if a broker asks for more than that as an upfront fee, that's a red flag. Legitimate brokers make their money on the successful close, not on upfront payments. The ones who rely heavily on upfront fees are usually brokers who don't expect to close many deals. Once the deal closes and the commission is paid, there's nothing more to negotiate unless the listing agreement specifies ongoing responsibilities that extend beyond closing. Some brokers offer post-closing advisory services for additional fees, but these are optional. Make sure you understand exactly when the broker's obligations end and what, if anything, continues afterward. In my experience, most brokers consider their job done once the escrow closes, but it's worth confirming this in writing rather than assuming.