Tracking your money every day isn't as complicated as people make it seem, but getting it right matters more than you'd think.
Most people treat finance journaling like it's some grand spiritual practice. It isn't. It's data entry with purpose. The Ultimate Finance Journal Daily Log is just that—a daily record of every transaction, cash flow movement, and balance update so you actually know where your money is going instead of guessing at month-end when you're stressed about bills. I set one up for myself about four years ago after realizing my monthly budget reviews were basically fiction. I'd write down estimates for groceries, utilities, entertainment, and half the numbers felt made up. The first time I actually compared my logged daily spend against what my bank statement showed, I was off by about $400 across a single month. That gap was mostly small purchases I hadn't mentally categorized as "spending"—subscriptions I forgot I had, automatic transfers, things charged to a secondary card I wasn't tracking closely.
Setting Up Your Ultimate Finance Journal Daily Log
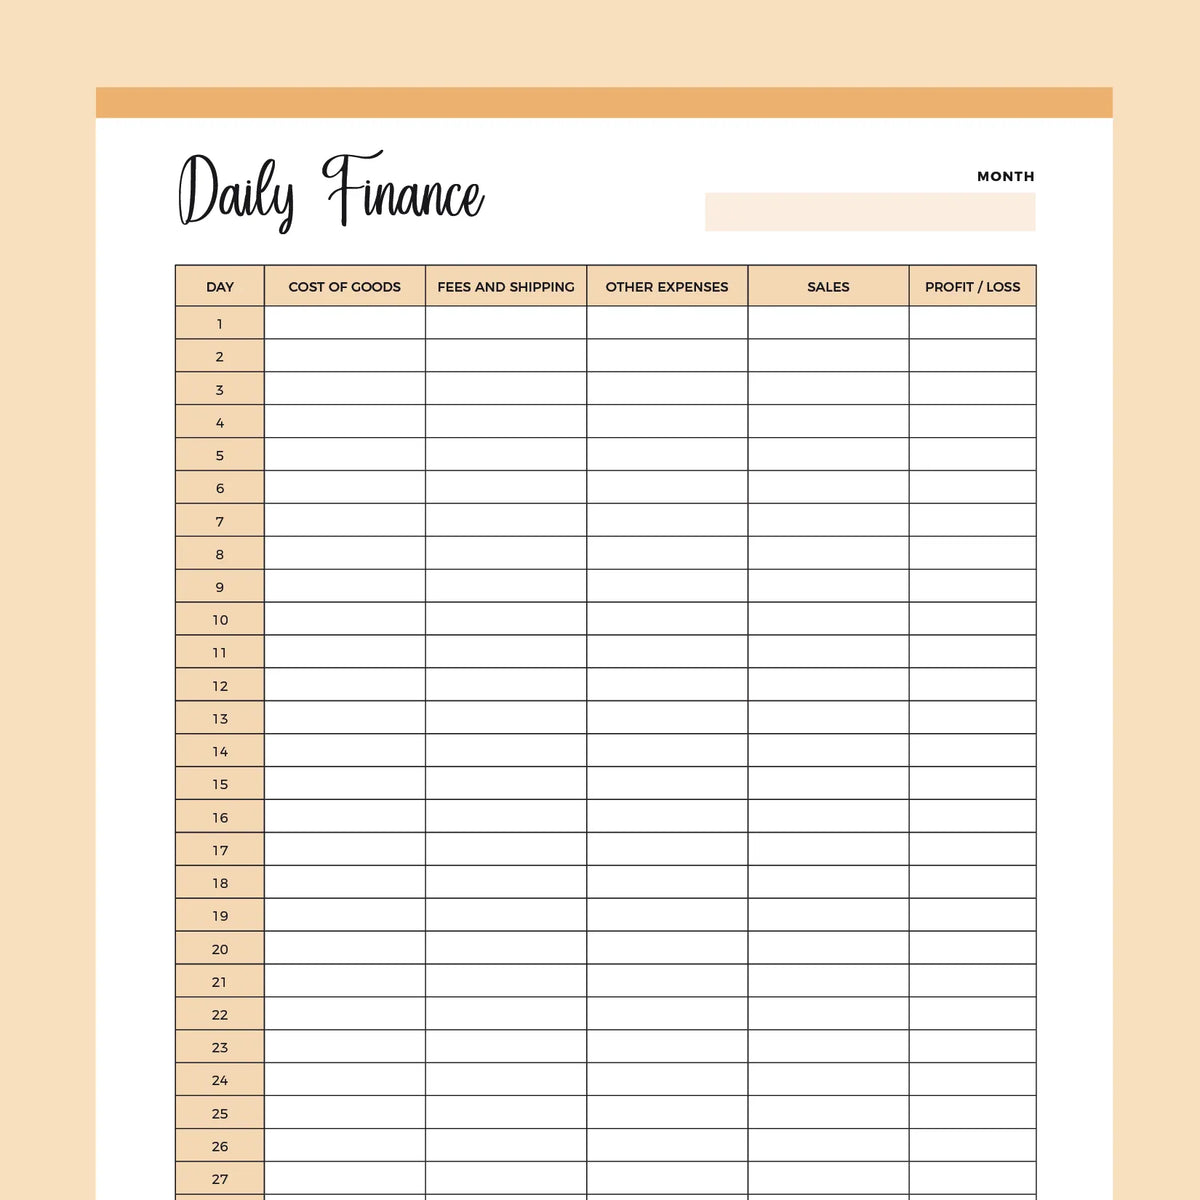
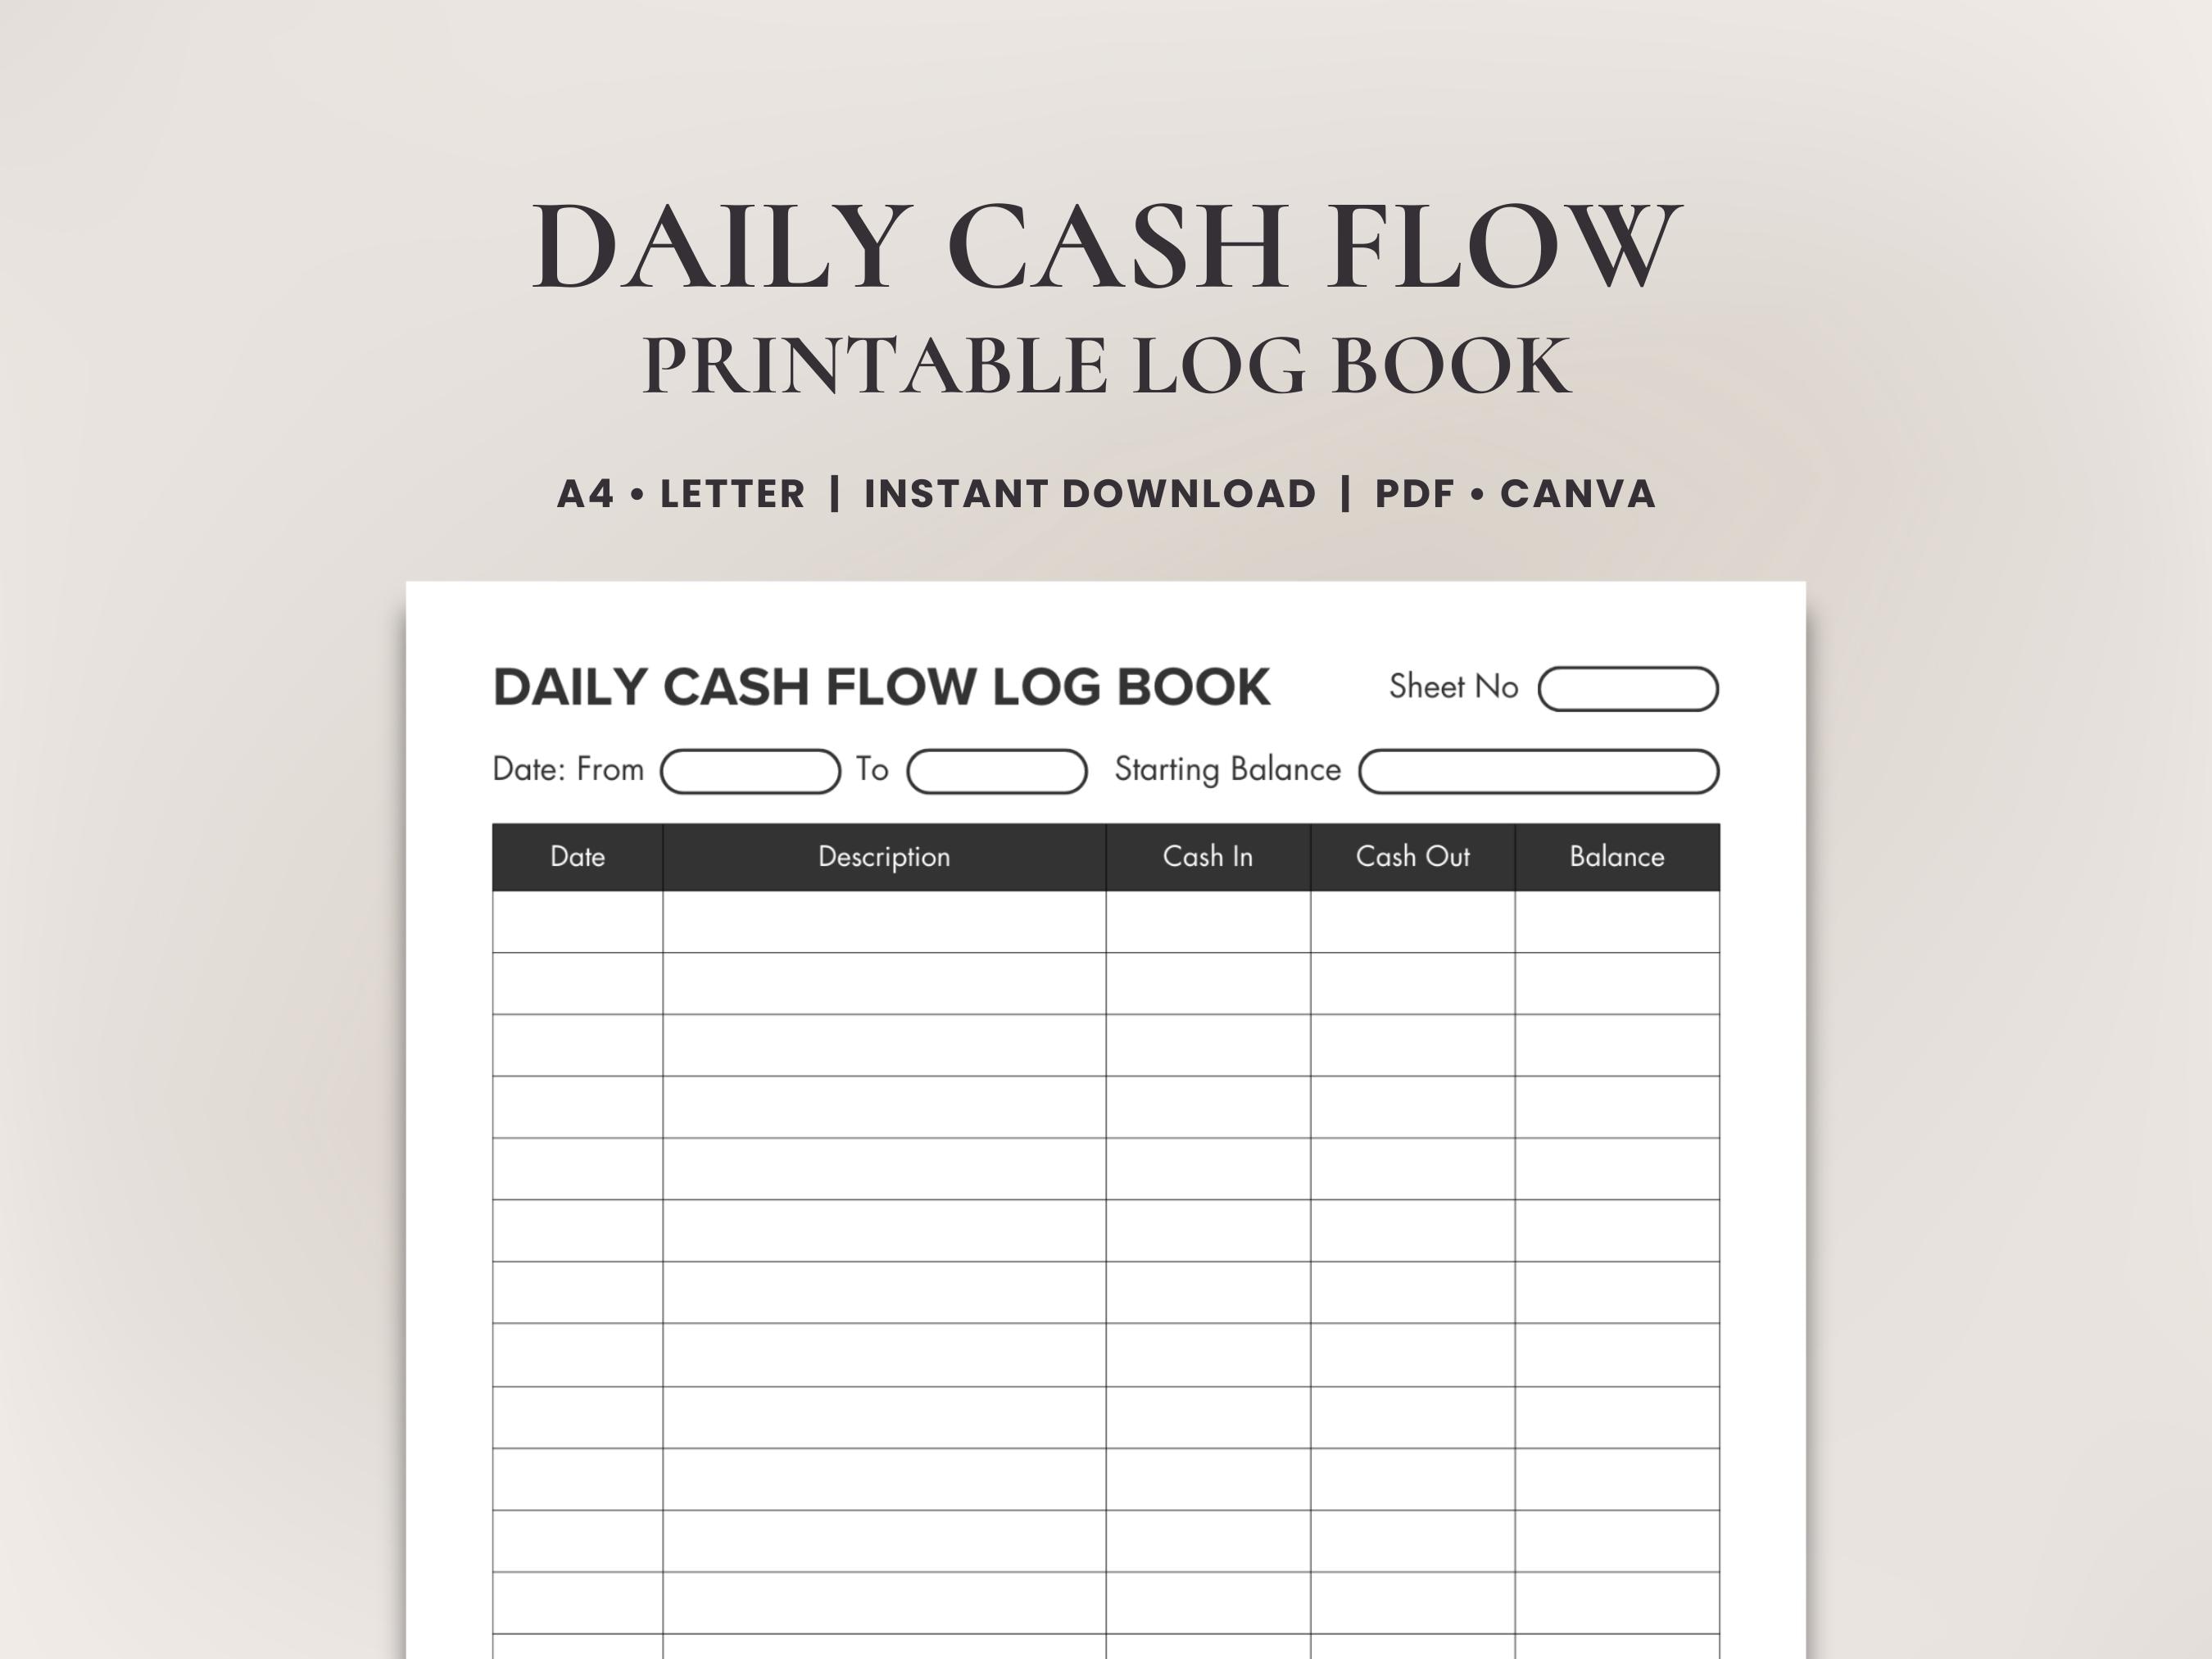
Start with the simplest possible structure. You need four columns minimum: date, description, amount, and category. After that, add a notes column because something will always be unclear the day you record it and you'll want to remember why that $87 charge happened three weeks later. I use a spreadsheet for this because it's searchable, filterable, and doesn't require an app subscription that might vanish if the company folds. The key insight nobody mentions is that you should log transactions on the day they post, not the day they occur. There's a difference. If you buy something Tuesday but it doesn't actually clear Wednesday, logging it Tuesday creates a phantom balance that makes your daily check-ins confusing. The bank hasn't taken the money yet. Your log shouldn't pretend it has. This distinction saved me about twenty minutes per week in reconciliation time because I stopped chasing discrepancies that existed only in my records, not in reality. Categories matter more than you'd expect but they shouldn't be elaborate. Six to eight broad categories covers almost everything. I use: groceries, dining out, transport, subscriptions, healthcare, utilities, personal spending, and savings contributions. If something falls outside these, it goes into a catch-all bucket rather than creating a brand new category. New categories invite procrastination because you spend more time organizing than actually logging.
What Actually Happens When You Do This Consistently
After about six weeks of daily logging, your spending patterns become visible. This isn't mystical. It's just repeated exposure to data. You start noticing that your "personal spending" category consistently hits above a certain number around mid-month. Or that your transport costs spike on specific weekdays. The pattern emerges from the accumulation of entries, not from any single one. Here's the part most guides don't cover: your first month will feel tedious and pointless. You'll wonder why you're spending twenty minutes a day writing down $4.50 coffee purchases. Trust the process. The visibility compounds. By month three, the time you spend logging drops to about five minutes because your brain has already categorized everything as it happens. You're not making decisions anymore. You're just recording them. The habit rewires itself through repetition.
Get the Full Details
A Problem I Ran Into and How I Fixed It
About nine months in, I hit a wall with recurring charges. There were enough subscriptions and automatic payments that I kept forgetting to log them, and when I caught up on a week of entries, the balance didn't match my bank. The issue was double-counting—some automatic payments appeared in my bank feed that I'd already manually entered, and others I completely missed because they processed on days I wasn't actively reviewing. My workaround was straightforward but took me a while to realize: I started using a simple tag system for recurring items. Instead of logging them daily, I marked subscriptions with a "R" tag and set a weekly reminder to verify they posted correctly. For anything under $20 that I knew was recurring, I stopped logging each instance and instead calculated a monthly average at the end of each cycle. This cut my daily logging time from roughly fifteen minutes down to about four and eliminated the double-counting problem entirely. The tradeoff is that you lose granular tracking on recurring expenses, but you gain accuracy on the rest of your data, which is the harder thing to get right.
When This Method Breaks Down
The Ultimate Finance Journal Daily Log works well for individuals and couples with straightforward income and spending profiles. It struggles with multiple income streams that change weekly—freelance work, side businesses, variable commissions. If your income fluctuates more than twenty percent month to month, a daily log gives you a false sense of precision because you're tracking every dollar in but your dollar-out patterns are the same as anyone else's. In those cases, a rolling three-month average approach to income combined with daily expense logging tends to be more accurate. Another limitation: this system requires you to actually have access to your transaction data in real time. If you're using a bank that takes two or three days to reflect posted transactions, your log will always be slightly behind. Not a dealbreaker, but worth noting if you expect perfect alignment between your spreadsheet and your bank balance at any given moment. If your financial situation involves complex investments, crypto holdings, or multi-currency accounts, a daily log alone won't capture the picture. You'd need supplemental tracking for those asset classes. A spreadsheet for expenses and a separate tracker for investments works better than trying to force everything into one document.
Practical Numbers That Matter
A well-maintained daily log typically takes between five and fifteen minutes per day once the habit is established. The first two weeks usually run longer because you're building the routine. Expect twenty to thirty minutes daily during that adjustment period. Most people quit during weeks one and two, not because the system is flawed but because the time investment feels disproportionate to an immediate payoff. There is no immediate payoff. The value shows up at month three and beyond. Reconciliation time—the process of matching your log against actual bank statements—should take no more than ten minutes per week. If it takes longer, your categorization is probably too granular or you're missing entries frequently enough that catching up becomes a chore. Both are fixable by simplifying your categories and logging same-day instead of batching entries at week's end.
Bottom Line
The Ultimate Finance Journal Daily Log is a boring system that produces reliable results if you stick with it. It won't make you richer on its own. It won't fix bad spending habits. But it will give you accurate information about your money, and accurate information is the foundation for every financial decision that comes after. Everything else is optional.