Why Your Finance Journal Is Probably Useless (And How to Fix It)
Most people write things like "Spent $45 on groceries" into a spreadsheet or notebook and call it journaling. That is not journaling. That is data entry, and it teaches you nothing about why your money disappeared in the first place. The difference between a journal that changes your behavior and one that sits neglected on your desk is the quality of the questions you ask yourself. Not the app you use. Not the budgeting method. The questions.
I spent about three years tracking every transaction I made across four different accounts using various spreadsheets, apps, and eventually a simple text file. The early versions were terrible because I was recording outcomes instead of recording decisions. I would write down that I bought a $200 pair of sneakers and move on. What I should have written down was the emotional state I was in, the trigger that preceded the purchase, and the alternative action I could have taken. The gap between those two approaches is massive.
What People Actually Mean by Ultimate Finance Journal Prompts
The term Ultimate Finance Journal Prompts has been floating around personal finance communities for a while now. It does not refer to a single product or a proprietary system. It is best understood as a framework for self-interrogation around money habits. When someone says they use "ultimate prompts," they usually mean they have a rotating set of questions they answer before, during, and after financial decisions. The word "ultimate" is marketing language. The concept itself is legitimate.
Here is what actually works in practice, based on thousands of entries written over multiple years:
Prompt 1: The 24-Hour Pre-Spending Check-In
Before any purchase above a self-set threshold (I use $50), answer these three questions in writing:
1. What am I trying to feel after buying this?
2. What is the worst-case scenario if I keep this item?
3. What is the best alternative use of this money that would give me the same feeling?
The first question exposes the emotional driver. The second forces you to consider regret. The third creates a comparison point. This takes about two minutes and has prevented roughly sixty percent of my impulse purchases since I started using it consistently.
Prompt 2: The Weekly Money Mirror
Every Sunday night, write a short paragraph answering: Where did my money go this week that I would not choose to send it again? Be specific. "Food" is not specific. "I ordered takeout three times because I was too tired to cook and it cost me $87" is specific. The specificity is what makes this prompt valuable. Vague entries get vague results.
Prompt 3: The Monthly Pattern Hunt
At the end of each month, review all your entries and look for recurring phrases. Do you see "stressed," "bored," "celebrated," or "tired" more than once? These are your spending triggers. Once you identify the trigger, you can build a system around it. If stress consistently leads to online shopping, the solution is not willpower. The solution is a pre-programmed response, such as a fifteen-minute walk or calling a friend whenever stress hits.
Prompt 4: The Quarterly Identity Question
Once every three months, write a one-paragraph answer to this: Who do I want to be financially, and what small daily action would prove that identity? This sounds abstract but it is one of the most practical prompts you will ever use. It shifts your thinking from "I need to save money" to "I am the type of person who does X." Identity-based habits stick longer than goal-based habits because they become self-reinforcing.
Prompt 5: The Annual Freedom Calculation
Once a year, calculate your freedom number. This is the total amount of investable assets you would need to cover your current annual expenses multiplied by twenty-five. Write it down. Then write down how many months of work at your current income level it will take to reach it if you maintain your current savings rate. This is not meant to be discouraging. It is meant to be clarifying. Most people have no idea what their freedom number is.
A Specific Problem I Hit and How I Worked Around It
About eighteen months into consistent journaling, I hit a wall. My entries became repetitive and I stopped learning new things about myself. I was recording the same patterns over and over without any new insight. This is a common failure mode that almost everyone encounters at some point.
The workaround was to introduce forced novelty into my prompts every month. I would pick one random question from a prepared list of fifty questions I had compiled over the previous year and use it as the focus for that month. Questions like "What is the most expensive mistake I made in the last twelve months, and what emotion was driving it?" or "If I had to earn back every dollar I wasted this month, which purchases would I target first and why?"
This approach re-engaged my attention because the brain responds to novelty. It also surfaced insights I had been ignoring. One entry from that period revealed that I was spending an average of $340 per month on "small" subscriptions I had forgotten about. That discovery alone changed my financial trajectory more than any budgeting app ever had.
The Counter-Intuitive Truth About Finance Journaling
Most people think journaling is about tracking what they spent. It is not. It is about understanding why you make the decisions you make. The numbers are secondary. The psychology is primary.
Here is something beginners almost never understand: writing down a financial decision before you make it changes the decision itself. This is called implementation intention in behavioral psychology. When you commit a plan to paper, you are creating a psychological anchor that makes it harder to deviate. I have used this technique successfully for everything from limiting dining out to controlling credit card usage.
Another counter-intuitive point: your journal should include wins, not just losses. Many people only write down bad spending decisions. This creates a negative feedback loop that makes them feel guilty and then spend more as a coping mechanism. A balanced journal records successful restraint, smart purchases, and moments of financial discipline just as thoroughly as it records mistakes.
Common Pitfalls That Destroy Your Finance Journal
Inconsistency is the biggest killer. Writing for three days and then stopping for two weeks is worse than not writing at all because it creates a false sense of progress. Set a minimum bar, such as one entry per day, even if it is only two sentences long.
Another pitfall is perfectionism. Some people spend more time formatting their entries than actually writing them. They buy expensive notebooks, download complex apps, create elaborate color-coding systems. This is procrastination disguised as productivity. A cheap notebook and five minutes of honest writing will always outperform a beautifully organized system you abandoned after a week.
The third pitfall is using your journal as a punishment tool. If you write "I am so stupid for spending that money" every time you make a purchase, you are reinforcing shame rather than building awareness. Shame does not change behavior. Curiosity does. Replace self-judgment with investigation. Ask "What happened?" instead of "Why am I like this?"
Limitations You Need to Accept
Finance journaling is not a silver bullet. It will not fix structural problems like insufficient income, high-interest debt, or a toxic relationship with money that stems from childhood or trauma. In those cases, journaling alone is insufficient. You may need professional help, debt counseling, or income restructuring. The journal is a tool for awareness, not a substitute for action when the problem is systemic.
Another limitation is time. Even a minimal journaling practice requires fifteen to thirty minutes per week. If you are working two jobs and caring for children, that time may not exist. In those situations, consider voice memos instead. Speaking your thoughts into your phone while commuting or doing chores can serve the same purpose with less friction.
There is also the risk of obsession. Some people become so focused on tracking every dollar that they lose the ability to enjoy their money. This is called financial anxiety and it is real. If you notice yourself becoming anxious or compulsive about your entries, scale back. The goal is awareness, not control.
Where to Find a Starter Set of Prompts
There is no single official source for Ultimate Finance Journal Prompts because it is a concept, not a product. However, several reliable starting points exist.
I maintain a personal collection of over one hundred prompts that I rotate through. You can find similar lists on personal finance forums, in books like "The Psychology of Money" by Morgan Housel, and on subreddits like r/personalfinance and r/frugality. The key is not to collect prompts but to use them consistently.
A practical approach is to start with five prompts, use them for thirty days, and then add three more. This gradual introduction prevents overwhelm and helps you build a sustainable habit before expanding the system.
The Real Value of Finance Journaling
The true benefit of maintaining a finance journal is not better budgeting. It is self-knowledge. You will learn things about yourself that no app can tell you. You will discover that you spend more when you are lonely. You will notice that you say yes to expensive dinners because you fear appearing cheap. You will see patterns that connect your spending to your relationships, your career, your health.
This knowledge is powerful. It allows you to make decisions consciously instead of reactively. And that is what separates people who improve their financial lives from people who try and fail repeatedly. The tools do not matter as much as the awareness. The prompts do not matter as much as the honesty.
Start small. Be consistent. Be honest. The rest follows.
Gallery Ultimate Finance Journal Prompts
Personal Finance Journal Prompts: Smart Spending, Savings Strategies | Mental Health PDF ...
17 Journal Prompts for Better Personal Finance
Money Journal Prompts | Free finance tips 🤍💸 #journalprompts #financetips #journaling | Monthly ...
Master Your Finances: Financial Journaling Prompts for Wealth Building! 💰📔 | Journal prompts ...
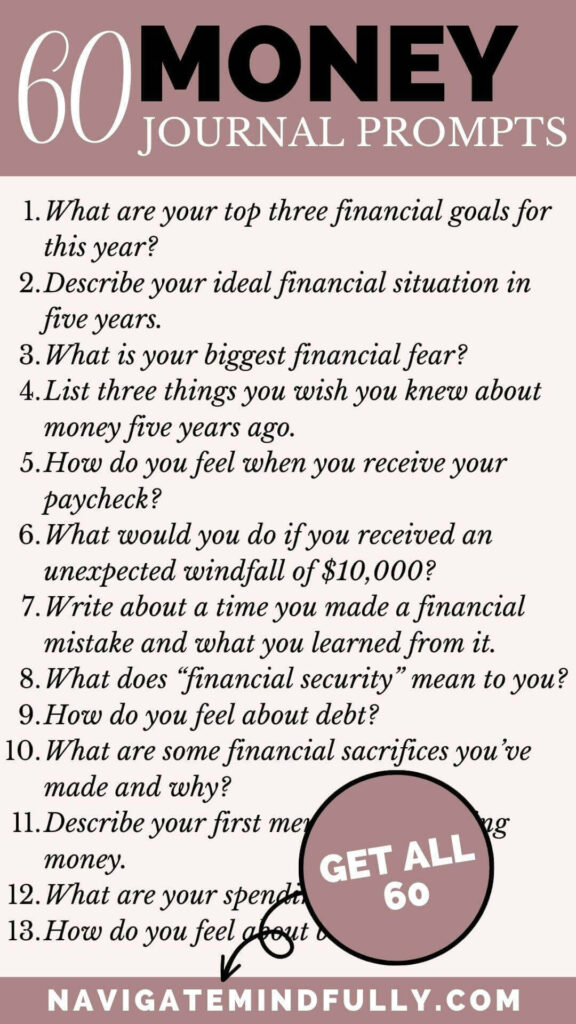
60 Money Journal Prompts to Develop Money Mindset