Most people think underwriting is just a rubber stamp before closing. It isn't. It's a risk assessment funnel that will flag things you didn't even know your lender could see. I've watched perfectly qualified buyers get stuck for three weeks because of a documented deposit trail issue that had nothing to do with credit score.
Underwriting Home Loan: What Actually Happens in the Queue
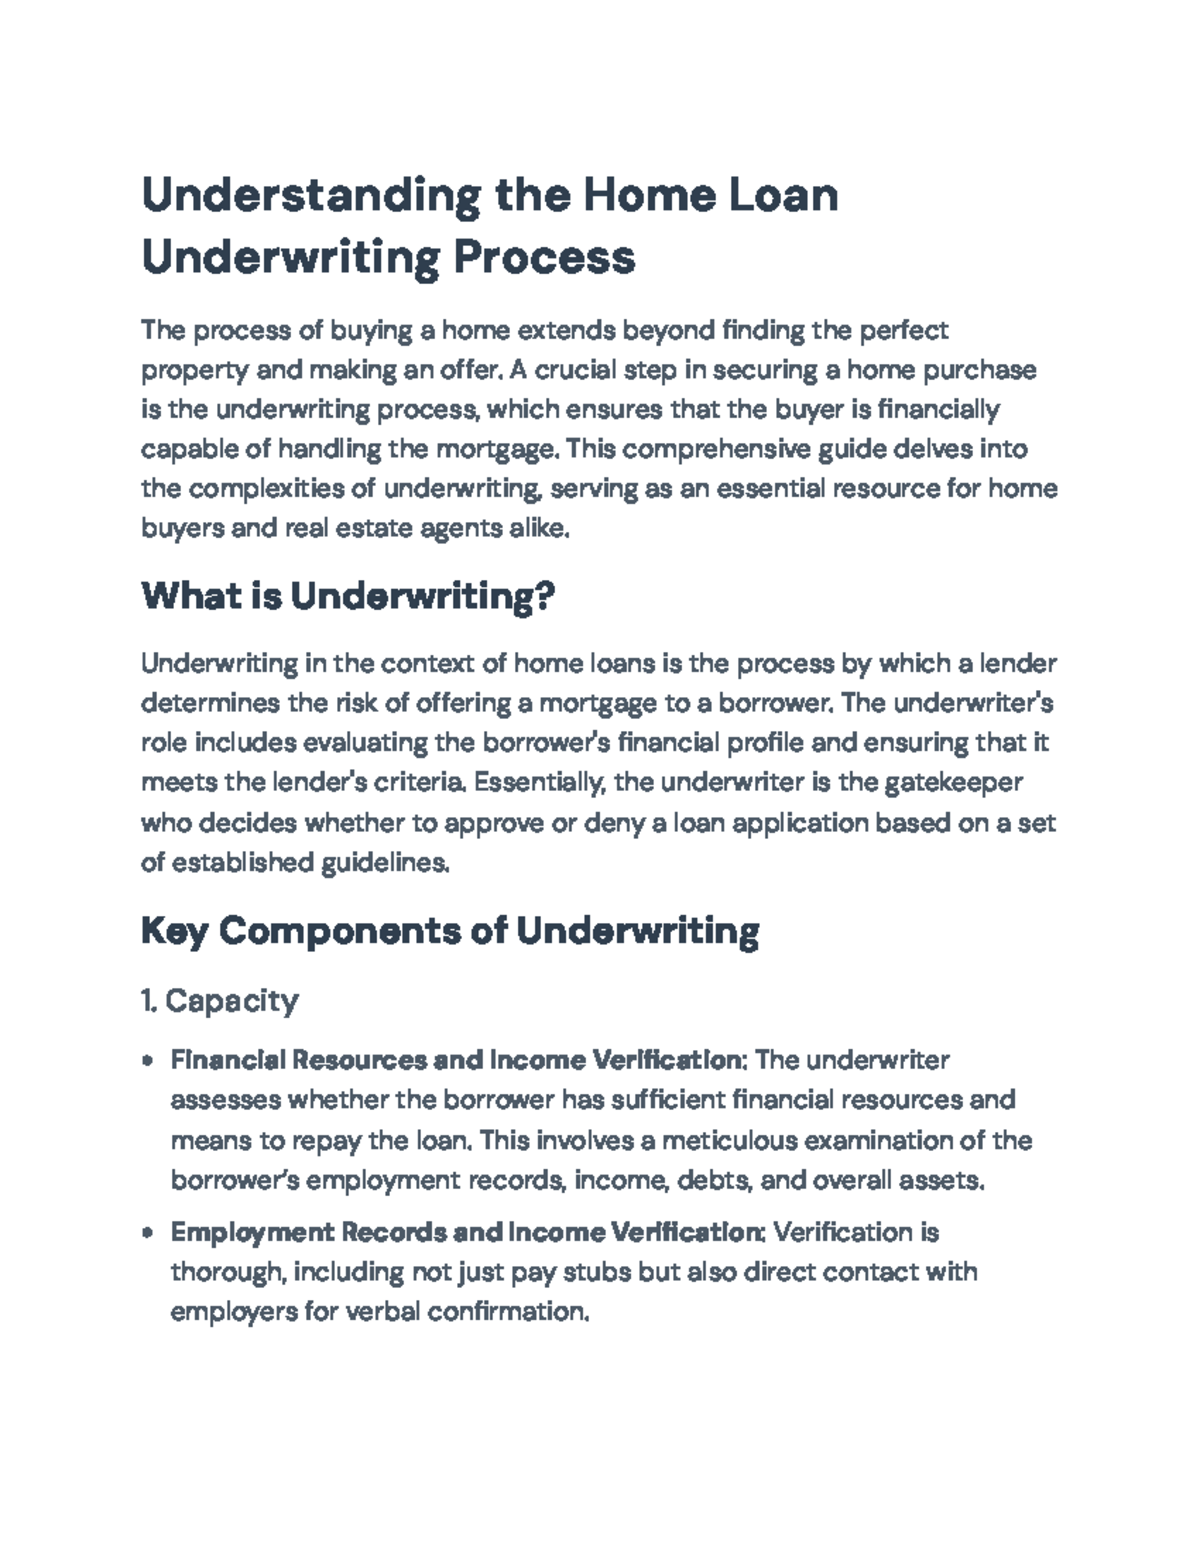
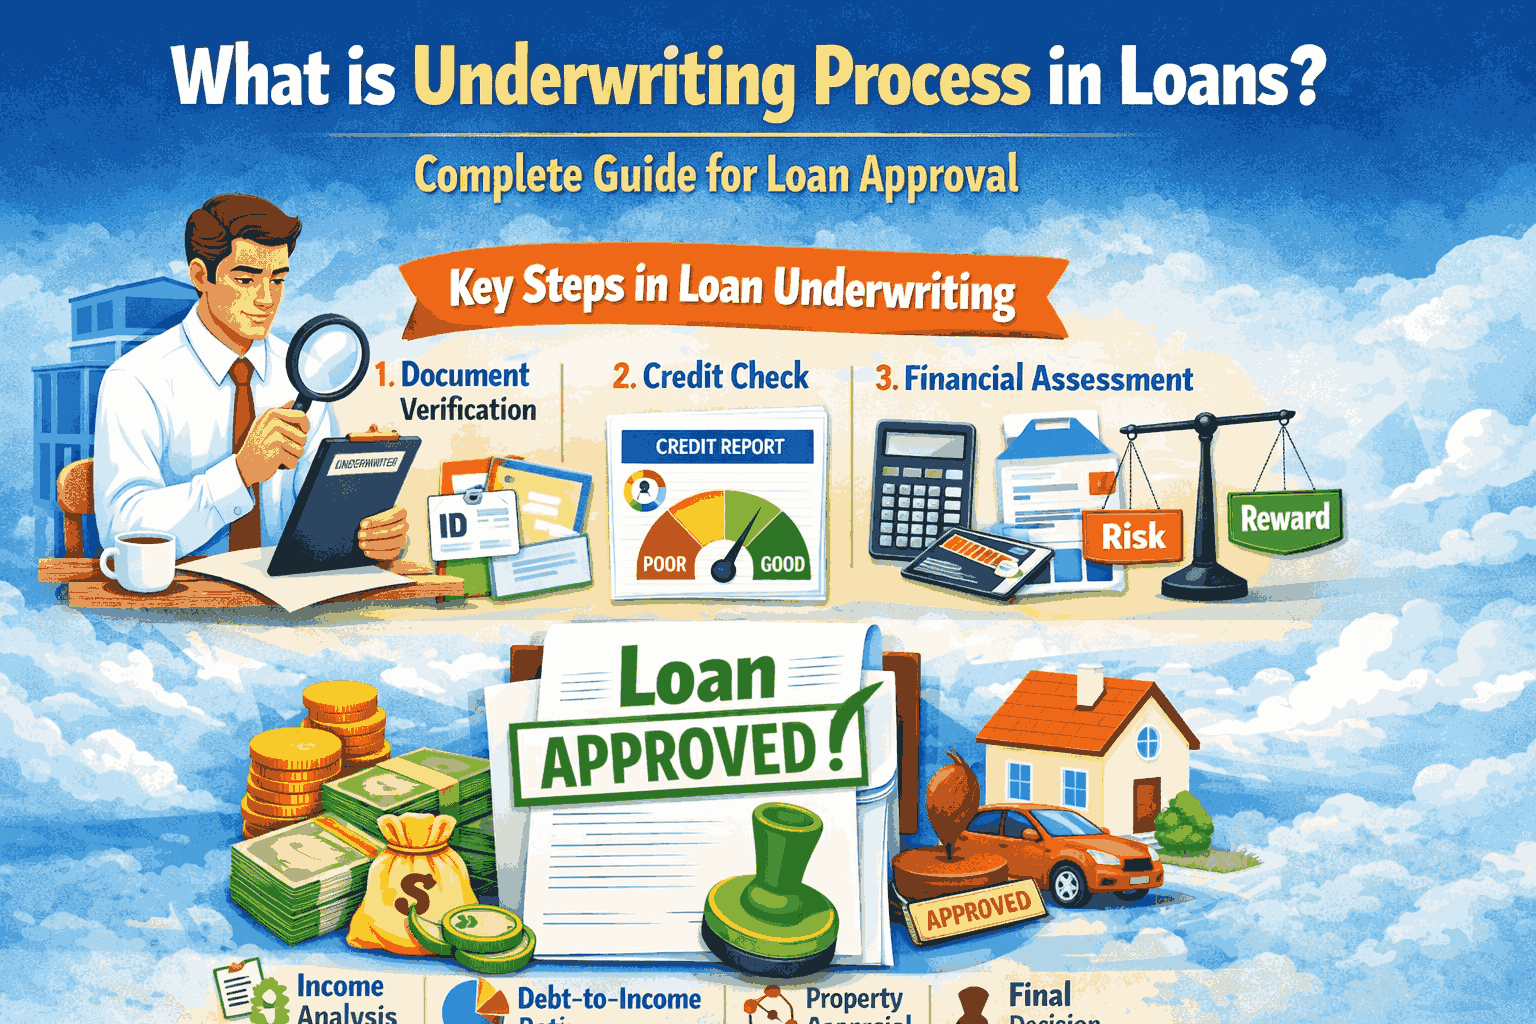
Once your application hits the desktop underwriter, they're looking at three buckets: capacity, collateral, and character. Capacity is whether the debt-to-income ratio holds up. Collateral is whether the property actually supports the loan amount. Character is whether your financial history tells a consistent story. The DTI calculation alone has more variations than most people realize. Front-end DTI looks at housing expenses divided by gross monthly income. Back-end DTI includes every recurring debt obligation. Some lenders will use the higher of the two ratios, which is why a low mortgage payment with high car loans can still get you rejected.
Here's what most guides don't tell you. The underwriter isn't evaluating your life. They're evaluating a spreadsheet that represents your life as of a specific date. Your income gets verified through W-2s and tax returns going back two years minimum. Self-employed borrowers need two full years of Schedule C or 1120S. If you changed jobs in the last sixty days, expect a letter of intent from your new employer or the file gets suspended. Lenders want to see stable employment history, not potential.
I dealt with a borrower last year who had a solid application going in. Eight hundred credit score, thirty-five percent down, twenty years at the same company. Underwriter pulled the file and found a single $47 charge on a credit card from two years ago that had gone to collections. Not even a large amount. The borrower had forgotten about it because it was old and irrelevant to their daily life. That forty-seven dollar charge delayed closing by eleven days while we tracked down the original creditor, negotiated a pay-for-delete, and got documentation that satisfied the automated underwriting system. A small detail that a human would probably overlook but Fannie Mae's guidelines don't care about.
The appraisal process during underwriting is another thing that catches people off guard. The appraiser isn't working for you or the lender specifically. They're working for the appraisal management company that the lender contracts through. This creates an indirect relationship where the appraiser has no incentive to advocate for either side. If the comp sales in the neighborhood are weak, the appraised value comes in low regardless of what you paid or what you think it's worth. When that happens, you can request a reconsideration of value with better comparable sales data, but the success rate on those requests is somewhere around fifteen to twenty percent depending on the market.
Cash reserves are one of those requirements that seems arbitrary until you understand the logic. Lenders want to see you have money left over after closing. Conventional loans typically require two to six months of mortgage payments in reserve. Seasonal workers or those with irregular income might need to show twelve months. The documentation path for reserves goes through bank statements, brokerage statements, or retirement accounts. You can't count funds that were deposited in the last sixty days without source documentation. A random $15,000 wire transfer from your brother showing up on your account five days before underwriting triggers a gift letter requirement and a full paper trail. That's called a large recent deposit and it's one of the most common reasons files get pulled out of the queue.
How to Prepare Your File Before It Hits the Underwriter
Don't do anything financial between approval and closing. I can't stress this enough. No new credit cards. No car payments. No co-signing anything for anyone. Any inquiry on your credit report after underwriting begins is a red flag. The automated systems pull a refreshed credit report and if they see a new hard inquiry, the file gets manually re-evaluated. That's an extra ten to fourteen days on your timeline.
Document everything early. Bank statements should be complete with no missing pages. If you're self-employed, have your tax returns and profit and loss statements organized in a digital folder before you even submit the application. I've had borrowers who spent three days in limbo because their CPA couldn't locate a year two tax return and the underwriting clock was already running. That delay cost them a rate lock extension that ran about eight hundred dollars.
Gift funds need proper documentation from day one. The donor needs to sign a gift letter stating the money isn't a loan. The money needs to show a clear paper trail from the donor's account to yours. If the donor is a relative, provide the relationship documentation. If it's from an employer or union, include that on official letterhead. Missing gift documentation is the number one reason for closing delays in assisted down payment situations.
There's a nuance with adjustable-rate mortgages that most borrowers miss. The underwriter needs to verify that you can afford the payment at the fully indexed rate, not just the teaser rate. So if you're getting a 5/1 ARM with a 3.5% initial rate and the fully indexed rate is 6.25%, your debt-to-income calculation uses 6.25%. This can change which loan products are actually viable for your situation. A fixed rate might come out cheaper after the qualification math even if the starting rate was higher.
Some loan programs have compensating factors that can offset weaker areas in your file. A higher credit score can sometimes compensate for a higher DTI. Significant cash reserves can make up for a short employment gap. Large documented assets outside the bank statements can sometimes offset a low reserve requirement. These aren't guarantees. They're manual overrides that the underwriter has discretion to apply. Understanding which levers exist gives you something to work with when your numbers are borderline.
Common Pitfalls That Kill Deals
Big purchases on credit before closing is the classic mistake. Someone needs a new refrigerator or they decide to buy furniture on credit. Even a couple thousand dollars in new installment debt can shift the DTI calculation enough to trigger a re-underwrite. The rule of thumb is don't spend anything you wouldn't normally spend. But the real rule is don't touch any new credit obligations at all.
Co-borrower complications come up more than you'd think. If you have a co-borrower on the application, their credit, income, and assets all get evaluated. Divorce proceedings, pending litigation, or even a bankruptcy filing by a co-borrower mid-processing can derail the entire application. Keep everyone in the deal informed and make sure nobody makes any financial moves without checking with the loan officer first.
Occupancy misrepresentation is a fraud indicator that lenders take extremely seriously. Saying you'll owner-occupy when you actually intend to rent it out or use it as a vacation property changes the entire risk profile. The penalties for misrepresentation include loan denial, reporting to fraud databases, and in extreme cases legal consequences. If there's any ambiguity about occupancy, disclose it upfront. The underwriter can work with uncertainty. They can't work with a lie.
Self-employment income is where a lot of file complexity concentrates. Lenders look at your net income after business expenses, not your gross revenue. Health insurance premiums, retirement contributions, and depreciation deductions all reduce your qualifying income. Some lenders add back certain non-cash expenses like depreciation, but the rules vary by program and by lender. Working with a loan officer who understands how different automated underwriting systems treat self-employment data can save you from picking a lender that will undervalue your income.
There's also the matter of state-specific requirements that most generic guides ignore. Some states have additional disclosure requirements, different escrow rules, or unique funding waiting periods. California has a three-day right of rescission on certain refinances that doesn't apply in Florida. Texas has additional notice requirements for certain loan types. If you're buying in a state you're not familiar with, ask your loan officer about state-specific timing implications before you assume the standard thirty-day close timeline will hold.
What to Expect During the Underwriting Timeline
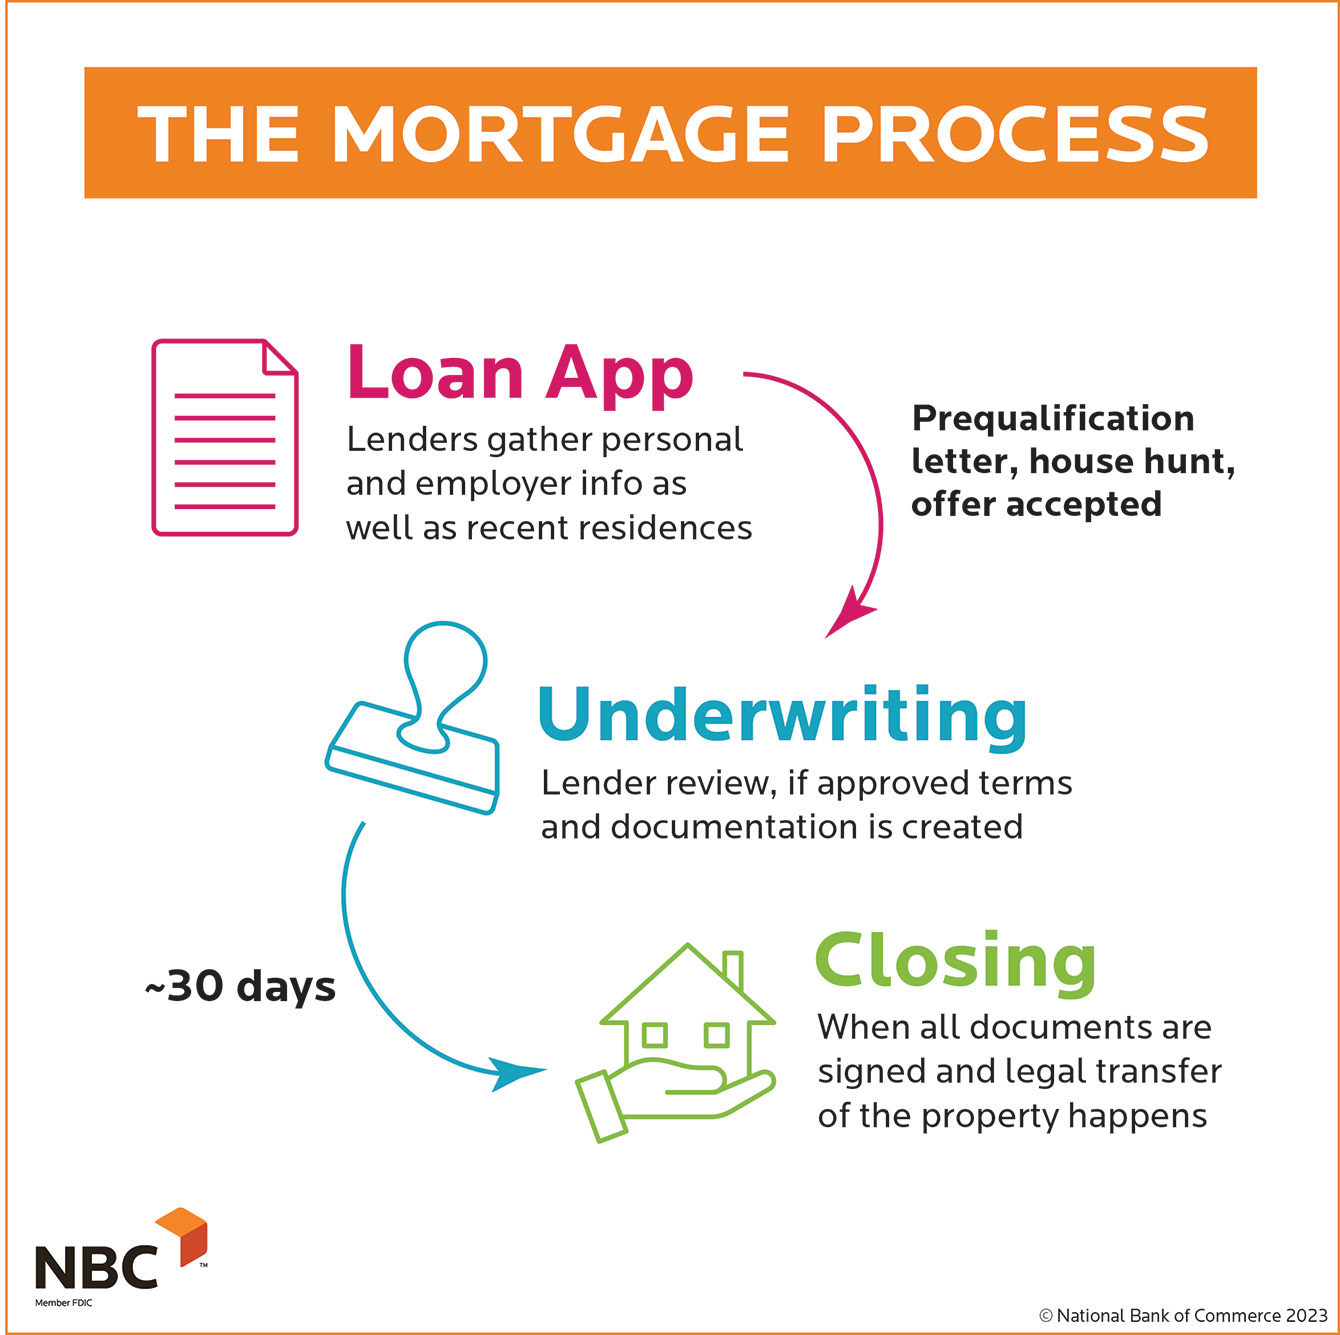
A typical conventional purchase goes through these phases: application and processing, appraisal and title order, underwriting review, conditions clearing, and closing. The processing phase usually takes five to ten business days. The underwriting review itself takes two to five business days if the file is clean. Condition clearing is where the variability lives. A straightforward file with no questions might clear in two days. A file with documentation requests or verifications can take two to four weeks.
I remember a file where the underwriter flagged a discrepancy between the borrower's listed employer on the application and the W-2 from two years prior. Same company name but a slight abbreviation difference. It turned out to be a data entry error on the W-2, not a job change. But resolving it required the borrower to contact their employer's payroll department, get a corrected form, and resubmit everything. That took four days and a good deal of frustration on both sides. Simple fixes often require simple but time-consuming verification steps.
Rate locks are another moving piece. Most locks are valid for thirty to sixty days. If underwriting drags and you're past your lock expiration, you'll need to extend the rate lock, which typically costs between zero point fifty and one point five points depending on market conditions and how long the extension is. Locking your rate as early as possible and understanding the extension policy before you commit is practical advice that most people don't follow until it's too late.
Underwriting guidelines themselves shift periodically. Fannie Mae and Freddie Mac update their eligibility criteria throughout the year. FHA guidelines change annually through their handbook updates. New programs get added and older ones get retired. The lender you worked with during pre-approval might have different program offerings or different overlay requirements by the time your file reaches the desk. Don't assume what worked in your pre-approval conversation will automatically apply to your full underwriting review.
Gallery Underwriting Home Loan
Home Loan Process: Steps to Getting a Mortgage
Loan Underwriting Process: FOIR, CIBIL & Approval
Mortgage Loan Underwriting in Australia: Explained in 2025
Understanding the Underwriting Process | Understanding loan contracts, Underwriting jokes ...
Loan Submitted to Underwriting: Understanding This Crucial Loan Stage - Unrealfi Mortgage