Mortgage underwriting isn't what most people think it is
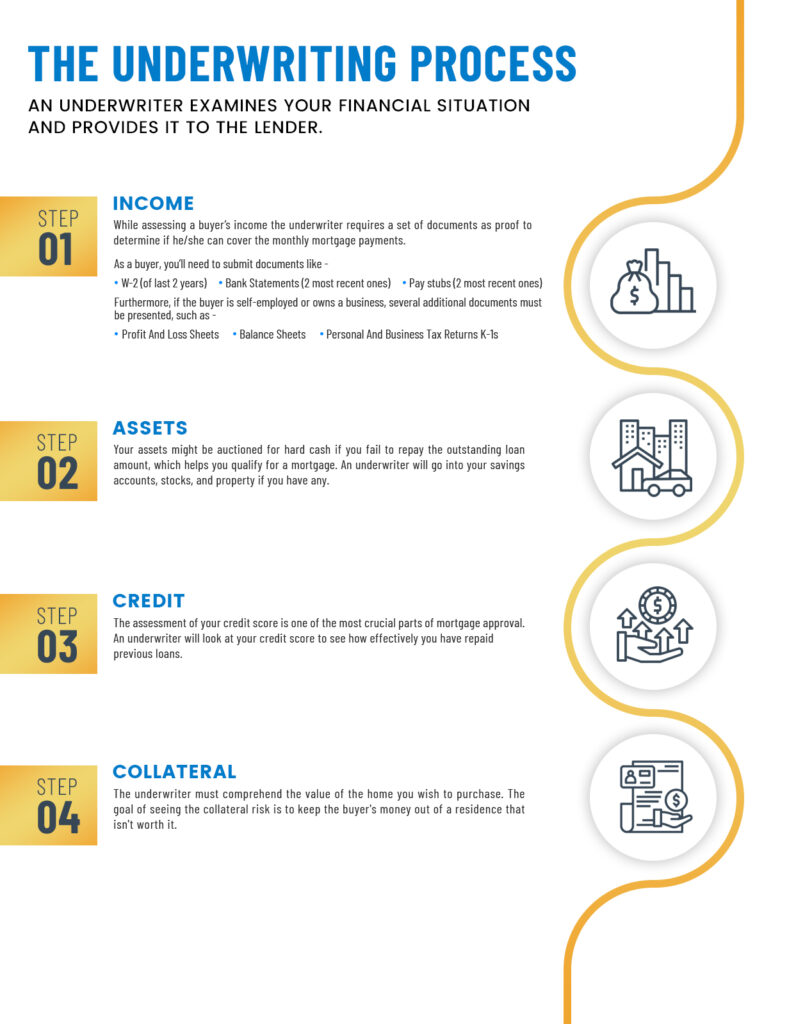
It's a series of checkbox decisions that feel arbitrary until you've done them a thousand times. The underwriting function at a mortgage company is where the risk gets separated from the revenue. That's it. Everything else is paperwork around that. I've been working in this space long enough to know that the systems change but the problems don't. Borrowers still submit incomplete documents. Loan officers still pull deals through hoping the processor catches their mistakes. And underwriters still sit in the middle deciding whether a file is fundable or a rehash.
How Underwriting Mortgage Companies Actually Operate
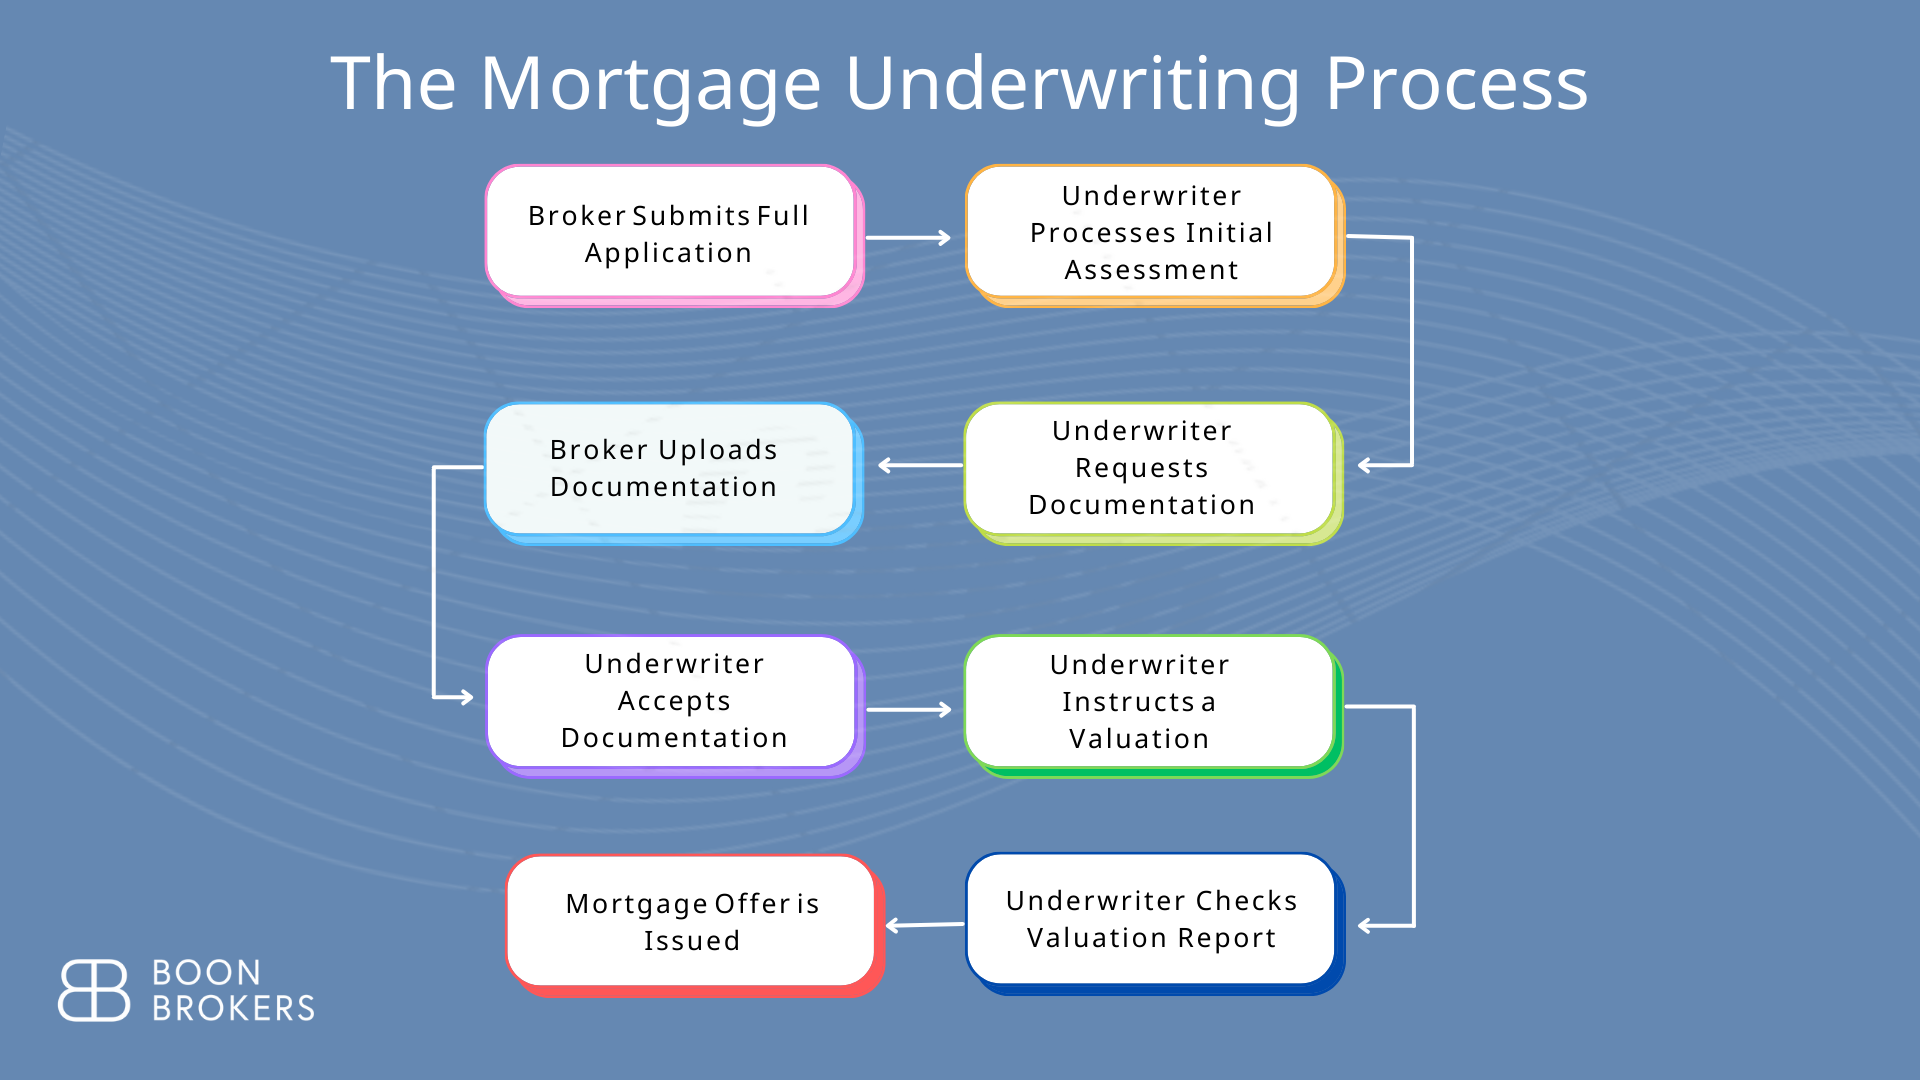
Start with the application intake. Most people think this is where the process begins. It's not. It begins with pricing and product selection, which happens before the application is ever formally submitted. The difference matters because if you price the loan wrong at the front end, the underwriter will fight you six weeks later when the rate lock is expiring and the appraisal comes in at 97 percent of the purchase price. The core workflow runs through three stages: ordering and reviewing conditions, evaluating the full document package, and issuing either a clear to close or a suspension. Each stage has its own set of decision points that separate a good underwriter from a competent one. Document review is where most files either get cleaned up or get stuck. I'm talking about the automated verifications — IVs — for income, employment, assets, and the credit profile. The automation handles the easy cases. What it doesn't handle well is self-employed income with K-1s that show losses in one year and profits in another, or a borrower who switched from W-2 to 1099 mid-year because their side business finally took off. That file went to manual underwriting last month. I spent four hours reconciling bank statements against the tax transcripts. The workaround was simple: we pulled the prior two years of returns, averaged the adjusted gross income from line 12 on Schedule 1, and used the higher of the two years for qualification. Standard practice, but the automated systems would have flagged that file immediately and sent it into a manual queue anyway.
Decision matrices and what they actually mean
Underwriting guidelines aren't suggestions. They're binary. A borrower either qualifies or doesn't. The nuance comes in how you interpret the gaps between the rules. Debt-to-income ratio is the classic example. Everyone knows the 43 percent threshold for conventional loans and the 50 percent plus guideline for FHA. What people don't always understand is how residual income factor changes the equation for certain loan types, especially in higher-cost areas where housing expenses eat into what looks like a comfortable DTI on paper. Asset depletion is another area where beginners trip up. A borrower shows two million dollars in liquid assets but the income doesn't support the payment. Some underwriters will accept this as a qualifying path. Others will push back harder. The right call depends on the investor selling guide and the specific loan product. Know your seller before you make that call. Appraisal reviews are where you see the most variation in judgment. A value opinion of 95 percent of contract price with minimal repairs might be fundable in one portfolio and a re-underwrite in another. The difference usually comes down to whether the property has any physical defects that suggest the market comps are stretched or whether it's just a thin appraisal in a thin market. Those look identical on the surface.
Get the Full Details
Occupancy classification causes more problems than it should. Owner-occupied versus investment isn't just a rate difference. It changes the insurance requirements, the reserve expectations, and the severity of underwriting scrutiny. I've seen files flipped from owner-occupied to investment after the appraisal report described the property as currently tenant-occupied with a lease on file. One sentence in the agent's notes changed the entire risk profile of the deal.
Common pitfalls in the underwriting pipeline
The biggest waste of time I see repeatedly is poor file preparation before it reaches the underwriter. Loan officers and processors have their own checklists, and those checklists are usually incomplete. What ends up missing is always something different — a signed explanation letter for a deposit, a voided check that doesn't match the account being used, a credit score update from a lender pulled during rate shopping that the automated system never refreshed. Automated underwriting systems like Fannie Mae's Desktop Underwriter or Freddie Mac's Loan Product Advisor are helpful but they're only as good as the data you feed them. Garbage in, garbage out isn't a catchy phrase here. It's the daily reality. I once had a file where the automated system returned a find acceptable because the employment history showed continuous five-year employment. The fine print in the verification section revealed that two of those five years were at the same employer but the address and phone number had changed, indicating a possible subsidiary or reorganization that the system couldn't parse. Manual review caught it. The borrower actually had a gap. Three months. That three-month gap changed the income calculation from stable to variable, which changed the qualifying ratio enough that the deal fell apart under manual guidelines even though the automated system approved it cleanly. Another thing nobody talks about enough is the rate lock expiration cascade. You lock a rate at day 20 of a 30-day process. Everything looks fine. Then the appraisal comes back with a repair request, the repairs happen, the re-inspection happens, the title search finds a mechanic's lien from a renovation that closed three months ago, and suddenly your lock expires on a file that isn't clear to close. You're now either paying an extension fee or re-pricing at a higher rate. The extension fee is usually one-twentieth of a point per week. That adds up fast when the underwriter is sitting on a file because someone forgot to order the flood certification in the first week.
Workflow optimization that actually moves the needle
Condition management is the single highest-leverage activity in the underwriting process. If you're issuing conditions in batches instead of sequentially, you're losing days. Sequential condition resolution means the borrower responds to one request at a time, and each response gets reviewed before the next request goes out. Batch conditioning means you dump ten requirements on the borrower at once and wait for everything to come back. The second approach sounds faster but it usually takes longer because the borrower can't prioritize, they respond to what's easiest, and then you're cycling back and forth for weeks. Pre-underwriting is becoming standard practice at larger companies. The concept is straightforward: before the file ever hits formal underwriting, a underwriter or quality control person reviews the complete package and flags issues early. This typically cuts the average processing time by about three to five business days on a standard 30-day closing pipeline. The cost is that you're using a higher-paid person earlier in the process instead of reserving that cost for the final decision stage. The math works if you're losing deals to slow turnarounds or doing re-underwrites because conditions changed after funding. Technology adoption varies wildly between companies. Some mortgage companies still run everything through email and spreadsheets. Others have integrated platforms where the LOS feeds directly into the underwriting workflow engine. The integrated approach reduces handoff errors and makes audit trails cleaner. It also means the underwriter sees real-time updates from the processing side instead of chasing down what happened to that uploaded document from Tuesday.
What the regulations actually require
Moral obligation to the borrower means you can't approve a file you know has a material defect. This isn't just ethical guidance. It's enforceable under Regulation Z and the ability-to-repay rules. If you're underwriting a loan and you know the income documentation is unreliable, approving it creates liability that extends far beyond the closing table. The recourse provisions in modern servicing agreements mean that a single bad file can cost the company significant money if it gets flagged in quality control review later. Equal credit opportunity law applies to every decision point in the underwriting process. This means the criteria you use must be consistently applied across all applicants regardless of protected characteristics. The problem isn't intentional discrimination. It's inconsistent application of guidelines. One borrower gets a waiver for a deposit explanation because they told a sympathetic story. Another borrower in the exact same situation gets rejected because their explanation didn't land well. That inconsistency is a compliance risk. Serve requirements have gotten stricter over the past decade. The documentation standards for what constitutes acceptable verification have tightened, and the audit expectations from investors have increased. Files that would have been approved cleanly in 2018 might get additional conditions today. This isn't because underwriters are being harder. It's because the guidelines changed and the audit exposure changed with them.
When manual underwriting is unavoidable
Non-QM loans still require underwriters who understand the nuances of alternative income documentation. Self-employed borrowers, interest-only products, and non-traditional credit profiles all fall outside the automated system comfort zone. The manual underwriting process for these files typically takes two to three times longer than an automated approval, and that's without complications. Credit re-establishment cases are another area where automation falls short. A borrower with a foreclosure three years ago who has rebuilt credit since then presents a profile that the automated systems often mischaracterize. The system sees the foreclosure and outputs a decline. The manual underwriter sees the pattern of on-time payments post-foreclosure, the reduced balance on revolving accounts, and the stable employment history, and makes a different call. The investor guidelines matter enormously here. Some portfolios are more forgiving than others. Property-related issues that affect value require manual intervention. A kitchen renovation that wasn't permitted, a finished basement that doesn't meet local code, a pool that was installed without inspection — these create valuation risk that automated systems can't assess. The underwriter has to decide whether to accept the appraiser's opinion, request additional documentation, or condition the approval on verification. Each decision has downstream consequences for the investor and the borrower.
The reality of scaling underwriting operations
Volume-based underwriting companies use scoring models and exception matrices to standardize decisions. This works well for homogeneous loan types and consistent borrower profiles. It breaks down when the product mix diversifies or when the borrower population becomes more varied. A model built on conventional conforming loans doesn't translate well to jumbo or non-QM products without significant recalibration. Training underwriters requires a mix of classroom instruction and supervised file review. The supervised review phase is where most people learn the actual job. Reading guidelines is one thing. Applying them to a file with seventeen document types, conflicting information between the application and the credit report, and an appraisal that seems slightly off is another. The training period for a new underwriter typically runs six to twelve months depending on the complexity of the product line and the quality of the mentoring program. Burnout is real in this role. The combination of high volume, tight turnaround expectations, and constant compliance pressure creates a stressful environment. Companies that treat underwriting as a transactional function rather than a risk management function tend to have higher turnover. The cost of replacing a productive underwriter who understands the product lineup and the investor guidelines can range from fifteen to twenty-five thousand dollars when you factor in recruiting, training, and lost productivity during the ramp-up period.
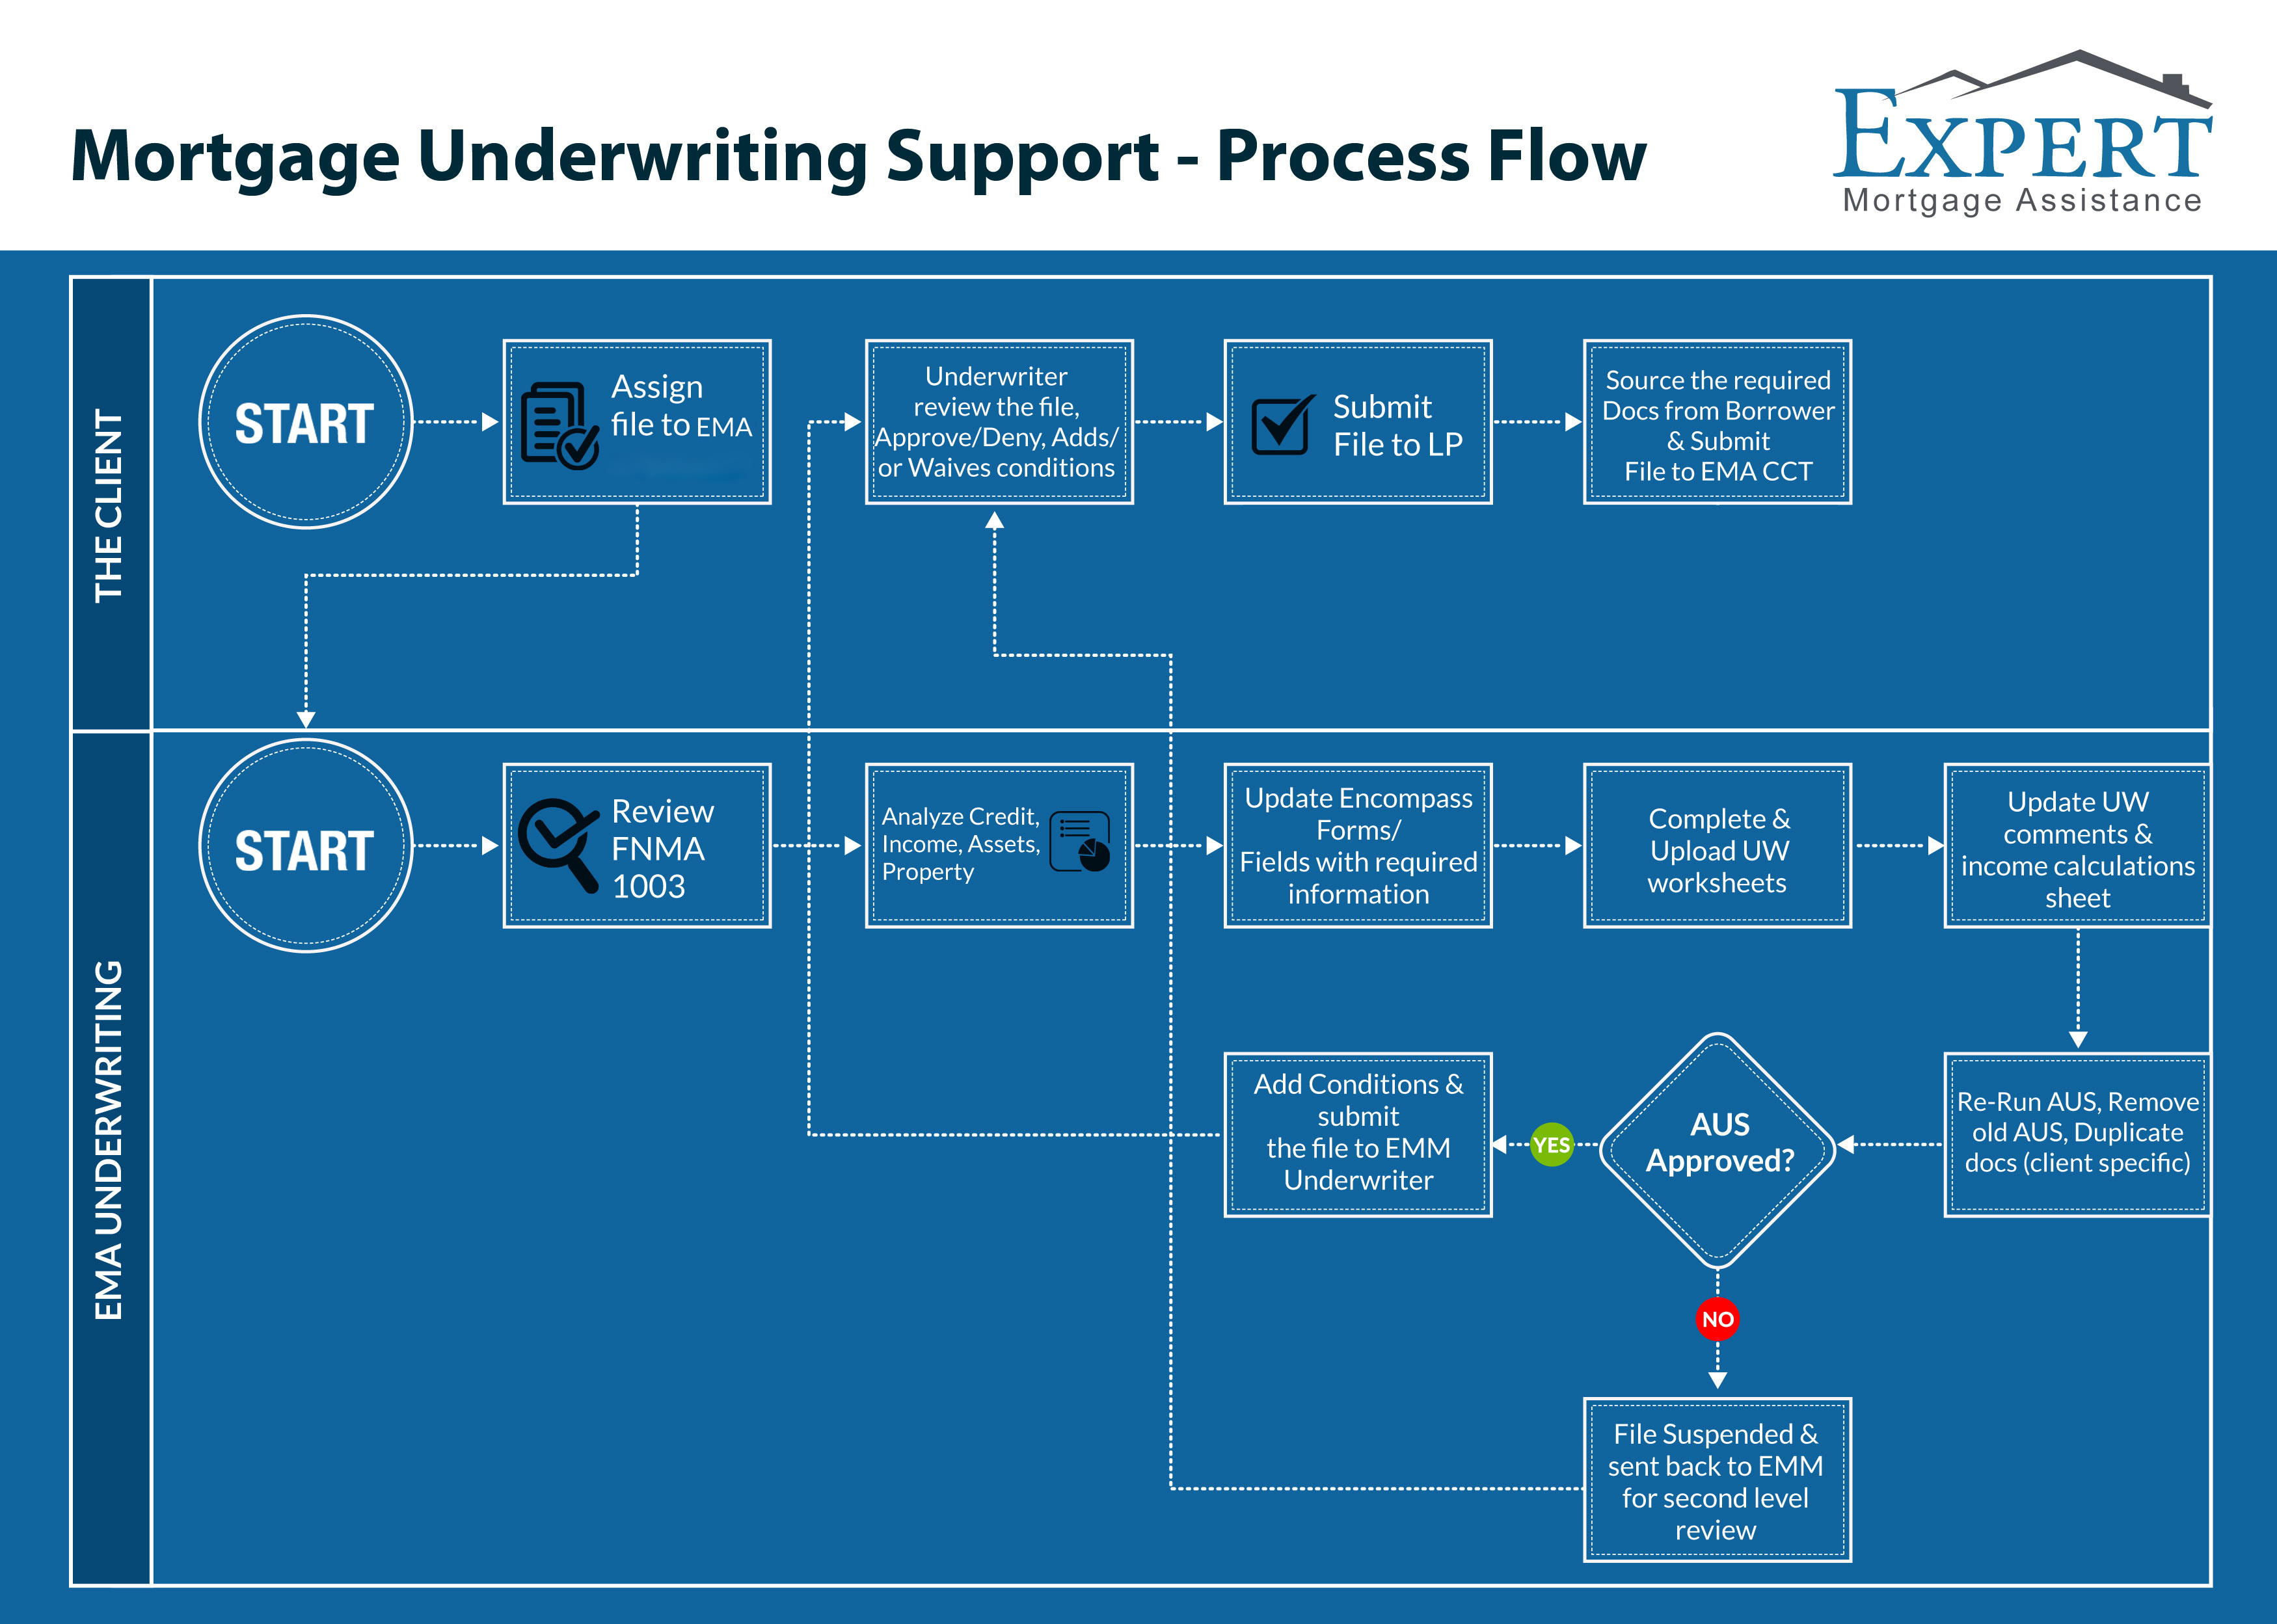
The regulatory landscape keeps shifting. Change management is a constant task for any organization running an underwriting operation. New guidelines from Fannie, Freddie, FHA, VA, and USDA get published regularly. The ones that matter most for your product mix need to be incorporated into your policies and procedures, your training materials, and your systems configurations. This isn't a quarterly task. It's continuous. Technology that helps but doesn't solve everything includes document parsing tools, automated credit report refreshers, and electronic verification platforms. These tools reduce manual data entry and speed up the verification steps. They don't make the judgment calls. The underwriter still has to read the parsed output, spot the discrepancies, and decide how to resolve them. The value of these tools is in reducing the administrative burden so the underwriter can focus on the actual decisions. Quality control reviews should catch errors before they reach the investor. Most companies do this through a combination of pre-funding and post-funding reviews. Pre-funding reviews on a sample of files typically run at two to five percent of production volume depending on the company's risk tolerance and regulatory requirements. Post-funding reviews catch issues that slipped through and inform improvements to the process. The best companies use both data sources together to identify patterns in errors and fix systemic issues rather than just blaming individual underwriters.
Profitability in mortgage underwriting comes from getting the file right the first time and getting it to closing fast enough to beat the competition on rate and service. Speed without accuracy creates recourse risk. Accuracy without speed loses business. The balance point is different for every company depending on their cost structure, their investor relationships, and their volume targets. There's no universal optimum. You find it by tracking your actual metrics over time and adjusting your process accordingly.