Understanding the Unit Personal Financial Literacy Homework 1 Answer Key
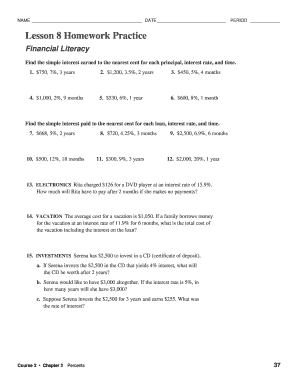
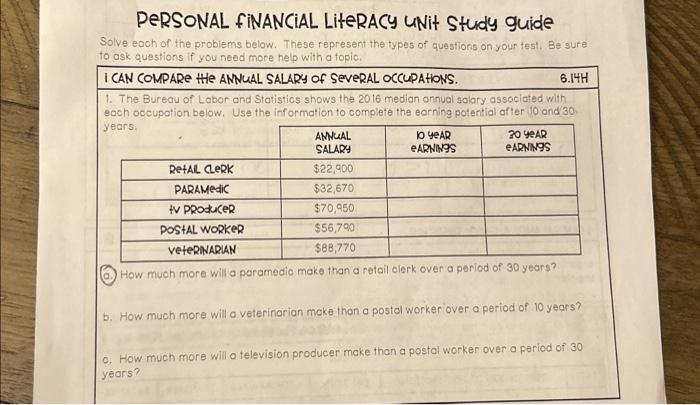
The answer key for Unit Personal Financial Literacy Homework 1 is essentially a reference document that shows the correct responses to a standard introductory personal finance curriculum. These units typically cover budgeting, income types, the difference between needs and wants, basic banking concepts, and the relationship between spending and saving. When students complete this unit, they are expected to demonstrate understanding through worksheets, multiple-choice questions, and sometimes short calculations involving simple percentages or ratios. I have helped several teachers and tutors review these materials over the years. The homework itself usually asks students to categorize expenses, compute gross versus net pay given a stated tax rate, fill in a mock checking account ledger, and identify appropriate financial decisions in short scenarios. The answer key provides the expected numerical results and the reasoning behind multiple-choice selections.
Where to Find the Unit Personal Financial Literacy Homework 1 Answer Key
These keys circulate primarily through educational resource platforms and teacher-sharing sites. Common sources include curriculum publishers, state education department repositories, and shared drives used by finance courses. Because many programs distribute their materials through subscription platforms like Edgenuity, Odysseyware, or similar LMS environments, the key may be embedded within the course itself rather than floating around as a standalone document. Always verify that any version you use matches your specific textbook edition or program, since different publishers phrase questions differently even when the underlying concept is identical. A standard Homework 1 assignment breaks down into three sections. The first section covers vocabulary and concept identification. Students encounter terms like fixed income, variable expenses, gross pay, net pay, direct deposit, and compound interest. They match definitions or select the correct term from a list. The second section moves into numerical problems. These involve calculating take-home pay from a given hourly wage and tax percentage, filling out a simple budget table, or determining remaining balance after a series of deposits and withdrawals. The third section presents scenario-based questions asking students to choose the most financially responsible action in a given situation, such as whether to use a savings account versus keeping cash at home, or how to handle an unexpected expense. The answer key reflects this structure directly. For vocabulary items, it lists the matched term alongside the correct definition letter or number. For calculations, it shows the final computed value along with the intermediate step so graders can see partial credit logic. For scenario questions, it provides the selected choice plus a brief justification statement that explains why that choice aligns with sound financial behavior.
Working Through the Problems Step by Step
Let me walk through the calculation portion since that is where most students lose points. If the homework asks you to determine net pay from a gross hourly wage, the process follows a clear sequence. Start with gross earnings. Multiply hourly rate by hours worked to get total gross pay. Then apply the tax deduction. If the problem states a flat tax rate, multiply gross pay by that rate to find the withholding amount. Subtract the withholding from gross pay to reach net pay. Keep all decimal places during intermediate steps and round only at the end to avoid cumulative rounding errors that throw off the final answer. Budget table problems work similarly. List each income source at the top. List each expense category below. Subtract total expenses from total income. A positive result means the budget balances with surplus money going to savings or debt repayment. A negative result signals that spending exceeds income, which requires either reducing discretionary expenses or adjusting the scenario assumptions. I encountered a specific issue recently while reviewing a student's work on a variation of this unit. The problem asked students to calculate monthly net pay from an annual salary of forty-eight thousand dollars with a twelve percent tax rate, assuming equal monthly distribution. The student divided the annual salary by twelve first, getting four thousand, then calculated twelve percent of four thousand and subtracted it, arriving at three thousand five hundred twenty. That answer was mathematically correct. However, the answer key expected the student to calculate total annual tax first, then divide the net annual amount by twelve. Both methods produce the same final number, but the key's intermediate values differed. I flagged this for the instructor because it revealed a gap in how the answer key handled alternative correct solution paths. The workaround was straightforward: I provided both sets of intermediate calculations alongside the final answer so the grader could award full credit regardless of approach.
Get the Full Details

Common Pitfalls to Watch For
Students consistently make the same errors on this assignment. Rounding too early is the biggest one. If a tax calculation produces a repeating decimal and the student rounds immediately instead of carrying the full value forward, the final net pay can shift by a dollar or more. Another frequent mistake involves confusing gross and net in budget scenarios. Some students plug the pre-tax income into expense categories as if it were the actual amount available for spending, which inflates the apparent budget by the tax withholding amount. Scenario questions also trip people up because the correct answer is not always the emotionally appealing choice. A question might present a tempting short-term option that costs more over time, and students pick it based on immediate relief rather than long-term financial logic. The answer key typically flags these pitfalls through its justification statements. When you compare your reasoning against the key's explanation, you can identify whether your error was computational or conceptual. Computational errors show up as wrong numbers but right logic. Conceptual errors show up as right numbers with flawed reasoning, which is actually worse because it means you got lucky on the calculation but did not understand the underlying principle.
Using the Answer Key Effectively
The key is most useful when treated as a diagnostic tool rather than a shortcut. Complete every problem on your own first. Then open the key and compare. For calculation questions, verify not just the final number but whether your method matches the expected approach. If your answer matches but your path differs, figure out whether your method is still valid or whether you happened to arrive at the right number through flawed logic. For scenario questions, read the key's justification carefully. Even if you selected the same option, your reasoning might be incomplete. A strong personal finance answer should reference opportunity cost, long-term impact, or risk management, depending on the question type. If you are a teacher grading these assignments, the answer key saves roughly twenty to thirty minutes per batch compared to working through each problem from scratch, assuming your class is using the standard version of the unit. It also ensures consistency across multiple graders or teaching assistants. However, the key has real limitations. It does not account for locally customized questions that some instructors add, such as region-specific tax rates or modified budget scenarios. When custom questions appear, the published key will not cover them, and you need to generate answers manually using the same formulas the original problems rely on. Additionally, answer keys from unofficial sources sometimes contain transcription errors, particularly in the numerical answers. Cross-check any key you download against at least two separate sources before relying on it for grading or self-study.
When the Answer Key Falls Short
There are situations where this particular unit's answer key is insufficient. If your course emphasizes financial spreadsheet modeling or calculator-based compounding exercises, the standard key will not provide step-by-step spreadsheet formulas or detailed compound interest derivation. In those cases, you need a more advanced resource or direct instructor guidance. Similarly, if the homework includes open-ended reflection questions asking students to analyze their own spending habits, there is no single correct answer, and the key can only offer a sample response framework rather than a definitive answer. I recommend supplementing the key with the textbook's chapter summaries and any teacher-created rubrics for partial credit on scenario explanations.