What actually happens when you submit University Financial Aid forms
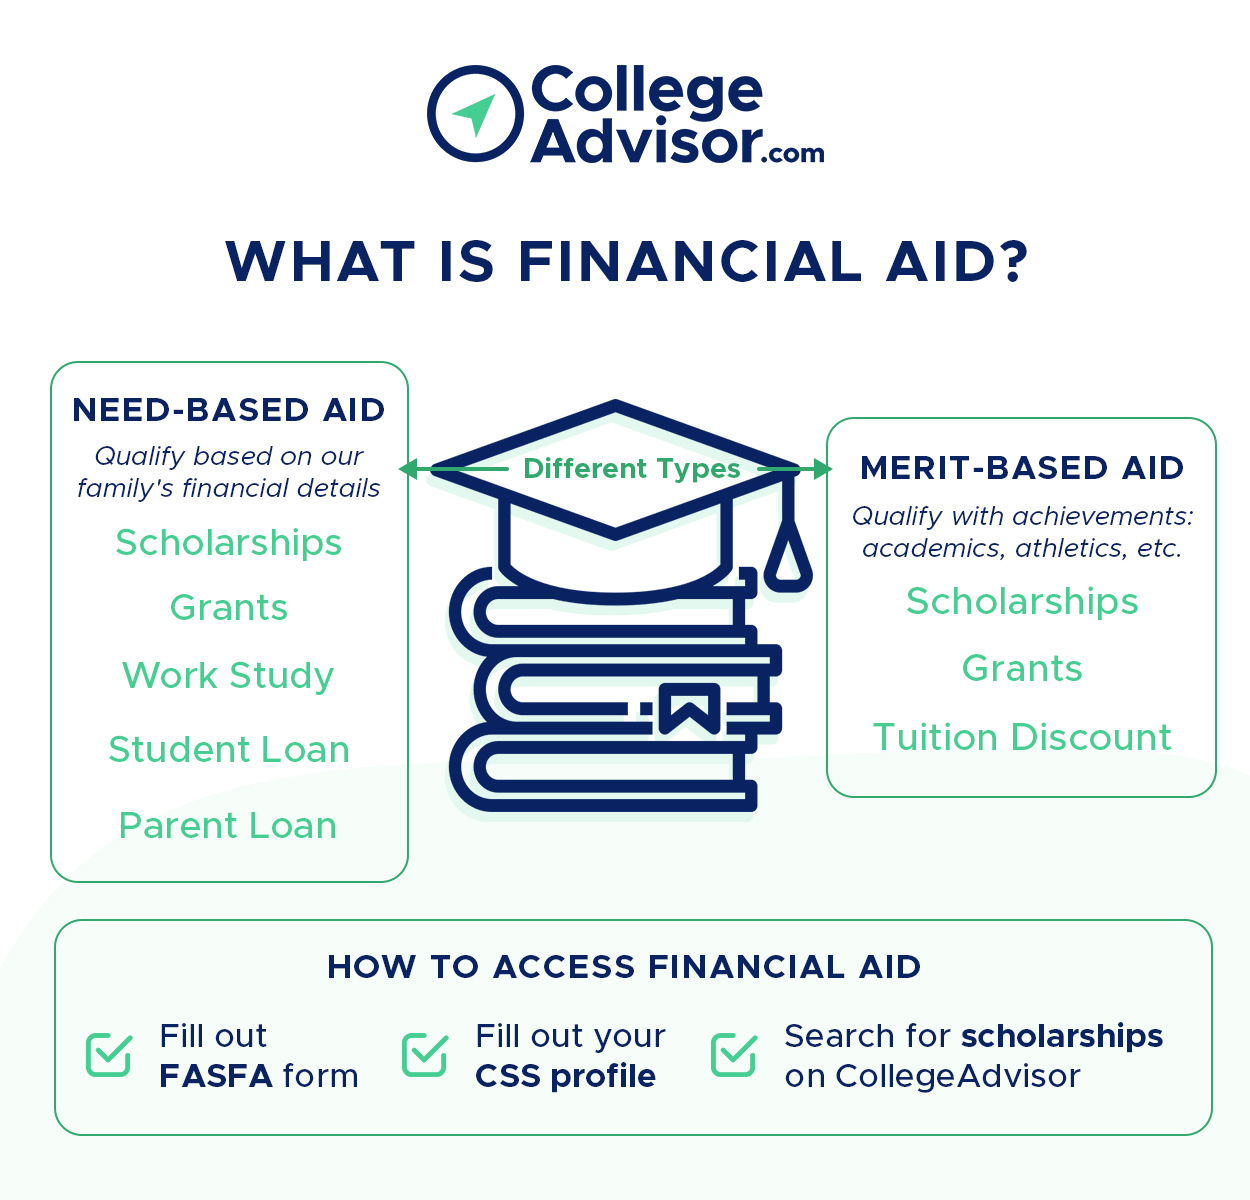
The Free Application for Federal Student Aid opens on October 1 every year, but that date alone won't save you anything. Most students I've worked with think submitting early means they'll get money sooner. That's not how it works. Colleges receive your FAFSA data on a rolling basis, and many award packaging cycles don't even begin until February or March because they're still waiting for tax transcripts from hundreds of families. If you submit in October but don't follow up with your required documents, your application sits in a verification queue while students who submitted in January and handed everything in on day one get their letters first. I dealt with a student once whose family had a significant capital gain from selling a rental property in the tax year used on their FAFSA. The CSS Profile needed at her target school required a detailed explanation of that income, and her original submission just listed the number with no context. The financial aid office sent her back to verify three separate times because the explanation was missing. We eventually attached a signed letter from her accountant along with Schedule D from their tax return, which finally cleared it. That delay cost her the priority merit scholarship deadline by six weeks.
Navigating University Financial Aid verification without losing your mind
Verification is the single most common bottleneck in the entire process. The Department of Education randomly selects about a third of all FAFSA submissions for verification, and some states and individual colleges apply their own mandatory verification rules on top of that. When you get flagged, you're usually asked for a verification worksheet, a tax transcript, and a list of household members in college. The transcript part trips people up repeatedly. They order an iron-copy transcript from the IRS and wait five to seven business days. You can use the IRS Data Retrieval Tool instead, which pulls the data directly into your FAFSA in minutes and eliminates that entire document request cycle. If your parents are divorced or separated and the tool won't work for your custodial situation, you'll need the actual transcript anyway. There's no shortcut there. One detail most guides miss: the FAFSA verifier field. If you're a dependent student whose parents refuse to fill out their portion of the form, you can request a dependency override from your financial aid office. I've seen three successful cases where a parent was incarcerated, and two where there was documented abuse with a police report or counselor statement. The bar is genuinely high. A parent who simply refuses to provide information usually doesn't qualify. The process takes about two weeks once you submit the paperwork, but if you're denied the override, you become eligible for unsubsidized loans only, not grants or subsidized loans. That distinction matters enormously for total cost.
How the actual award package gets built
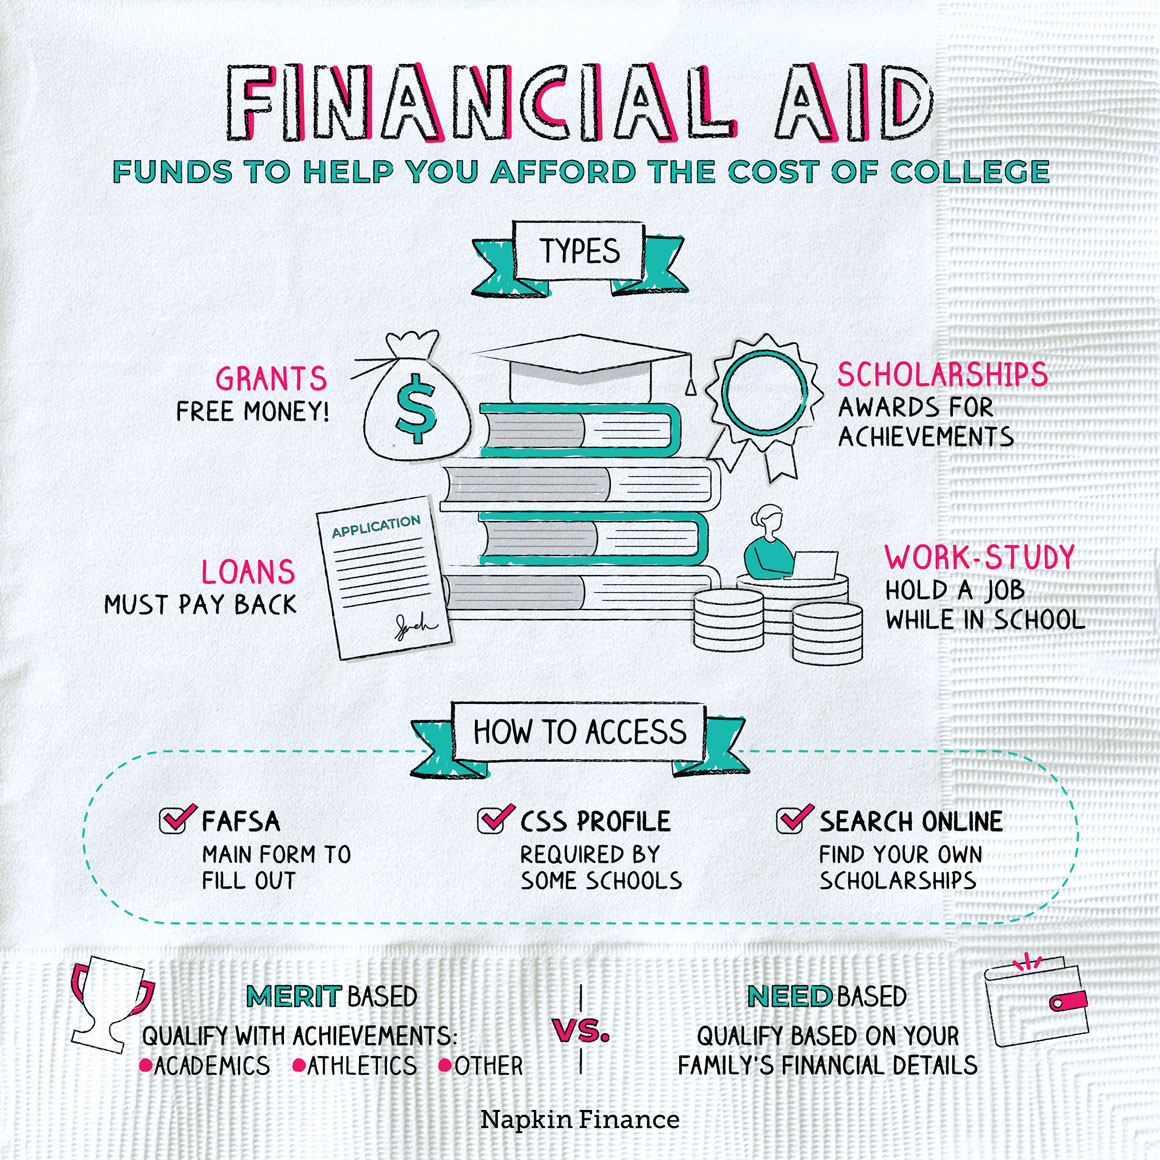
Your Expected Family Contribution used to be the number everyone obsessed over. It's been replaced by the Student Aid Index since the 2024-25 award year, but the mechanics are essentially the same. The formula looks at parental income and assets, student income and assets, family size, and the number of family members enrolled in college at least half-time. The last factor is the most misunderstood part. If two siblings are both in college simultaneously, the EFC or SAI gets divided across both applications, which usually lowers each student's calculated contribution and increases grant eligibility at need-aware schools. I've seen this exact scenario add $8,000 to a younger sibling's grant package because the older sibling was already enrolled when the FAFSA was filed. The award letter you receive is not a single offer. It's a packaging decision that typically combines federal Pell grants, state grants, institutional need-based grants, federal Direct Subsidized Loans, federal Direct Unsubsidized Loans, and sometimes a work-study allocation. The loan portions are mandatory if you qualify, but the grant and work-study portions are not guaranteed. Here's the counter-intuitive part that nobody warns you about: schools often prioritize filling your grant gap with institutional money first, then layer in federal loans, then work-study. That means two students with identical SAI numbers at the same university can receive different award packages if one applied early through early action or early decision and the other applied through regular decision. Institutional grant pools have finite budgets, and they distribute those dollars based on arrival order of complete applications, not just on calculated need. Another thing people miss is the role of professional judgment. If your family's financial situation has changed significantly since the base tax year—job loss, medical expenses exceeding the standard deduction threshold, a divorce finalized after the tax year closed—you can request a professional judgment review. The financial aid office has the authority to adjust your income or asset figures on a case-by-case basis. This is not something you do online. You need to submit a formal letter explaining the change, supporting documentation like termination letters or medical bills, and you usually need to request this review before the school's priority packaging deadline. I handled one case where a single mother's hours were cut from forty to twenty per week during the tax year, and after the review, her SAI dropped by nearly two thousand dollars, which unlocked an additional state grant she wouldn't have qualified for otherwise. The process took about ten business days from submission to decision.
Get the Full Details
Common mistakes that quietly reduce your aid
Students frequently list their summer earnings on the FAFSA as current-year income when they should be listing prior-prior year tax data. The FAFSA asks for income from two years before the award year, which is intentional. That design choice exists so families don't have to wait for the current tax year to finish before filing. Using the wrong income year creates a mismatch that triggers verification flags and delays your package by three to four weeks. Check that you're reporting the correct tax year before you submit anything. Another mistake is not understanding the difference between cost of attendance and what you actually pay. Your COA includes tuition, fees, room, board, books, supplies, transportation, and a personal allowance. The financial aid office uses this number to calculate your demonstrated need by subtracting your SAI from the COA. But the COA is an estimate, not a bill. If your actual rent is lower than the housing component of the COA, you don't get the difference refunded as extra aid. Conversely, if your books and transportation costs exceed the allowance built into the COA, you can potentially request a readjustment of your cost of attendance, which would increase your total aid eligibility. This is rarely done, but it's available and it's worth filing if your expenses genuinely exceed the standard estimate. There's also the issue of outside scholarships. If you receive a private scholarship that isn't reported to the financial aid office, they can reduce your institutional grant portion dollar for dollar. Some schools will replace grant money with loan money instead, which technically keeps your total aid package the same value but shifts you from free money to borrowed money. The best approach is to report every scholarship you receive and ask the office how they apply the reduction. A quarter of students I've spoken to discovered after the fact that their unreported scholarship had reduced their grant by exactly the amount they received, leaving them with zero net benefit from the award.
Where the system actually fails you
The FAFSA itself has structural limitations that no amount of preparation can fully overcome. The income formula treats home equity as an asset, which penalizes families who own modest homes in expensive markets. There is no exclusion for retirement accounts on the FAFSA, but there also isn't a special handling advantage for them, so the calculation doesn't meaningfully reward saving for retirement through 401(k)s or IRAs. If your family has significant retirement savings but low liquid assets, your calculated contribution may be higher than your actual ability to pay because the formula doesn't capture that nuance. The CSS Profile has similar blind spots. It asks for medical expense deductions that require you to itemize on your tax return, which most families don't do. If your medical expenses are substantial but you take the standard deduction, you simply cannot claim that adjustment on the CSS Profile. I've seen this deny families thousands in additional need-based aid because the form's design assumes itemized deductions, and the online submission process has no workaround field for medical expenses reported elsewhere. State aid programs vary wildly in their deadlines and requirements. Some states use the FAFSA as their sole application and have deadlines as late as June for the following academic year. Others have separate state applications with October or November deadlines and don't accept the FAFSA at all. California's CADAA, for example, serves undocumented students who are ineligible for the FAFSA but want state grant money. If you're in a state with a separate application, missing that deadline costs you state-level grant money that has nothing to do with the federal process. Check your state's higher education website directly rather than relying on general guidance.
What to do if you hit a wall
When your award letter doesn't cover your estimated costs, you have two options beyond applying for more loans. You can request a professional judgment review if your circumstances have materially changed, as I mentioned earlier. Or you can appeal for a packaging reconsideration by presenting new information the office didn't have when they built your original package. This second route is different from professional judgment because it doesn't involve changing your financial data—it involves showing the office something they overlooked, like a scholarship you missed reporting or a special expense they didn't account for in your cost of attendance calculation. The appeals process at most institutions is informal and email-based. You write to the financial aid office, explain what's missing, attach documentation, and ask for a review. Response times vary from five business days to three weeks depending on the office's workload. I've never seen an appeal denied outright when the documentation was legitimate and the request was reasonable. What does happen more often is a delayed response and a packet of additional questions before any adjustment is made. Plan for a two-to-three-week turnaround on any appeal. If you're an international student or an undocumented student ineligible for federal aid, the FAFSA and most state programs are not available to you. Your options narrow to institutional aid, private scholarships, and in some cases, state-level programs that don't require citizenship. The CSS Profile is still usable for institutional aid at most private universities, and some schools have their own non-federal need analysis forms for students who can't complete the FAFSA. Contact the financial aid office directly and ask about alternatives to the FAFSA before you submit anything.

The bottom line is that University Financial Aid is not a single process. It's a series of overlapping systems—federal, state, and institutional—each with its own deadlines, rules, and failure modes. The people who navigate it successfully are the ones who treat the FAFSA as the starting point, not the end point, and who follow up on everything they submit. The system rewards attention to detail and punishes assumptions.