How the FAFSA and institutional deadline process actually works
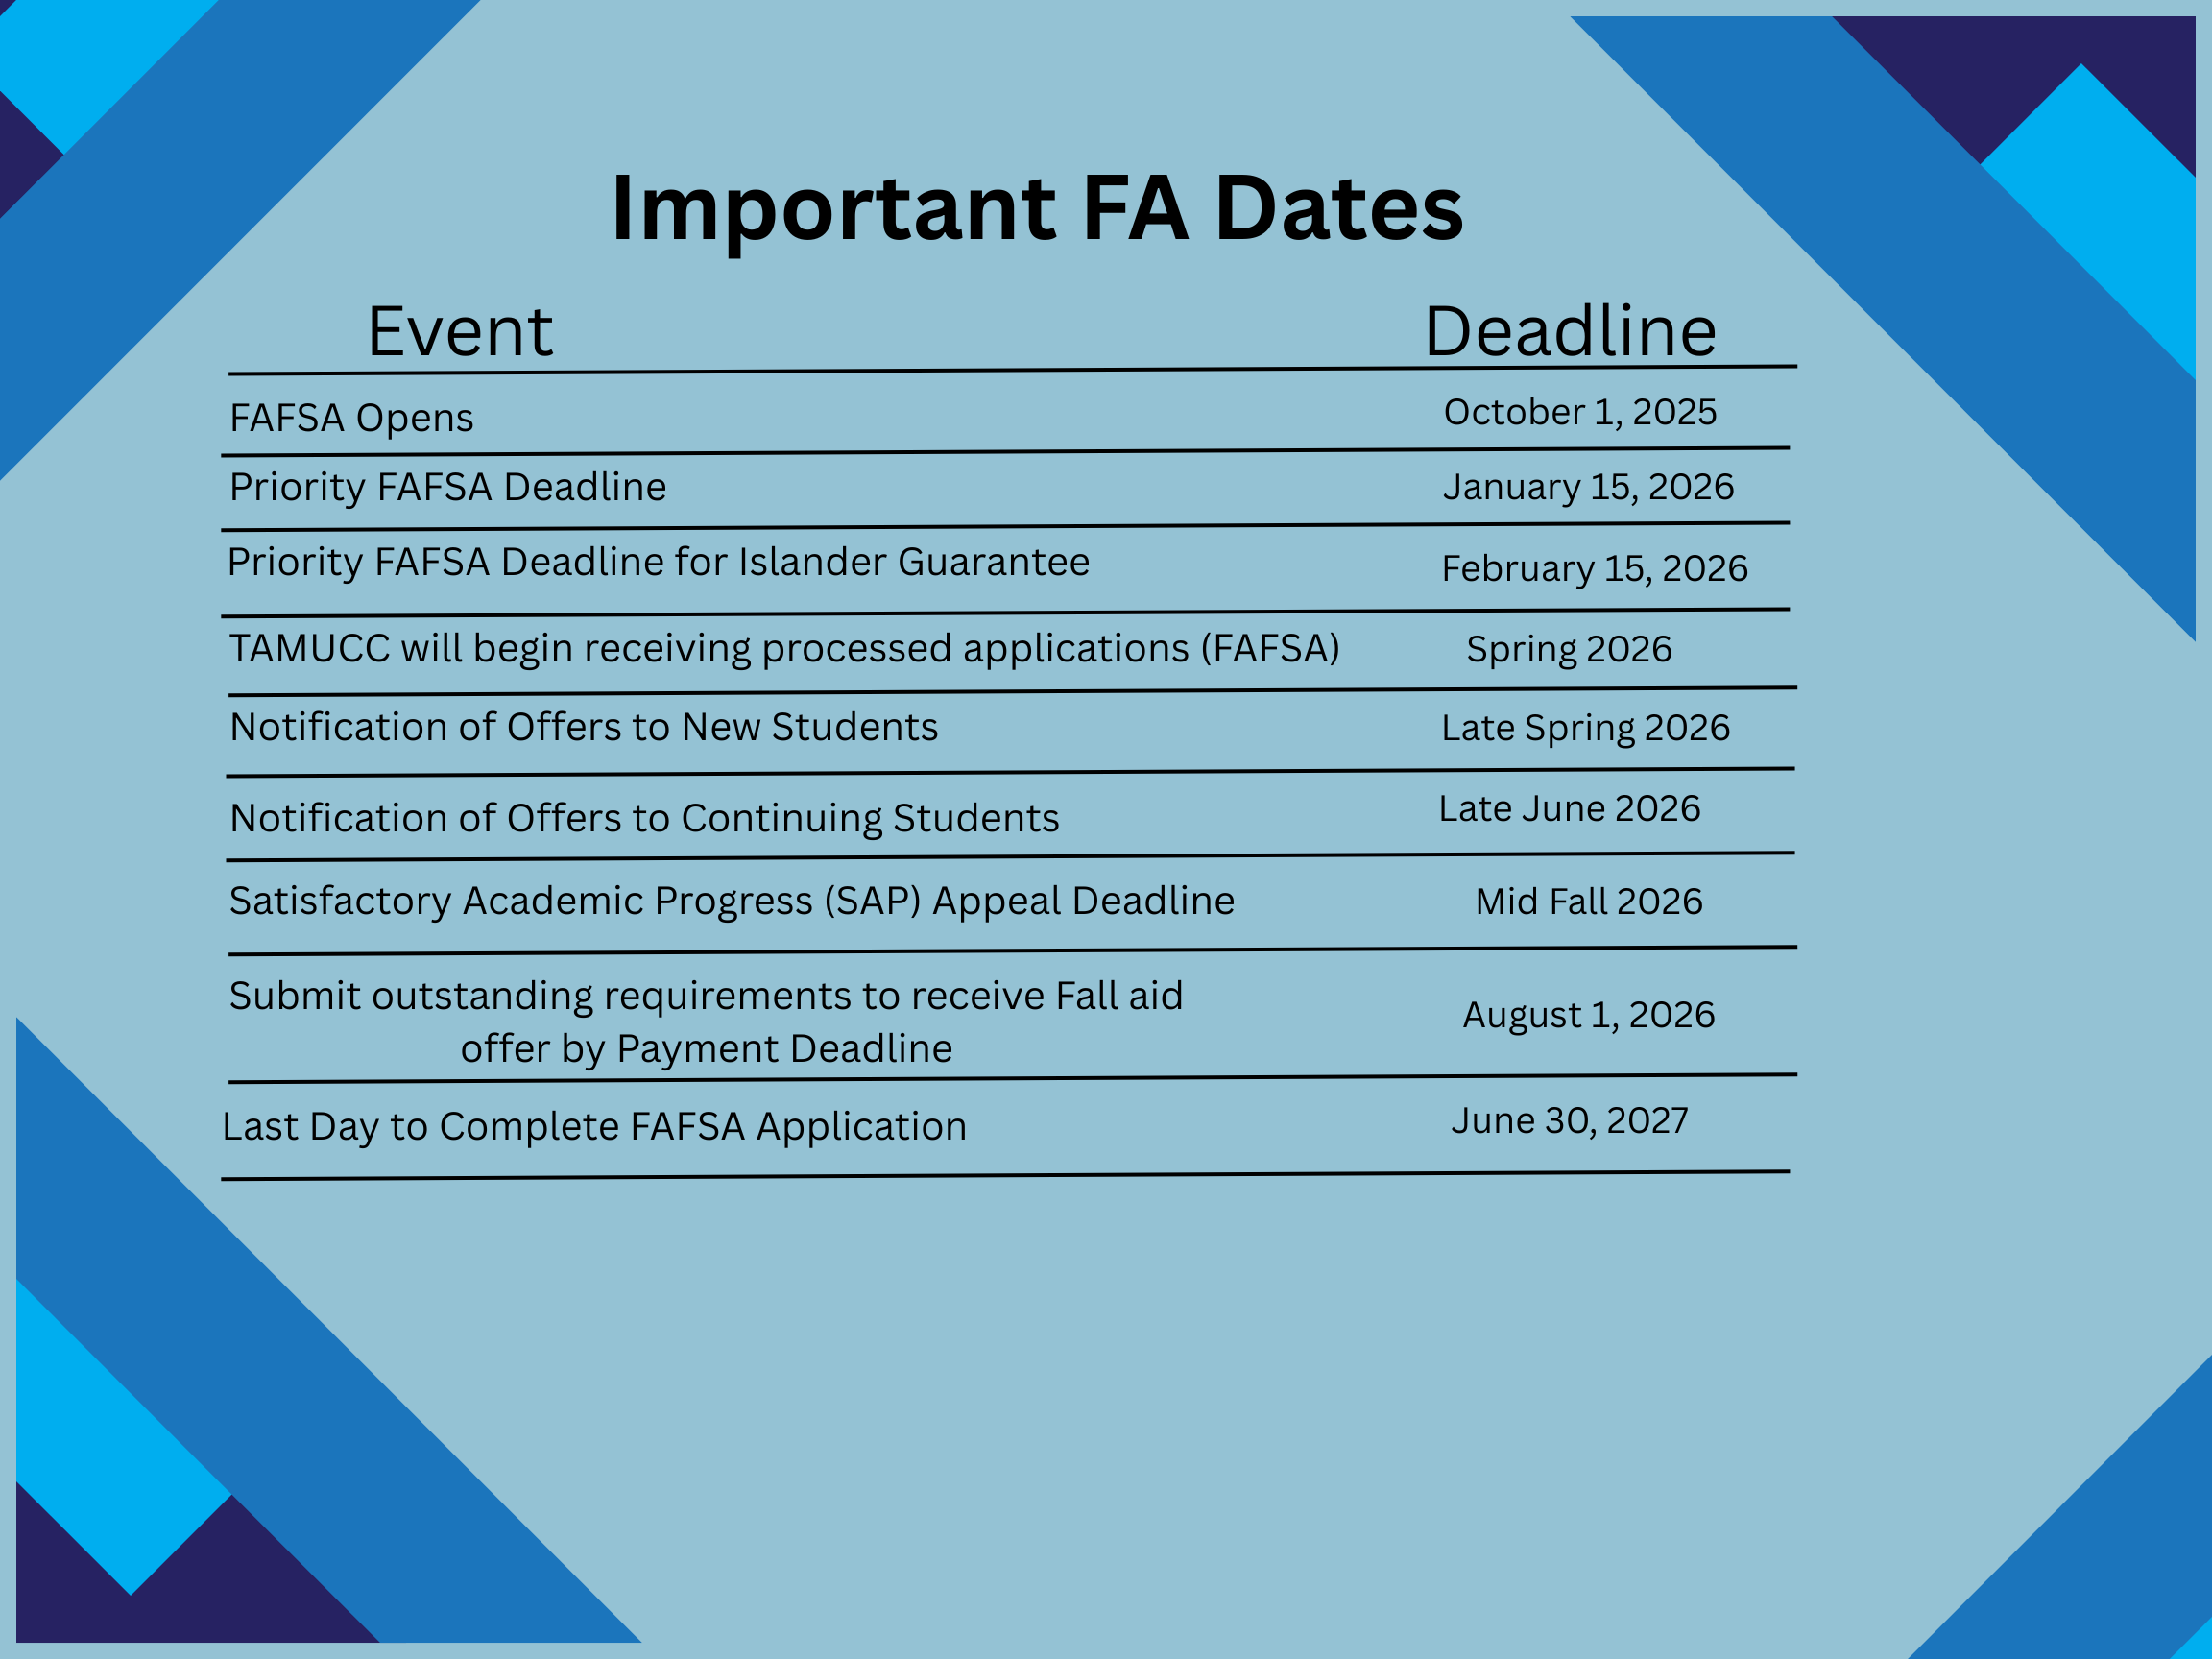
The University Financial Aid Deadline isn't a single date you can circle on a calendar. It's a moving target that depends on what type of aid you're applying for, which school you're going to, and whether you filed on time. I spent eight years working in financial aid offices before moving to the other side, and even now I double-check dates because they shift every cycle. There are three layers to this. Federal deadlines set by the Department of Education are the broadest net, state deadlines run through individual agencies, and institutional deadlines are what your school actually cares about. Missing the federal deadline doesn't necessarily mean you lose everything, but it does mean you're working with fewer options. The federal FAFSA deadline for the 2025-2026 award year was June 30, 2026, but that number is mostly symbolic. Most schools have deadlines months earlier. Some community colleges don't close their doors until summer, while selective private universities want everything in by February or March if you want merit consideration alongside need-based aid.
I once had a student who submitted her FAFSA on June 28th because she assumed the federal deadline meant the end of the road. Her state grant program had closed on April 15th, and the institutional scholarship window shut April 1st. She lost roughly $8,000 in grant money that couldn't be recovered. The workaround she used was to appeal to the financial aid office directly with documentation of her circumstances, which sometimes works for emergency or recovery grants but never for state-funded programs that have hard stop dates.
The actual mechanics of filing on time
Start with the FAFSA. It opens on October 1st each year, which is earlier now than it used to be. The old system made students wait until their senior year of high school to discover the process. Now it's structured so you can apply during the fall before enrollment, which gives schools more time to process and students more time to understand what they're getting. The IRS Data Retrieval Tool is still the most reliable way to transfer tax information without manual entry errors. I've seen countless applications rejected or delayed because someone typed their adjusted gross income wrong by a few hundred dollars. The tool eliminates that variable entirely, though it does require you to have filed your taxes by the time you submit the FAFSA. If you're self-employed or your tax situation is complicated, you might need to estimate and then correct it later. Most schools ask for additional forms. The CSS Profile runs through College Board and costs money to submit. Some institutions require the Common App financial aid section, others have their own portal. Check what your target schools require before October 1st so you're not scrambling when the window opens. The total cost for CSS Profile submissions adds up quickly if you're applying to ten schools, each charging around $25 for the initial report plus $12 for each additional school.
Get the Full Details

Common pitfalls that catch people off guard
One thing people consistently misunderstand is that theFAFSA isn't a scholarship application. It's a data collection exercise that determines your Expected Family Contribution, which schools then use to build your aid package. Getting a low EFC doesn't guarantee you'll receive anything. It just means the formula says your family should be able to contribute less than the calculated amount. Another gotcha is the renewal process. If you filed in your first year of college, you still need to submit a new FAFSA every subsequent year. The prior-year data carries over partially, but your family's financial situation can change dramatically between years. A parent losing a job, a medical emergency, a divorce, even receiving an inheritance. All of these affect your EFC and your eligibility for additional aid. The most counter-intuitive thing I learned after years in this work is that submitting early rarely gives you meaningful advantage for need-based aid. Need analysis happens after the deadline anyway. Early submission matters most for state grants and institutional scholarships that operate on a first-come, first-served basis. Some schools distribute their limited merit scholarship pool before the general deadline passes.
There's also the issue of correction cycles. Once you submit the FAFSA, you can't edit it freely. If you need to make changes, you have to log back in and submit corrections through the FAFSA website, then wait for the updated information to process. Schools can see the revision history, but there's still a processing delay that can push you past internal cutoffs.
What happens when you miss the deadline
Missing the institutional deadline usually means you're downgraded to less favorable aid categories. You might still qualify for federal loans and basic grants, but the merit scholarships and work-study positions disappear. Some schools have late filing policies that allow penalties, but those typically involve administrative fees or reduced award amounts. The federal deadline is more forgiving in practice. If you miss June 30th, you can still submit for the following academic year. You won't get funding retroactively, but you won't be locked out entirely. State deadlines are harder to recover from. Most states have statutory funding limits and don't reopen once the fiscal year closes. I had a case where a student's family missed the state deadline because they were dealing with a funeral. The death occurred two weeks before the cutoff, and by the time they could handle the paperwork, the grant pool was exhausted. The only path forward was to appeal to the state agency directly, which required documentation from the funeral home and proof of when the tax filings were completed. It took three months and they received partial credit, but only because the state had a hardship provision that wasn't widely advertised.

Building your personal deadline strategy
The most practical approach is to create a tracking system that accounts for every deadline your target schools require. Make a spreadsheet with columns for federal deadline, state deadline, institutional deadline, CSS Profile requirement, and any special forms. Update it as you research each school and mark when you've completed each component. Aim to submit the FAFSA within the first week of October if possible. That gives you time to resolve any issues before the rush. The Department of Education experiences server slowdowns in mid to late October as volume spikes, and technical problems during that window can push your submission past internal school deadlines. Check your email and your school's student portal regularly after submitting. Some schools request additional documentation, and failing to respond within their stated timeframe can void your application. I've seen students miss appeals because they didn't check their spam folder for three weeks.
When you receive your financial aid offer, read it carefully. The numbers presented might look generous, but they could include loan requirements or work-study expectations that don't match your situation. If something seems unclear, contact the financial aid office directly. Don't assume the package is final, and don't hesitate to request clarification or appeal if your circumstances have changed since you submitted the FAFSA. Some schools allow you to petition for a deadline extension if you have documented reasons. Medical emergencies, family crises, technical failures, even errors made by the school itself during processing. The success rate varies significantly by institution, but having a written explanation with supporting documentation typically improves your chances. Start that conversation early rather than waiting until after you've missed the date.