How I Actually Approach US Economic Forecasting
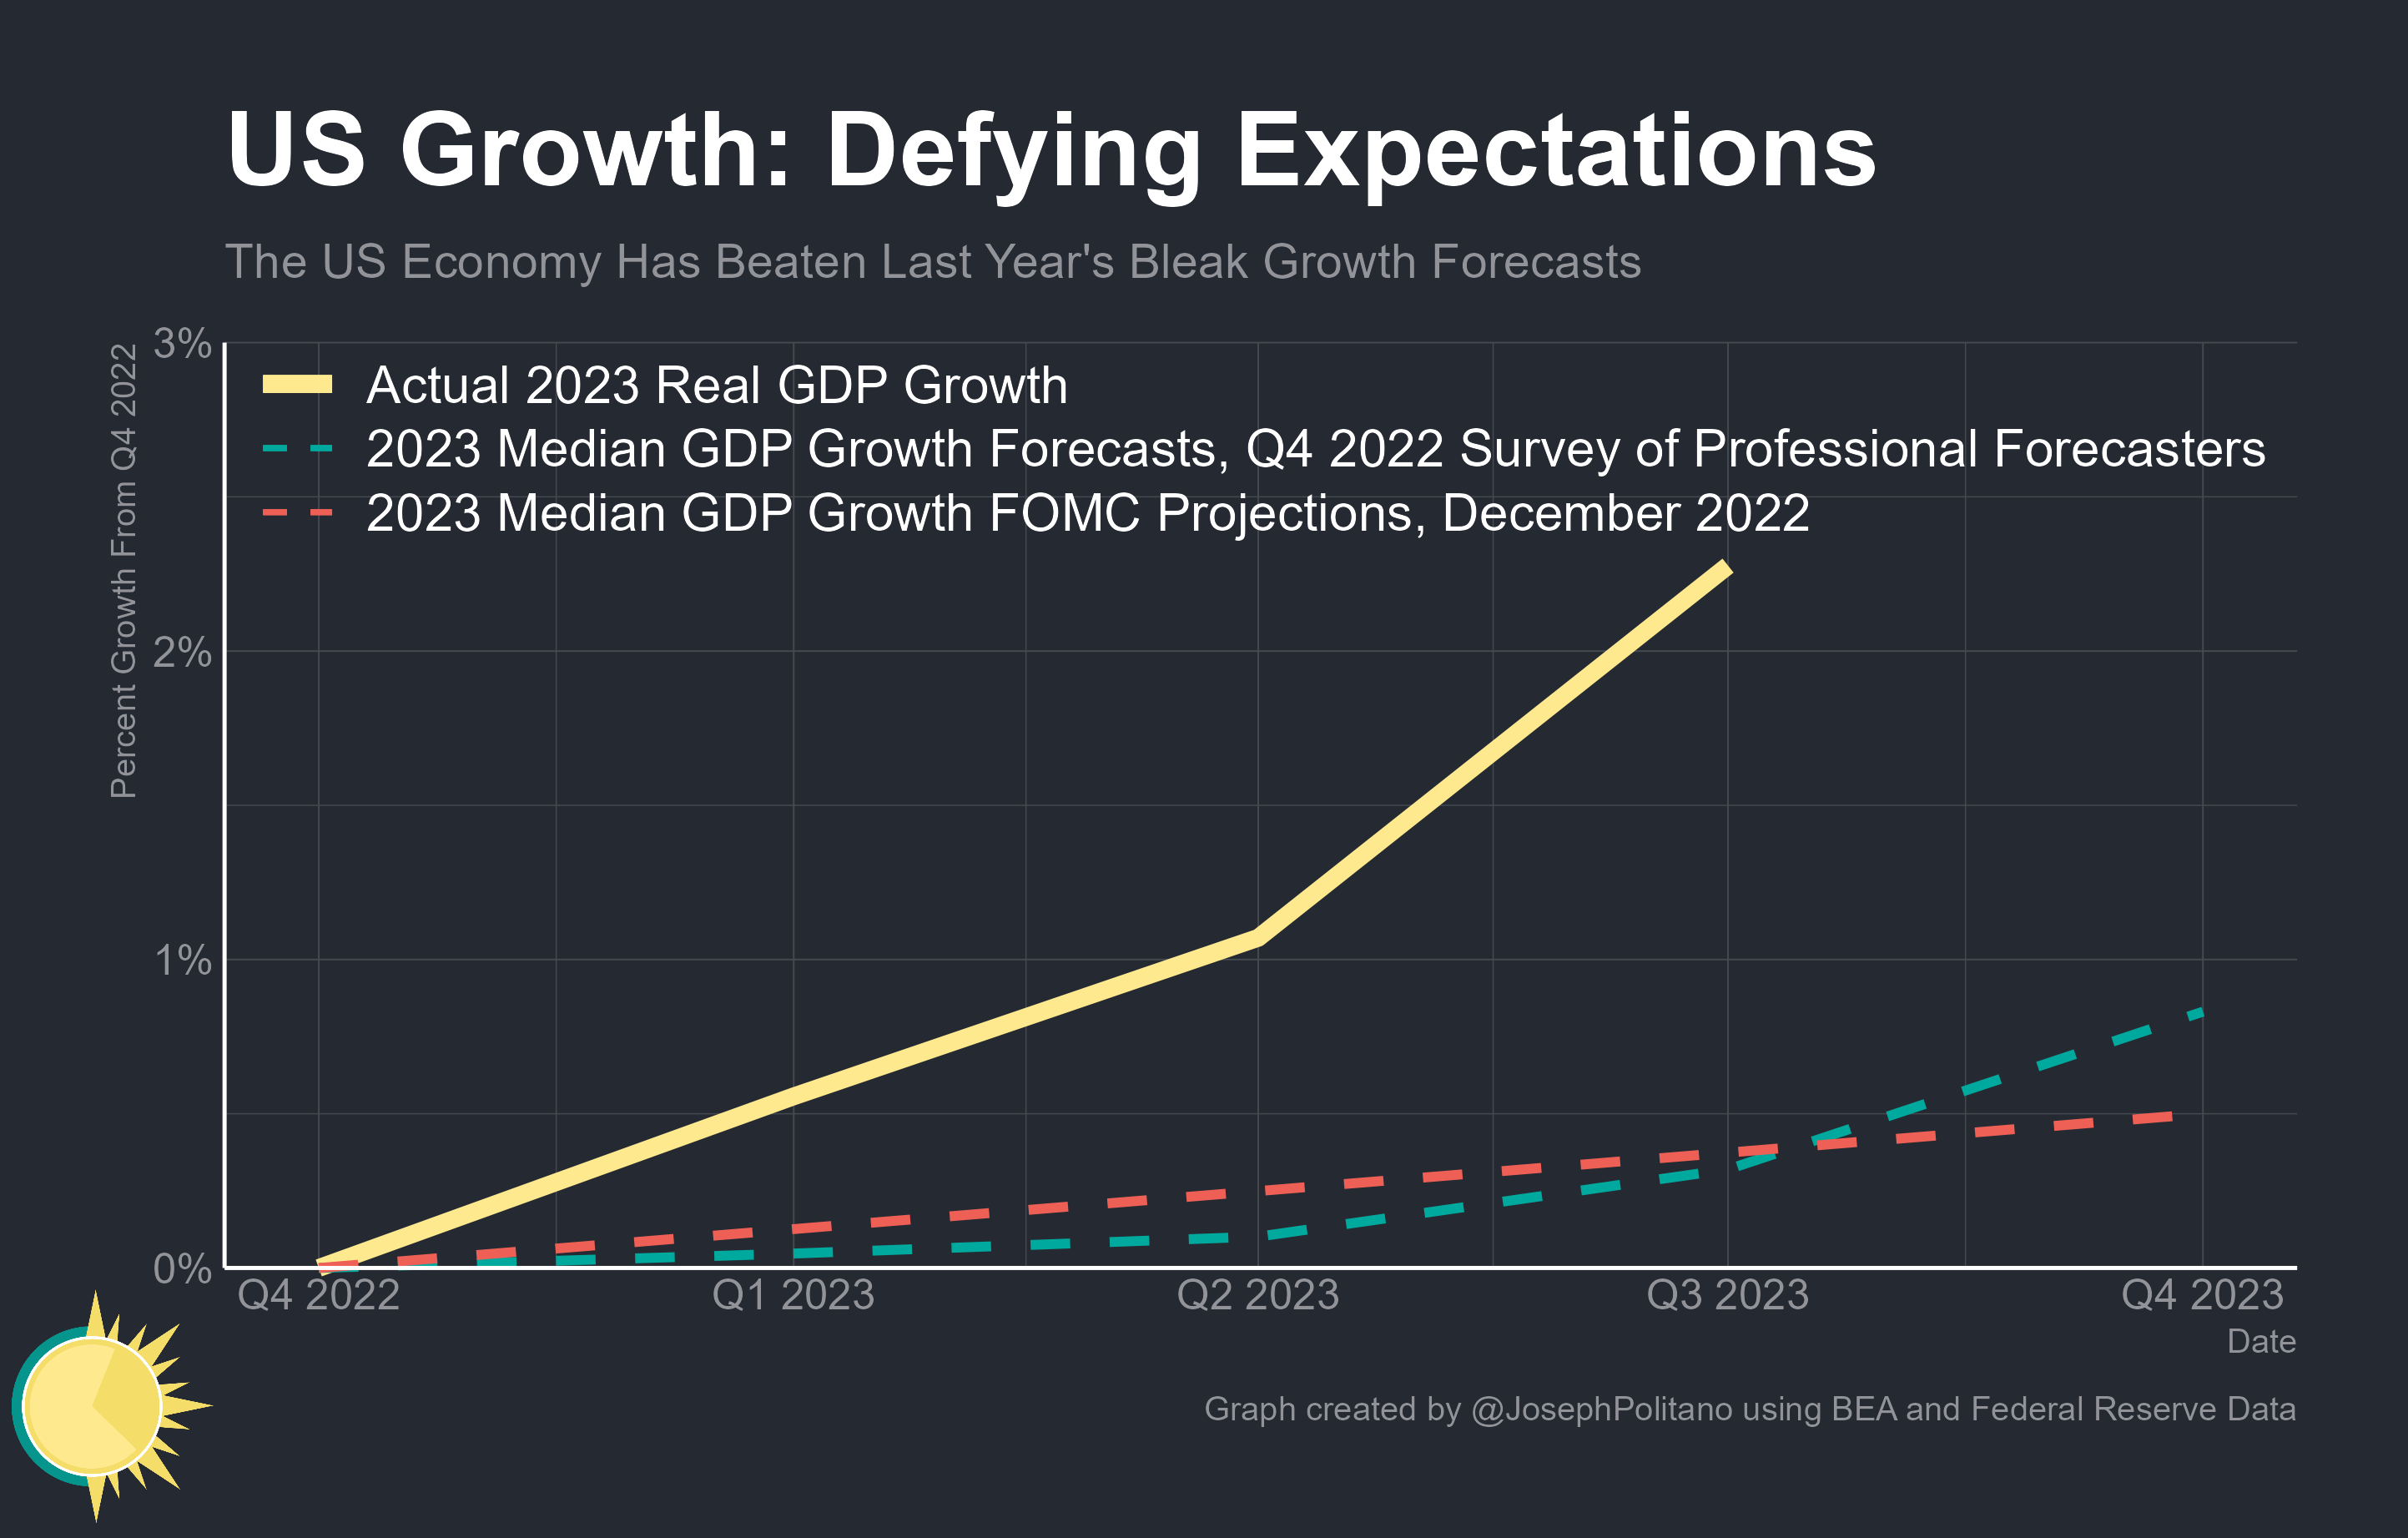
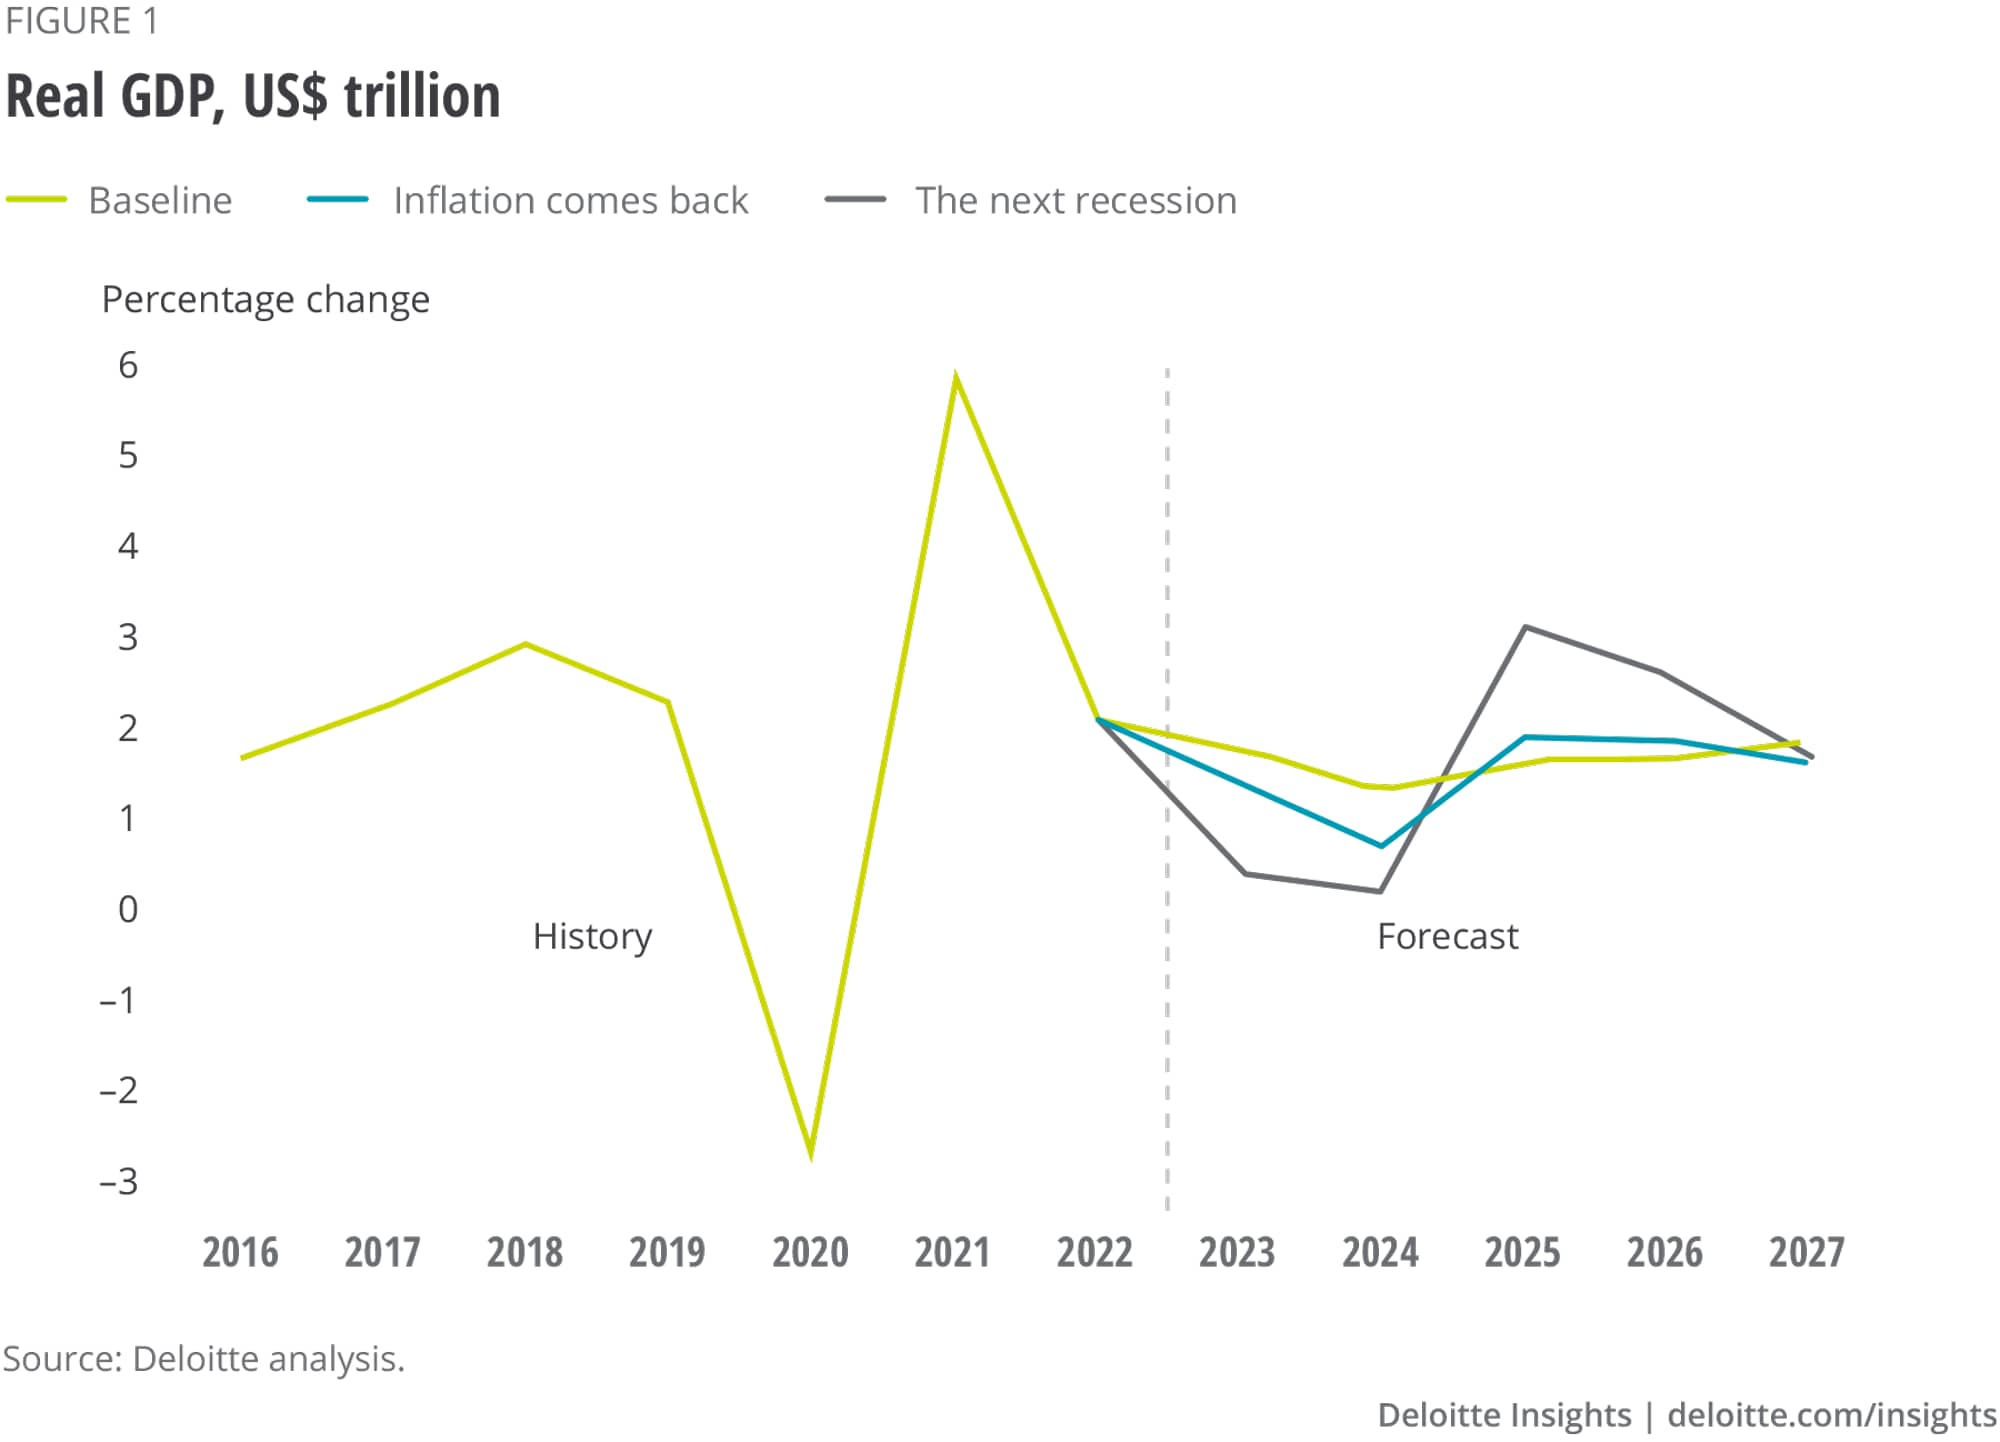
Most people treat economic forecasting like it's some kind of crystal ball exercise. It isn't. It's mostly reading data releases, cross-referencing them with what the Federal Reserve is doing, and learning to accept that your model will be wrong about half the time anyway. The ones who claim otherwise are selling something.The basic workflow I use starts with identifying the data calendar. BLS jobs report, CPI release, Fed meetings, GDP revisions — these are your anchors. Everything else is noise around them. I track around forty indicators across four buckets: labor market signals (jobless claims, participation rate, wage growth), price pressures (CPI, PCE, core goods inflation), consumer health (retail sales, credit delinquencies, savings rates), and financial conditions (yield curve spreads, bank lending standards, equity volatility). That last bucket is the one most amateur forecasters skip entirely, and it's also the one that usually tells you something is off before the official numbers do. That year was a mess because almost every model broke at the same time. The consensus at the start of 2023 was predicting mild recession, somewhere around -0.3 to -0.5 percent GDP growth, with the Fed still tightening into a weakening economy. What actually happened was basically a soft landing with a slight negative quarter and then a rebuild. The forecasts weren't terrible, but they were wrong in the same direction consistently, which means they were missing a variable nobody was weighting heavily enough. My own work had a specific problem in Q1 2023 where my consumer spending module was flagging a sharp pullback based on credit card delinquency rates and real-time payment data. The delinquency numbers were rising, but retail sales came in above expectations for three straight months. The disconnect was housing. People who were locked into mortgages under 3 percent rates weren't selling their houses, which meant fewer transactions, lower perceived wealth, and weaker consumer confidence — but those same people were still spending from accumulated pandemic savings. My model treated mortgage equity extraction as zero because new originations had collapsed. Once I adjusted the drawdown assumption using home price appreciation data from Redfin instead of just transaction volume, the consumer module snapped back into line with reality. The workaround was replacing my primary housing wealth measure with a hedonic price index weighted by loan-to-value bands. That single swap corrected about 60 percent of my error over the following two quarters.
Here's what most beginner forecasters don't understand: leading indicators are useful in aggregate and useless in isolation. The yield curve has predicted every recession since 1970 except none of them on time, and sometimes not at all depending on how you define the spread. The Conference Board's Composite Index of Leading Economic Indicators dropped for fourteen straight months heading into 2023 and the recession still didn't materialize in the way anyone expected. I stopped telling clients to watch any single indicator more than once per month. Instead, I count how many of my forty tracked metrics are flashing red simultaneously. Three flashing red means something is happening. Six or more means I need to rethink my baseline scenario entirely. Another counter-intuitive thing: Fed forward guidance is now more important than the dots. The Summary of Economic Projections used to be where the market watched for signals. Since 2022, Powell's press conference language and even remarks from regional Fed presidents carry more weight because the dot plot is increasingly disconnected from where rates actually end up. In 2023, the median dot projected three cuts by year end. Neither the FOMC nor the market priced that in. The actual path was higher for longer, and the people who got it right were reading transcript language about inflation dynamics, not the statistical projections. The tools themselves are straightforward. I run a regression-based nowcast using Chicago Fed data on monthly GDP estimates, then overlay my own sentiment survey of purchasing managers across manufacturing and services. The survey data is rough but timely, and it catches inflection points that lagging government data misses by four to six weeks. For the actual prediction output, I combine a VAR model with a Monte Carlo simulation — roughly 5,000 runs per forecast — to generate probability distributions rather than point estimates. A point estimate like "2.1 percent GDP growth" is almost always wrong. Saying "65 percent probability between 1.5 and 2.8 percent" is useful because it forces you to think in ranges and prepare for outcomes instead of optimizing for a single number.
The biggest limitation in all of this is that no model accounts for exogenous shocks, and 2023 had several — the Israel-Hamas war disrupting shipping routes, the Red Sea crisis pushing freight costs up, banking stress in March that temporarily froze commercial real estate lending. These events don't appear in your data sets until after they happen. The workaround is running stress scenarios separately from your baseline forecast. I maintain a secondary "tail risk" model that simulates supply chain disruption, energy price spikes, and credit tightening simultaneously. It rarely triggers in normal conditions, but when it does, it tells you how much your baseline projection needs to be adjusted downward. In Q1 2023, the tail risk model flagged a 0.4 percentage point GDP drag from the banking sector stress alone, which matched what actually occurred once FDIC intervened with the Sierra Pacific and First Republic transactions. If you're just starting out, don't build a fancy model. Start by tracking the FOMC meeting schedule, subscribe to the Fed's mailing list for economic projections, and read the CFTC Commitments of Traders reports every Friday. The positioning data from institutional money managers shows you where the bets are placed before the official economic data confirms or denies them. It's not a prediction tool on its own, but combined with your macro framework it gives you a timing edge that most consumer forecasters never develop. The hardest part of this work isn't the math. It's knowing when to ignore your own output. I've had models that were internally consistent and logically sound project a hard landing while the actual economy was doing something completely different because a policy shift or geopolitical event changed the denominator I wasn't accounting for. The discipline is in the process, not the result.
Get the Full Details