Understanding Economic Growth Across Different Time Horizons
When people talk about economic growth in the United States, they're usually thinking about either the quarterly GDP reports that dominate the news cycle or the broader multi-decade trends that shape policy debates. These two views aren't always aligned, and conflating them leads to some genuinely bad decision-making by investors and policymakers alike. Short-term growth is measured in quarters, sometimes monthly. The Bureau of Economic Analysis releases GDP estimates on a quarterly basis with revisions coming in about a month, then again a month later, and a final advance reading around a year out. It's not as precise as people think. Consumer spending drives about 70% of US GDP, so it moves fast based on sentiment shifts, supply chain hiccups, or a sudden change in employment conditions. The Federal Reserve watches this closely because it determines whether they need to adjust interest rates.
Us Short Term And Long Term Economic Growth
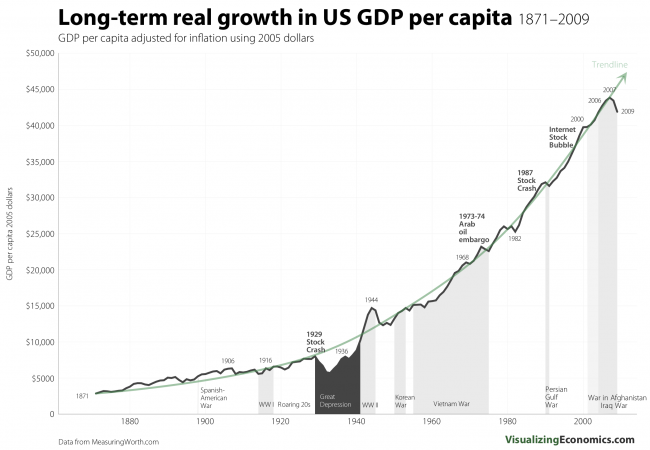
Long-term growth is a completely different beast. It's measured in decades and driven by productivity improvements, population changes, capital accumulation, and institutional factors. The Congressional Budget Office produces its own estimates every two years based on the current law projections, and they typically project trend GDP growth around 1.8% to 2% annually for the US. This number feels low if you compare it to the double-digit growth rates of postwar decades, but that was an outlier period driven by specific historical conditions that won't repeat. I've spent years working on growth forecasting and modeling these dynamics. One thing that trips up most people is the revision cycle on short-term data. Let me give you a concrete example from my own experience. Back in early 2023, the Q4 2022 GDP print came in weaker than expected, which got a lot of media attention and market volatility. But the revision two months later added nearly a full percentage point to that quarter's growth. The headline number looked like a recession warning. The revised number told a different story. If you make decisions based on advance readings alone, you'll get burned repeatedly. The same revision problem exists at the long-term end. CBO projections have consistently overestimated future GDP by roughly 0.3 to 0.5 percentage points per year compared to what actually materializes. This isn't a minor error. Over a ten-year horizon, that compounds into a significant miscalculation of fiscal trajectories and debt sustainability. The CBO itself acknowledges this pattern but the structural reasons are hard to pin down because unforeseen technological breakthroughs or demographic shocks are by definition unpredictable.
Here's a nuance that doesn't get enough attention: short-term and long-term growth rates don't necessarily correlate the way people assume. A country can have strong long-term growth prospects but go through five or six years of painful adjustment. The US experienced something like this between 2008 and 2011 when potential output was growing near 2% but actual output was depressed by a massive demand shock. Conversely, you can have a short-term boom that's entirely non-renewable, like the commodity-driven surge in certain periods that leaves you with higher inflation and no lasting productivity gain. The other thing people miss is how the measurement of GDP itself creates blind spots. The US GDP calculation has made adjustments over the decades to account for new products and quality changes, but it still undercounts certain dimensions of economic activity. Digital goods, free services like search and social media, and the sharing economy don't flow neatly into the existing framework. Some researchers at the BEA have worked on incorporating quality adjustments for technology products, but the methodology is imperfect and the revisions lag behind real-world changes by years. If you're trying to assess the health of the US economy for investment or policy purposes, you shouldn't rely on any single data point. Look at real GDP growth alongside labor force participation, productivity growth (which is essentially output per hour worked), and inflation expectations. The relationship between these measures tells you whether growth is sustainable or just noise. A period where GDP grows 3% but productivity is flat usually means either more hours are being worked or the growth is coming from nominal rather than real sources, which matters enormously when you're projecting long-term fiscal outcomes.
Get the Full Details
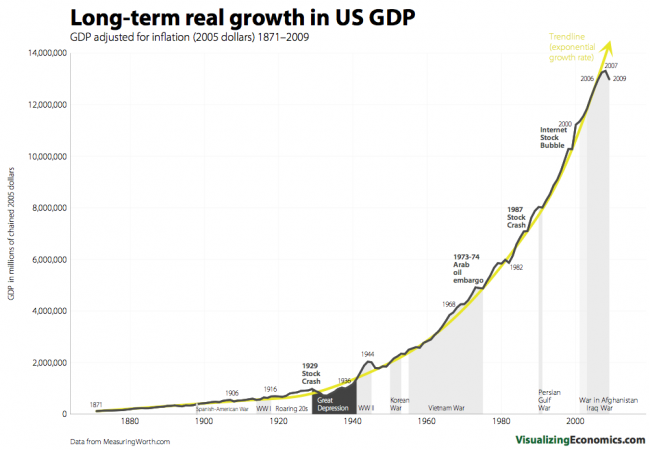
The Federal Reserve's dual mandate of maximum employment and price stability is really a short-term framework. They can't directly influence long-term growth rates very much, though monetary policy stability does create an environment where long-term growth becomes more likely. Central banks that maintain credible inflation control tend to see lower risk premiums and higher investment rates over time. But even the Fed admits they have limited influence over the structural factors that drive long-term productivity gains. Population growth is a bigger driver of US long-term growth than most people realize. The working-age population growth rate has been declining for decades, falling from around 1.2% annually in the 1990s to something closer to 0.5% in recent years. This directly reduces the denominator in productivity calculations and slows aggregate GDP growth even if per-capita productivity improves. Immigration policy debates aren't just political theater, they're fundamentally about long-term growth projections. The CBO's latest baseline assumes a gradual increase in net immigration, and the difference it makes to decade-long GDP projections is roughly 0.2 percentage points annually. One practical workaround I use when dealing with weak or contradictory short-term data is to look at high-frequency indicators like weekly jobless claims, the ISM manufacturing index, and retail sales. These aren't perfect but they move faster than GDP revisions. When the GDP advance estimate contradicts these indicators, I tend to weight the high-frequency data more heavily until the first revision comes out. It's saved me from several bad calls over the years.
There are also legitimate debates about whether US growth numbers are overstated or understated depending on which measurement approach you use. The NIPA (National Income and Product Accounts) framework used for GDP has known biases. Gross Domestic Product measures the value of goods and services produced within US borders regardless of who owns the producing entities. Gross National Product would include income from US citizens and companies abroad while excluding income earned by foreigners in the US. The difference used to be small but has been widening as US companies generate more foreign revenue. For understanding the domestic economic experience, GDP is the right metric. For understanding national income flow, GNP matters more. The bottom line is that short-term and long-term growth analysis require different tools, different data sources, and different tolerance for uncertainty. Trying to force a short-term model to make long-term predictions or vice versa will produce confident but wrong answers. The US economy has shown remarkable resilience across multiple decades, but that resilience depends on policy choices, technological adoption rates, and global conditions that are inherently unpredictable. Anyone who tells you they know exactly where US GDP growth will be in five or ten years is selling something.