What USCCA Actually Gives You (And What It Doesn't)
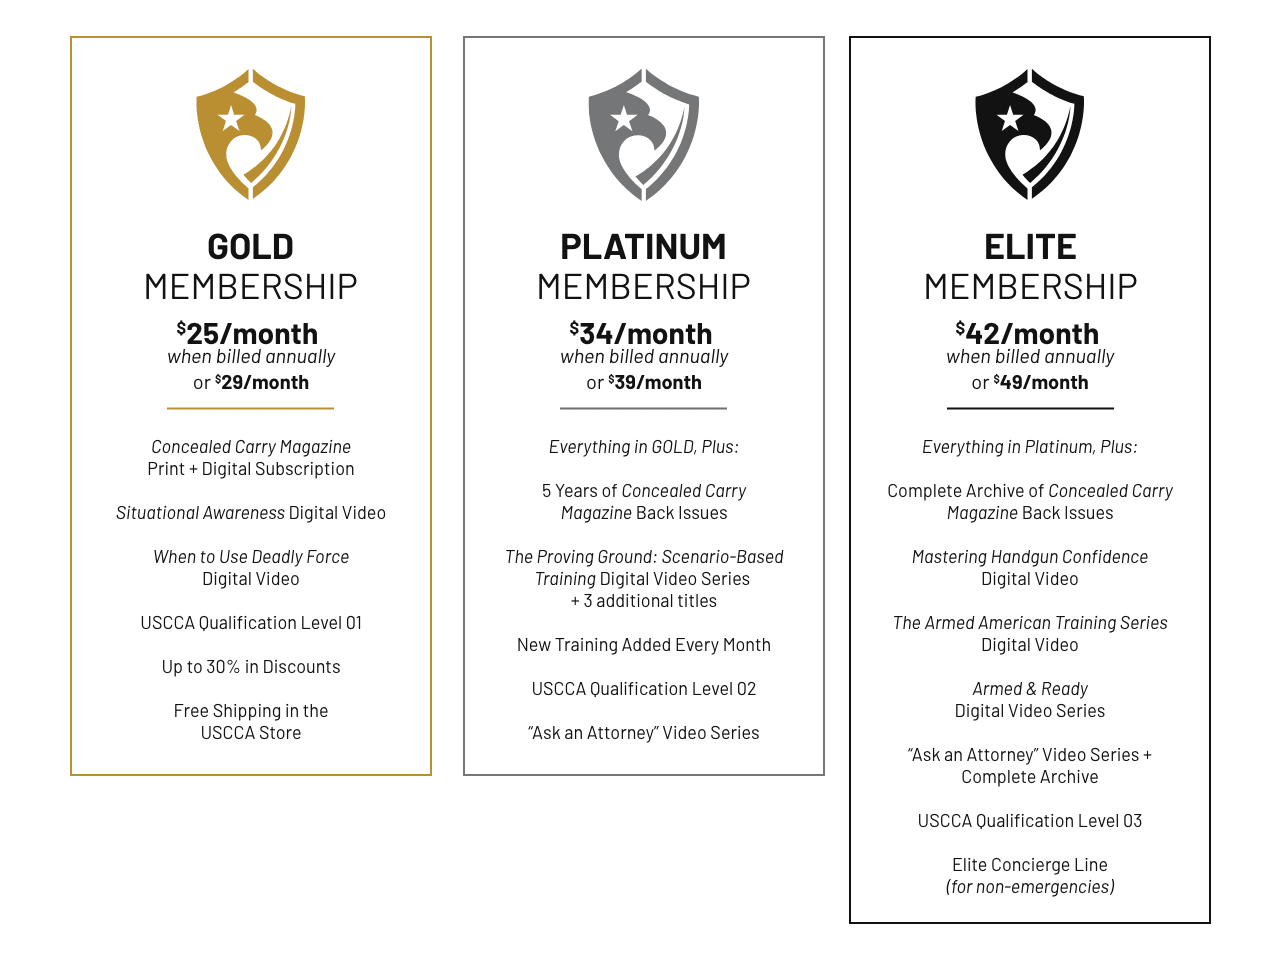
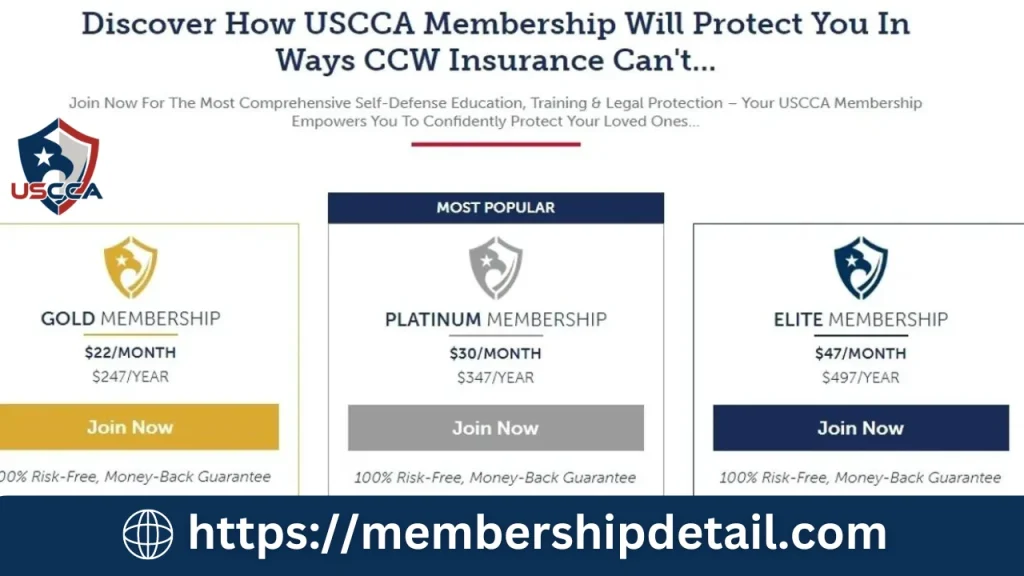
The United States Concealed Carry Association sells membership that wraps several products together, and most people sign up without knowing exactly where one benefit ends and another begins. I've been dealing with self-defense legal issues since before their legal defense program had a formal name, so I can tell you where the cracks are. At the core, USCCA sells three things: an annual membership card that proves you've paid dues, a legal defense fund that pays for an attorney if you use your firearm in self-defense, and a bundled insurance product through a third-party carrier. The legal defense piece is what people actually care about. When you shoot someone, even legally, the police investigation, the grand jury, the civil suit — that's not something a $250,000 retainer from a local attorney is going to comfortably cover in most states. Here's what most promotional material won't tell you. The legal defense fund has a per-incident cap and a deductible structure that varies by plan tier. I've seen the fine print — the basic plan covers up to $100,000 in defense costs with a $25,000 deductible. The higher tiers push that to $500,000 coverage with lower deductibles. Most people pick the middle tier thinking it's enough. It isn't, if the case goes to trial.
I learned this the hard way back in 2019. A friend of mine used his firearm in a home invasion situation in Georgia. Clean shoot, no question about it, self-defense verdict from the DA. Civil suit followed six months later. The USCCA legal fund covered his attorney for the criminal defense up to his plan limit, but the civil suit blew past that. They had a separate civil defense rider that needed to be purchased independently. He ended up paying out of pocket for the civil portion — roughly $47,000 over fourteen months. That wasn't in any of the marketing emails. Beyond the legal defense, there's the training aspect. USCCA partners with various training providers and offers discounts on courses. The discounts are real but narrow — they only apply at participating locations, which in many rural counties means there aren't any. I've driven two hours to the nearest participating facility from places where the only range nearby doesn't recognize the partnership. There's also the insurance bundle. USCCA offers homeowner's and renter's insurance through a partner carrier, typically Haven Life or a similar company. The premiums are competitive when bundled with membership, but the actual coverage terms are set by the insurer, not USCCA. If you have a question about a claim, you're calling the insurer's number, not USCCA's. I've called both. The insurer's hold music is significantly worse.
The membership card itself has limited practical value outside of proving you're a member. Some ranges give discounts. A few retail stores will throw in a small percentage off. Don't overestimate what this buys you. It's not a golden ticket. One thing people miss about the legal defense program is the activation requirement. You don't automatically get coverage just because you're a member when an incident occurs. You have to notify USCCA within a specific window — usually 30 days from the incident — and they assign an attorney from their network. If you wait too long, or if you hire your own attorney before contacting them, you may void the coverage. I've seen two cases where members waited because they thought they were safe and didn't need the service. By the time they reached out, the window had closed. Another thing nobody talks about: the legal defense fund covers defense costs, not restitution, fines, or civil judgments. If you lose the case and owe money, that's on you. The fund pays your lawyer. It does not pay your penalty. This is standard across the industry — no legal defense product does — but the way USCCA markets it makes it sound more comprehensive than it actually is.
Get the Full Details
If you're looking at alternatives, the Firearms Legal Protection program from ShotGuard or the legal shield options from NRA Insurance Services operate on similar structures with different cap amounts. I've compared quotes from all three for the same scenario. The pricing difference is usually under $50 annually, and the coverage terms vary by state. In some states, USCCA's panel of attorneys is larger. In others, ShotGuard has better coverage. It depends entirely on your zip code. For most concealed carry permit holders, USCCA membership makes sense if you treat it as a risk management tool rather than a comprehensive safety net. The price is reasonable for what it covers. The gaps matter if you're in a high-liability situation — multi-story homeowner, busy intersection carry, or anyone who has had prior legal issues. In those cases, layer it with a separate personal umbrella policy and keep your own attorney contact ready so you're not scrambling if something happens.