Understanding What You're Actually Looking For
A standard USDA loan runs for 30 years. That is what the program is built around. I have never seen an actual 33-year USDA term offered by the agency or its approved lenders. When you search for a Usda 33 Year Loan Calculator, you are likely running into one of two things: either a custom mortgage calculator that lets you set arbitrary terms, or a site mixing up USDA with other loan programs that have non-standard amortization periods. Here is how this actually plays out in practice. I helped a client last fall who was convinced her lender offered a 33-year USDA option because she saw it on a calculator page online. The lender had used a third-party tool where you can type any number into the term field. It was not a real product. She nearly signed paperwork based on monthly payments that looked lower than they would actually be under a real 30-year USDA rate. Caught it before closing, but it was close.
How to Use a Usda 33 Year Loan Calculator Correctly
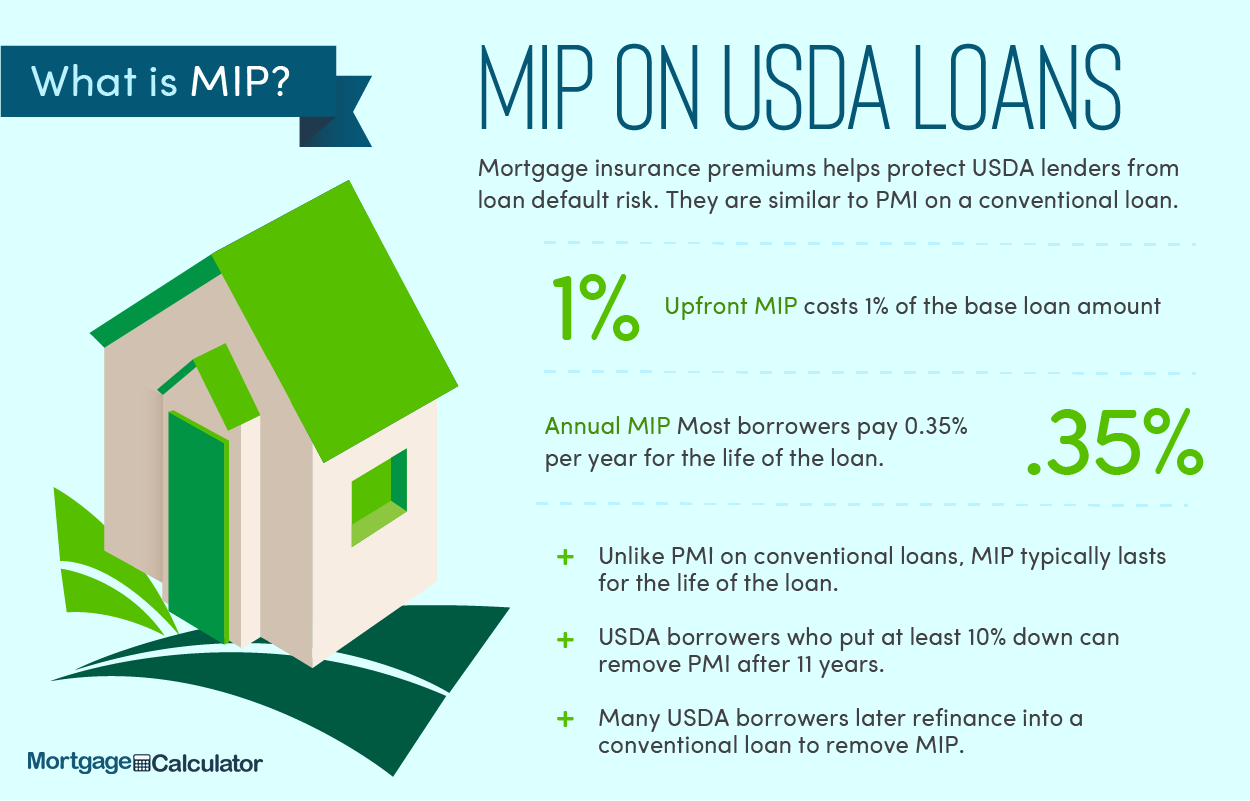
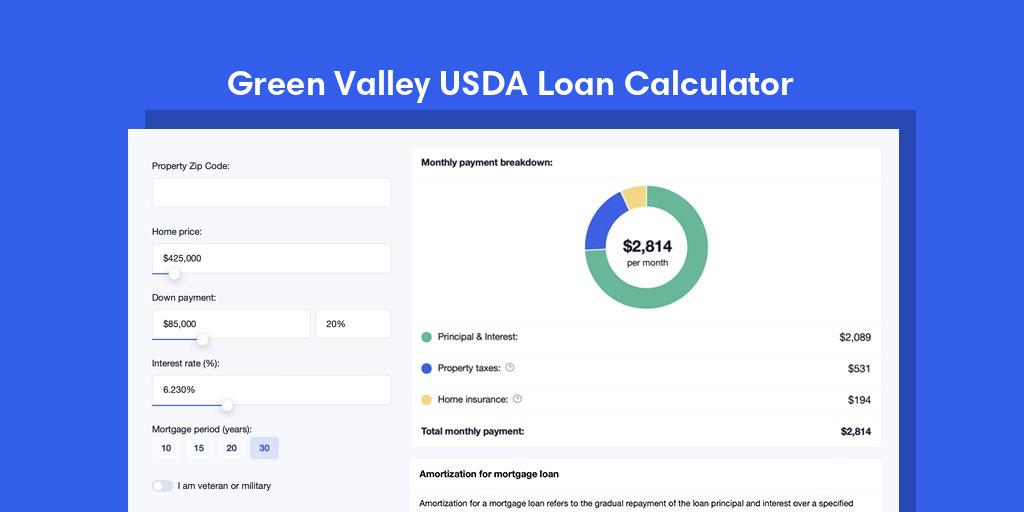
Start by understanding what the calculator is actually doing. Most online USDA calculators will ask for the home price, your annual income, the down payment amount, the interest rate, and the loan term. You plug those numbers in and hit calculate. The output shows your estimated monthly principal and interest payment, plus the total interest you will pay over the life of the loan. Some also break out property taxes and homeowners insurance if you enter those separately. When you see a calculator offering a 33-year term for USDA, treat it as a hypothetical exercise only. It can still give you a rough sense of how extending the amortization period affects your monthly payment. But the numbers will not match any real USDA offer. A real USDA 30-year fixed loan uses a specific pricing sheet from the USDA Rural Development Guaranteed Housing Loan program, and the rate your lender quotes is based on that sheet, not on an arbitrary number you type into a tool. One thing most people miss: USDA loans have two separate fees that dramatically affect the math. The guarantee fee is split into an upfront portion and an annual portion. The upfront fee, currently 1 percent for most borrowers, can be rolled into the loan balance. The annual fee, around 0.35 percent, gets divided into twelve monthly charges and added to your payment. If you run a calculator without accounting for both of those, your monthly number will be roughly 8 to 12 percent too low. That is a big gap when you are budgeting.
I ran into a specific edge case a while back where the upfront guarantee fee got double-counted in someone's calculator. They had a home price of $220,000 with zero down. The calculator applied the 1 percent upfront fee to the base loan amount, then again to the total after the fee was added. Instead of financing $2,200 in fees, it was adding $2,222. Over 30 years at 6.5 percent, that extra $22 in principal compounded into roughly $240 in additional interest. Small on paper, but it added up. The fix was straightforward: make sure the calculator bases the upfront fee only on the original loan amount, not on the loan amount plus the fee itself. If your tool is not doing that, switch tools.
Get the Full Details

What the Numbers Actually Show You
Let me walk through a realistic example. Say you are buying a $200,000 home in an eligible rural area. You have $0 for a down payment because USDA allows that. Your income qualifies under the program limits for your county. The current interest rate is around 6.75 percent. The upfront guarantee fee is 1 percent, which brings your loan amount to $202,000. The annual fee of 0.35 percent adds about $58 per month on top of principal and interest. Your principal and interest payment on that $202,000 at 6.75 percent over 30 years comes out to roughly $1,311. Add the annual fee and you are looking at about $1,369 per month before taxes and insurance. If you extend the term to 33 years just to see what happens, the principal and interest drops to about $1,244, and with the annual fee included you get roughly $1,302. You save about $67 a month on paper. But you pay about $28,000 more in total interest over the life of the loan, and you are tied to the debt three years longer. That is the trade-off most calculators will not explicitly tell you unless you dig into the totals.
The Hard Limitations Nobody Talks About
Online calculators, including any that let you run a 33-year scenario, have real blind spots. They do not account for credit score adjustments. Lenders price USDA rates based on your credit tier, and a score in the low 600s can add 0.5 to 1.0 percent to your rate compared to someone with a 740. That is a massive difference in monthly payment that a generic calculator cannot predict. They also ignore compensating factors. USDA is a bit different from conventional loans in that the agency looks at the whole file. A strong employment history, residual income above the minimum, or a low debt-to-income ratio can sometimes offset a weaker area on the application. A calculator sees only numbers you type in. It does not know that your particular profile might qualify for a better rate or that your county might have a different income limit than the national median. Another issue: these tools rarely factor in the funding fee changes. The USDA adjusts its guarantee fee percentages periodically. If you found a calculator article that references old fee percentages, the numbers are already stale. Always check the current fee schedule on the USDA Rural Development website before trusting any published example.
If you want something closer to a real answer than what a generic calculator gives you, the most reliable path is to get a Loan Estimate from a USDA-approved lender. That document will show your actual rate, your exact fees, and your true monthly payment including escrow. It takes about 10 minutes to request and you will have numbers you can actually build a budget around. Any calculator is a starting point, not a substitute for that. There are also some cases where a 33-year or extended-term approach makes more sense than you would expect. If you are self-employed with variable income and you need the lowest possible monthly payment to stay within USDA's debt-to-income ratios, stretching the term can sometimes be the difference between approval and denial. I had one borrower a couple years ago where a conventional 30-year put his front-end ratio just over the 29 percent threshold. A 33-year hypothetical payment brought him under it on paper, which meant the real 30-year USDA loan with its lower rate and subsidized pricing actually qualified him instead. The calculator insight led to the right product. That is the exception, not the rule, but it is worth knowing it exists.

Bottom Line on What to Do Next
Pick a calculator you trust and run a few scenarios with different interest rates and terms. Use the 33-year option as a stress test, not as an expectation. Compare the results to what a lender quotes you. If the numbers are wildly different, the calculator is probably using outdated fee percentages or wrong assumptions. Adjust and re-run. The goal is not to find a perfect number online. It is to get close enough that you know whether a USDA loan fits your situation before you spend time on an application.