What the USDA Guarantee Fee Actually Is
The guarantee fee is how the USDA backs up loans through its Single Family Housing Guaranteed Loan Program. It's not a traditional mortgage insurance premium paid to an insurer. The fee goes to the USDA to cover losses on the pool of guaranteed loans. When you take out a USDA loan, there's an upfront fee and an annual fee. Most people conflate them, but they're calculated completely differently and hit at different points in the loan lifecycle. The upfront guarantee fee is 1 percent of the loan amount. The annual guarantee fee runs at 0.35 percent of the unpaid principal balance, charged monthly. That's the basic structure. The calculator tools you find online are designed to spit out a clean number, but the real world is messier than that.
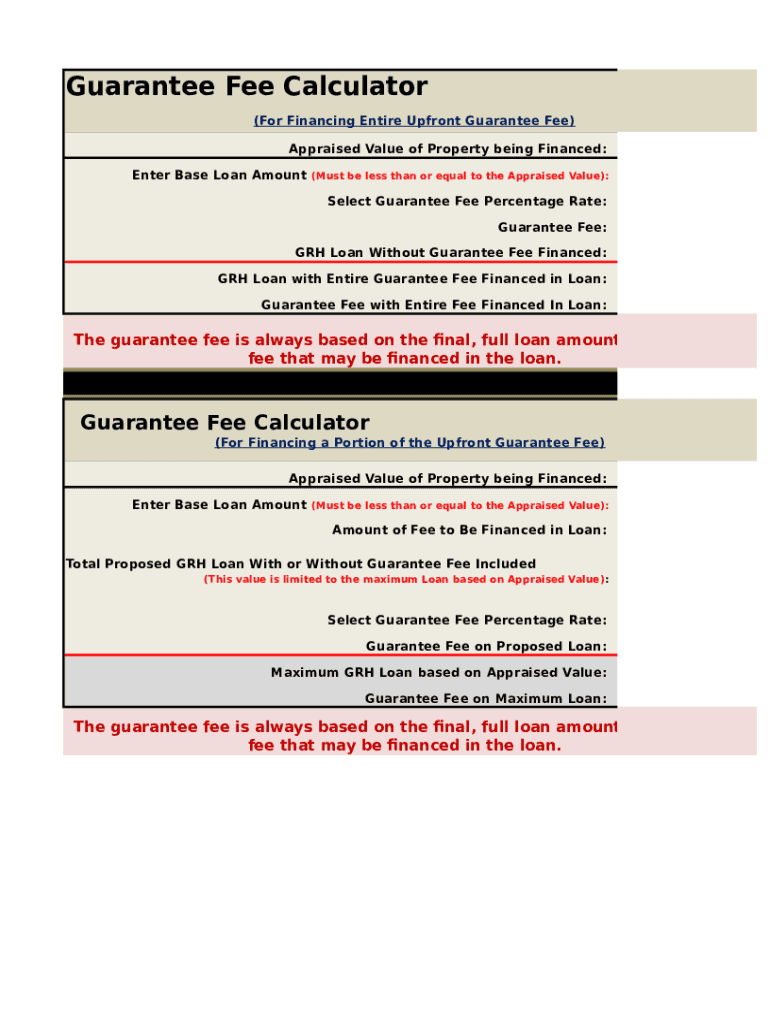
Usda Guarantee Fee Calculator
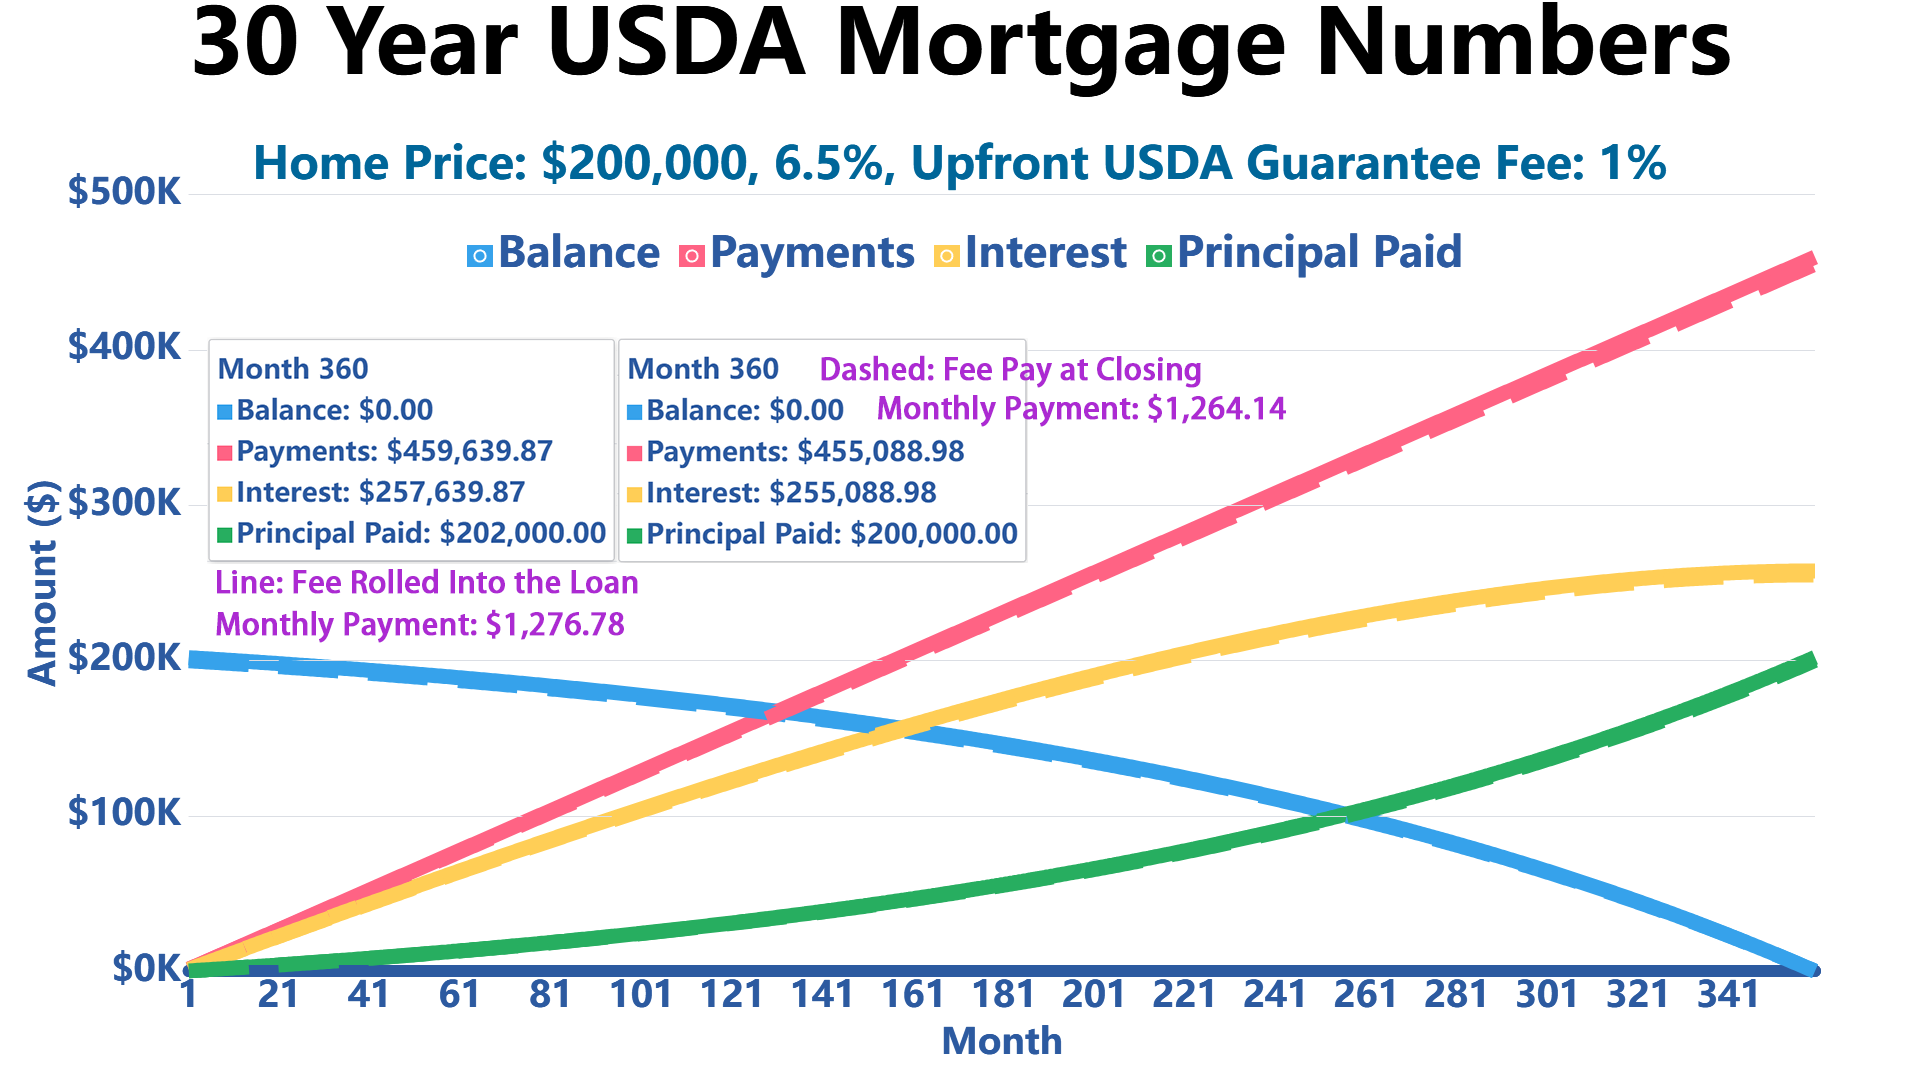
There isn't an official USDA-branded calculator you download from their website. What exists falls into three buckets: the USDA's own fee worksheets, third-party mortgage calculators that include a USDA section, and Excel-based tools built by loan officers over the years. If you're looking for a downloadable file, the best bet is usually a well-built spreadsheet rather than a web tool. Spreadsheets let you adjust scenarios without being locked into a single input format. Here's how I set one up when I need to show a client the exact breakdown. Start with the eligible loan amount. USDA loan limits vary by county, and that's where most mistakes happen. A $400,000 home price doesn't automatically mean a $400,000 loan. You have to factor in the financing of the upfront guarantee fee itself, which means the loan amount is slightly higher than the base price before fees. The math goes like this. Take your base loan amount, multiply by 0.01 to get the upfront fee, then add that fee to the loan. The new total becomes your actual financed amount. For the annual fee, divide the rate by 12, multiply by the monthly unpaid principal balance, and that's your monthly charge. It compounds as you pay down principal, so the monthly dollar amount drops every year. The earlier months carry the highest absolute cost because the unpaid balance is still large.
I use a spreadsheet with separate tabs for the upfront calculation and the amortized annual fee projection. You can find decent templates on lender intranets if you work in the space. Free public versions tend to be outdated or missing the finanical adjustment for rolling the upfront fee into the loan, which is the most common error I see.
Get the Full Details

How to Use a Calculator Without Getting the Wrong Answer
The biggest issue I run into is when people paste a home price into a generic calculator and treat the result as final. A USDA calculator is only as good as its assumptions. Input accuracy matters more than anything else. Here's the sequence that actually works. Step one: verify the county and income eligibility first. The guarantee fee exists regardless of location, but if the property or borrower doesn't qualify for USDA in the first place, the fee is irrelevant. USDA has a property eligibility map and income limits that change annually by household size and county. I always check those before running any fee numbers so we're not calculating a payment for a scenario that won't close. Step two: determine the maximum eligible loan amount for that county. County loan limits are published by USDA and reset every year. They differ between metro and non-metro areas within the same state. If you use a generic calculator that assumes a single national limit, your fee projection will be wrong. The upper bound changes frequently enough that I don't trust my memory on it. I pull the current limit from the USDA website before I do any math.
Step three: calculate the upfront guarantee fee based on the actual loan amount, not the purchase price. This is where the compounding effect bites. When the borrower finances the upfront fee into the loan, the fee is applied to a slightly larger number. The difference looks small on paper, but on a $350,000 loan it adds roughly $350 to the total cost of that upfront chunk. It matters when you're showing side-by-side comparisons against FHA or conventional loans. Step four: project the annual fee across the full amortization schedule. The annual guarantee fee isn't a flat dollar amount per year. It shrinks as the principal balance drops. A 30-year fixed at 4 percent will have the fee decline meaningfully over the first decade. If you just multiply the annual rate by the starting balance, you're overstating the true cost. I build a simple amortization table into the spreadsheet so the annual fee column updates automatically each month. Step five: add the annual fee to the PITI payment and compare it against alternative programs. The whole point of running this calculation is to see what the borrower's monthly payment looks like with the guarantee fee baked in. Without that comparison, the number is just a statistic. I always run FHA, VA, and conventional side-by-side so the client sees the tradeoff clearly. The upfront fee on a USDA loan is lower than FHA's MIP in most cases, but the ongoing annual fee adds up differently depending on how long they hold the loan.
Edge Cases That Break Simple Calculators
Not everything fits neatly into a standard formula. I ran into a case last year where a borrower in Hawaii was using a mainland calculator. The tool pulled a standard loan limit and a standard fee schedule, but USDA has separate provisions for high-cost areas like Hawaii and Guam. The upfront fee rate stayed the same, but the loan limit was significantly higher, which changed the dollar impact of the 1 percent fee substantially. The calculator returned a number that was off by about $8,000 on the upfront charge because it didn't account for the territory adjustment. I had to manually override the loan limit field and rerun the projection. That's the kind of thing that doesn't show up in any FAQ. Another scenario I deal with regularly is refinancing. The upfront guarantee fee on a refinance works differently than on a purchase. When you refinance a USDA loan into another USDA loan, you typically pay the upfront fee again, but it's calculated on the new loan amount, which may include wrapping in certain closing costs if they're eligible. Some calculators assume the refinance fee is zero or default to the purchase formula. I've seen clients told their refi would be fee-free because the tool they used didn't have a refinance branch in its logic. That simply isn't true under current USDA policy. Refinances carry the full 1 percent upfront fee unless they qualify for a streamlined refi option, and even then the terms have specific restrictions around credit history and payment testing. There's also the matter of loan assumption. If a buyer assumes an existing USDA loan, no new upfront guarantee fee is charged. Standard calculators won't tell you that. They'll default to the new loan formula and inflate the cost by a full percentage point. I flag this whenever a client is considering assuming a parent or relative's loan. It's a legitimate cost savings, but it only shows up when you understand the underlying program rules, not from pressing a button on a calculator page.
What the Calculator Gets Wrong and When to Pivot
Guarantee fee calculators are useful for rough estimates. They are not underwriting tools. I've seen loan officers hand clients a screenshot from a free online calculator and present it as a binding cost projection. That's risky. The actual fee is determined by USDA at closing, and there are minor adjustments that don't appear in any public calculator. Servicer billing cycles can affect how the annual fee is scheduled. Some servicers round to the nearest cent monthly, others use half-cent rounding, and the cumulative effect over 30 years can shift the total annual fee cost by a few hundred dollars. It's not material enough to panic over, but it's enough to make a calculator number look slightly off when you compare it to the closing documents. If you need precision, the workaround is straightforward. Run the calculator for an estimate, then confirm with the USDA Direct Program or your loan officer's internal system. Most lenders have access to the USDA's guaranteed loan pricing tools that pull real-time fee schedules and income limits. Those tools are behind a login wall, which is why public calculators can't replicate them exactly. The tradeoff is transparency for accuracy. There's also a hard limitation most calculators don't mention. The annual guarantee fee is charged for the life of the loan. Unlike FHA MIP, which can be dropped after a certain period if you have enough equity, the USDA annual fee stays until you refinance out of the program or pay off the loan. That's a critical detail. I've watched borrowers compare USDA favorably to FHA without realizing FHA's MIP expires while USDA's annual fee does not. The upfront savings on USDA can flip into a long-term disadvantage if the borrower plans to stay in the loan for fifteen years or more. The calculator number alone won't reveal that difference. You have to run a multiyear projection to see it.
A Practical Walkthrough
Say you have a loan amount of $300,000 in a qualifying rural area with a standard 30-year fixed term at 6.5 percent interest. The upfront guarantee fee is 1 percent, so that's $3,000. If you finance it, the new loan amount becomes $303,000. The actual upfront fee recalculates on $303,000, bringing it to $3,030. The difference is small, but it's the correct approach. For the annual fee, 0.35 percent divided by 12 gives you a monthly rate of roughly 0.02917 percent. On a $303,000 balance, the first month's annual fee comes to about $88.31. In month twelve, after making regular payments, the unpaid principal balance will have dropped, so the fee will be slightly lower. By year five, the monthly annual fee typically falls to the mid-eighty range. By year ten, you're looking at roughly seventy-five dollars per month. It's a slow decline, but it's consistent. If you want a downloadable setup, I recommend building a single Excel file with three sheets. Sheet one handles the upfront fee with inputs for purchase price, loan limit verification, and whether the fee is rolled into the loan. Sheet two runs the amortization and projects the annual fee month by month. Sheet three compares the total five-year and ten-year cost against FHA and conventional alternatives. It takes maybe twenty minutes to set up, and once it's done, you can plug in new scenarios without reopening any web tool or waiting for a page to load.
The tool is only as useful as the assumptions behind it. Run the numbers, check the county limits, and remember that the annual fee is a lifetime cost unless you leave the program. That's the part most quick calculators won't warn you about, and it's the part that actually matters when you're deciding whether USDA makes sense for a specific borrower.