USDA vs FHA: The Actual Differences That Matter When You're Applying
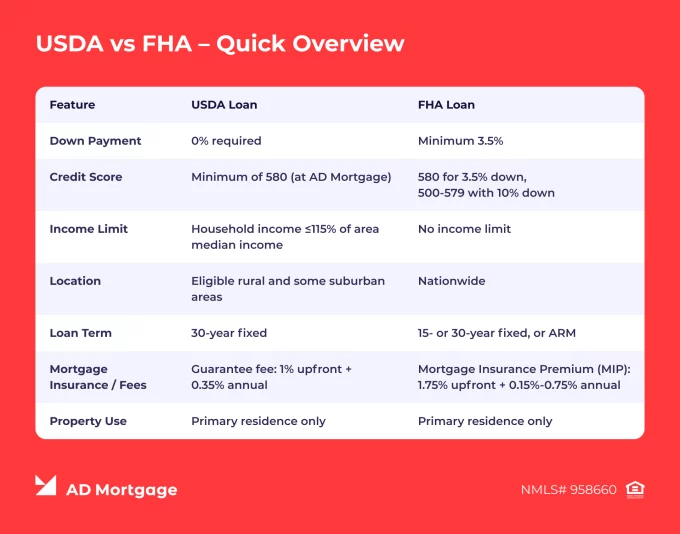
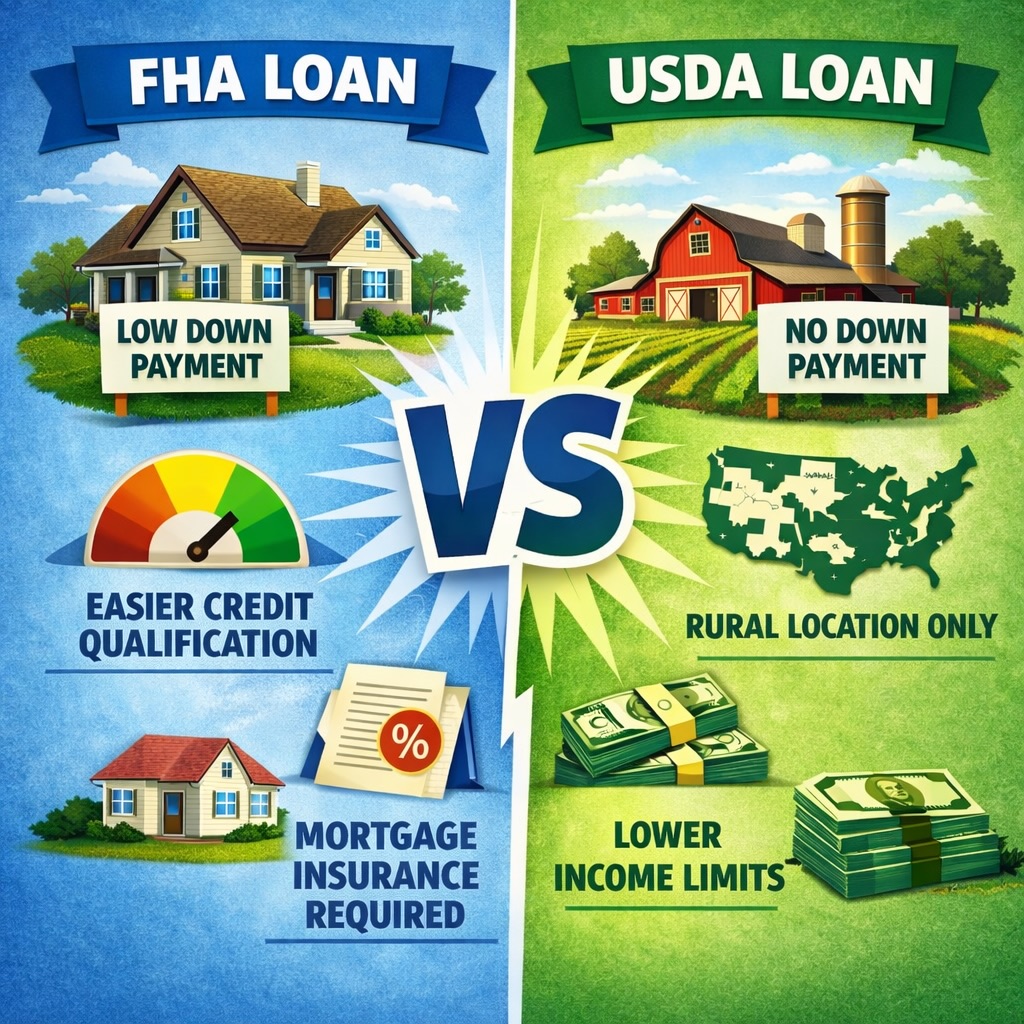
I spent years running underwriting files for conventional, FHA, and USDA loans, and I keep seeing people compare these two programs like they're identical when they aren't even close. They share some surface similarities, sure, but they diverge on eligibility, costs, geographic restrictions, and income caps in ways that completely change the math on a loan application. Let me break down what actually happens when you pick one over the other. FHA loans are backed by the Federal Housing Administration, which is part of HUD. They're designed for borrowers who might not qualify for conventional financing because of lower credit scores or smaller down payments. You need at least 3.5% down with a credit score of 580 or higher. Below 580, you're looking at 10% down. The mortgage insurance premium runs 0.55% annually on top of your principal and interest payment, and it stays for the life of the loan if you put less than 10% down. That's a critical detail most people gloss over. USDA loans come from the US Department of Agriculture. They offer 100% financing, meaning zero down payment. That sounds ideal, and sometimes it is. But the income limits are strict. You can't just be a first-time homebuyer and qualify. Your household income has to fall below a certain threshold for your county. In rural areas, that threshold is often around 115% of the area median income. The tricky part is that USDA defines "rural" loosely. Some suburbs within an hour of a major city still qualify, while others immediately adjacent don't. I once had a client who thought she was buying in a USDA zone because the nearest town was ten miles away, but the property was just outside the designated rural boundary. She had to switch to FHA at closing and eat the higher closing costs.
The Real Cost Breakdown
FHA upfront mortgage insurance premium is 1.75% of the loan amount. That gets rolled into your loan balance. Then you pay an annual MIP of 0.55%, split into monthly installments. On a $250,000 loan, that's about $115 per month in MIP. It never goes away unless you put at least 10% down, in which case it drops off after eleven years. USDA charges a guarantee fee of 1% upfront and an annual fee of 0.35%. Both get financed into the loan. So on that same $250,000 loan, your annual fee is roughly $875, or about $73 a month. USDA is cheaper on ongoing costs. But the catch is the upfront guarantee fee applies regardless of how much money you bring to the table, since there's no down payment to speak of. I calculated a real scenario last year for a client comparing the two on a $300,000 purchase in an eligible USDA zone. FHA came to about $1,293 per year in MIP. USDA came to $1,050. The difference is roughly $21 per month. Not huge, but over a thirty-year term, it compounds to something real. However, USDA has a stricter debt-to-income calculation. They count housing expenses plus all recurring debts, and they don't allow as much flexibility in how they treat variable income. If you're self-employed, this is where USDA gets finicky fast.
Where USDA Actually Falls Apart
The biggest frustration with USDA is the appraisal process. It takes longer than FHA, sometimes significantly longer. A standard USDA appraisal can take three to six weeks. FHA appraisals usually move in one to two weeks. If you're on a tight timeline with a seller who needs to close quickly, USDA is a liability. The appraisal has to meet both the property condition standards of a conventional appraisal AND USDA's specific habitability requirements, which include things like handrail height, minimum ceiling height, and functional utilities. I've seen appraisals fail on a tripped GFCI outlet near a kitchen sink. The appraiser didn't care about the rest of the house. They just marked it as not livable until it was fixed. There's also the income recalculation issue. USDA requires you to document every source of income for the last two years. Child support, alimony, overtime, bonuses, side income. They verify it through tax returns and pay stubs. FHA doesn't ask for the same level of income verification. If you have unusual income patterns, USDA can delay your closing by weeks while they hunt for documentation. I had a case where a borrower's income dropped 12% due to a changed commission structure mid-application, and the entire file had to be re-evaluated. That added twenty-two business days to the closing. The deal almost fell apart.
Get the Full Details
When FHA Is the Better Choice
If you're buying in a metro area that's not USDA-eligible, FHA is your only government-backed option with low down payment. Conventional loans require 3% down and generally 620 credit score minimums, but PMI on conventional is cheaper than FHA MIP if you put 20% or more down. At 5-10% down, FHA beats conventional on monthly cost because the MIP rate is lower than most conventional PMI rates for that LTV range. I recently ran the numbers on a $220,000 condo purchase with a 5% down payment. FHA total monthly P&I plus MIP came to $1,547. A conventional loan at the same LTV had PMI of 0.85% annually, bringing the total to $1,521. The gap was negligible, and the conventional loan closed four days faster because there was no FHA case number to assign and no FHA appraisal requirements. For a condo, FHA has an additional hurdle: the entire condominium project must be FHA-approved. USDA doesn't have that requirement, which is an advantage in some markets, but many newer developments aren't on the FHA approved list. You can get stuck waiting for a variance that never comes through.
Property Eligibility Quirks
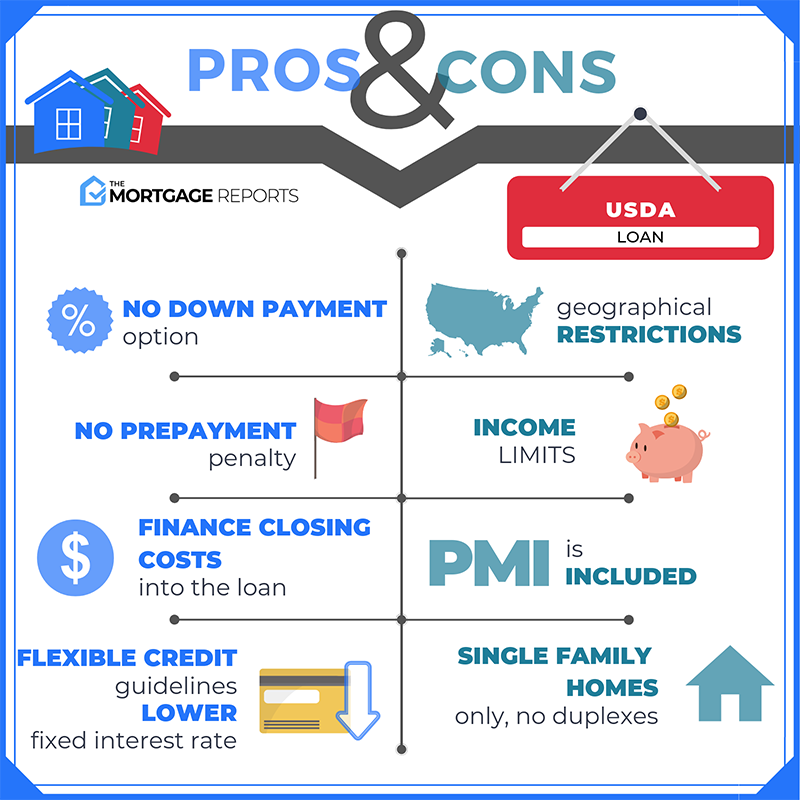
USDA properties must be in designated rural areas. You can check eligibility through the USDA website, but the maps are outdated more often than you'd think. I've had multiple instances where the online map showed a property as eligible, the underwriter later confirmed it, and then the appraisal came back and the system flagged it as ineligible. This happens because USDA occasionally re-zones areas, and the automated systems don't always sync in real time. Always double-check with the local USDA office before you get too far into the process. It saves a week of wasted effort. Another thing nobody tells you about USDA: the loan limit is based on county, not on the property value. In most counties, the maximum USDA loan amount is $339,900. In high-cost counties, it can go up to $225,350 or lower depending on the area. Wait, that's backwards. High-cost counties have higher limits. The national floor is $339,900, but some counties can go up to $825,000 or more. If you're buying a $400,000 home in a low-cost county, you can't use USDA for the full amount. You'd need a combo loan. I've seen this mess up deals where the buyer assumed USDA covered anything under a certain price point. It doesn't work that way.
The Credit Score Reality
FHA is more forgiving on credit. A score of 580 gets you the 3.5% down payment tier. USDA typically wants 640 as a minimum for automated underwriting approval. Below that, you need manual underwriting, which means more documentation and longer processing times. There's no hard minimum for either program from a regulatory standpoint, but lenders set their own overlays. Most FHA lenders will go down to 560 with a 10% down payment. USDA lenders rarely go below 620 because the manual underwriting adds so much complexity to the file. If you have a credit score in the 620s and you're thinking about USDA, ask your lender directly whether they do manual underwriting for USDA. Many won't. I've recommended FHA in those cases because the path forward is clearer and faster. The slightly higher MIP cost is worth the speed. You lose maybe $20 a month but you close in forty-five days instead of seventy-five.

A Note on Refinancing
USDA has a straightforward refinance option called the Streamline Refi, which only requires a credit check and no new appraisal. It can lower your rate and potentially reduce your monthly payment by $30 to $60. FHA has a similar program called the FHA Streamline, but it requires a net tangible benefit analysis and often a credit check that can bump your rate if your score has improved. Neither program lets you pull cash out through a streamline refi. If you want to access equity, you need a cash-out refi, which both programs allow but with stricter qualification standards than the original loan. The bottom line is this: USDA gives you zero down and lower ongoing costs but demands you live in a specific zone, pass stricter income tests, and wait longer for your appraisal. FHA gives you more flexibility on location and credit, moves faster, but costs more over the life of the loan. Pick the one that fits your actual situation instead of picking based on whichever sounds better in a headline. I've seen too many people chase zero down and end up stuck in a longer, more expensive process because they didn't understand the restrictions they were signing up for.