
How the Usda Housing Loan Calculator Actually Works in Practice
Most people treat a Usda Housing Loan Calculator like it will tell them exactly what they can afford. It does not. It is a rough estimate tool, plain and simple. The real value shows up when you understand the inputs behind the numbers, because the standard outputs miss several things that matter a lot once your file goes to an underwriter. A USDA loan is a government-backed mortgage for rural and suburban homebuyers. Zero down payment. Guaranteed by the USDA Rural Development program. The calculator takes your income, the home price, your existing debt, and your interest rate, then spits out a monthly payment estimate. That is the surface-level version. Here is what most calculators leave out. They do not account for the annual fee, which is currently 0.25% of the loan amount divided into twelve monthly charges. They usually skip the eligibility income limits, which vary by county. They also do not factor in the geographic area adjustment, because USDA loans have different maximum loan amounts depending on whether you are in a low-, middle-, or high-cost rural area. If you only look at the monthly payment number, you are going to get blindsided later.
I ran into a specific issue last year that illustrates this. A client brought me a calculator printout showing she qualified for a $280,000 home in a particular Mississippi county. The calculator said her debt-to-income ratio was clean. It turned out the county had a very low USDA income limit, and her household income was $3,000 over the threshold. She had been approved for a totally nonexistent loan amount. The workaround was simple but annoying. I pulled the USDA income eligibility lookup tool directly from the USDA website, entered the property address, and verified both the income limit and the maximum claim amount for that specific county before we ever looked at houses. This took maybe twenty minutes and saved us three weeks of wasted time.
What the Calculator Gets Right and What It Misses
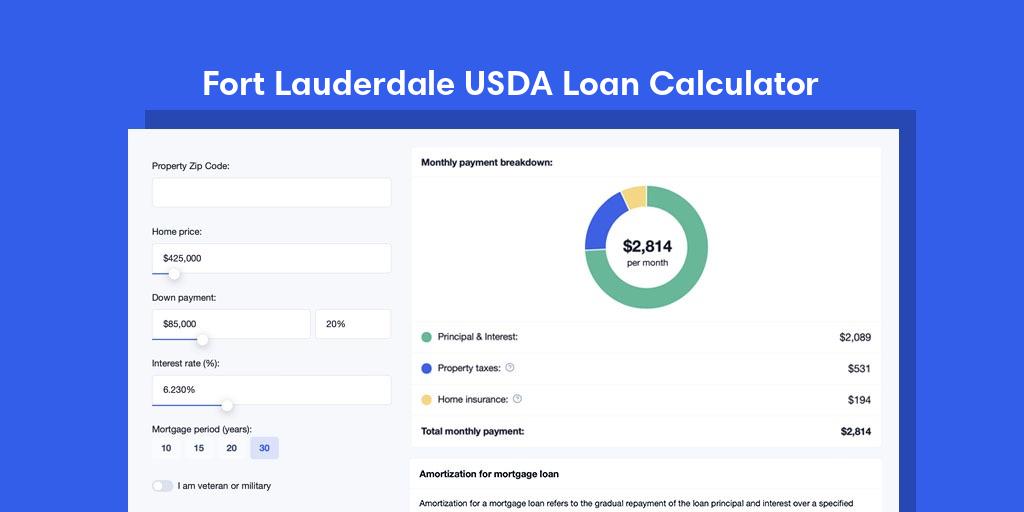
The main strength of any USDA loan calculator is the monthly payment breakdown. It combines principal, interest, property taxes, homeowner's insurance, and the USDA annual fee into one monthly figure. That gives you a realistic sense of the total housing payment, not just the mortgage portion. A lot of conventional loan calculators show only principal and interest, which makes the payment look significantly smaller than it actually is. Another thing calculators handle reasonably well is the front-end and back-end ratio check. USDA typically requires a front-end ratio around 29% and a back-end ratio around 41%. Some lenders stretch these to 33% and 46% with compensating factors. The calculator uses whatever ratio assumptions you feed it, so the output only reflects those assumptions. Where it falls apart is credit adjustments. A calculator assumes a single interest rate based on the credit score you enter. It does not account for the fact that your actual rate could shift significantly depending on your credit profile, the lender's overlay requirements, or even the specific USDA product your lender offers. I had a case where two different lenders gave the same borrower the exact same calculator output, but their actual rates differed by 0.375%. That difference added nearly $90 a month to the payment over thirty years. The calculator cannot tell you that. Only a rate quote from a lender can.
Get the Full Details
There is also the issue of guaranteed versus direct loans. Most people applying for a USDA loan end up with a guaranteed loan, which is insured by private lenders and backed by the government. A smaller number of applicants in very rural areas qualify for a direct loan, which comes directly from USDA and has different income thresholds and interest rates set by the agency. A calculator almost never distinguishes between these two paths, and the payment difference can be substantial. Direct loans often carry lower effective rates but have stricter income caps and longer processing timelines.
Countering Common Misconceptions About USDA Calculators
One counter-intuitive thing about USDA loans that nobody warns you about is the property eligibility requirement. Not every house in a rural area qualifies. The property itself has to be in a USDA-approved area. You can check this on the USDA eligibility map, but even if the map says yes, some properties fail the USDA appraisal requirements later. I once worked with a buyer who found a beautiful old farmhouse in rural Alabama that checked every box on the calculator and the eligibility map. The appraiser flagged the roof and the septic system during the USDA-required inspection. The house did not meet minimum property standards. The loan fell through at step four. The calculator never had a checkbox for "does the house pass USDA inspection?" Another overlooked nuance is the occupancy requirement. You have to intend to live in the property as your primary residence. The calculator will happily show you a payment number for an investment property scenario, but that path does not exist under USDA guidelines. There is no workaround. If you try to use a USDA loan for a rental property, the application gets denied regardless of what the calculator showed you.
Practical Walkthrough
Let me show you how to actually use a Usda Housing Loan Calculator without getting the wrong impression from the results. Start by gathering your recent pay stubs, your W-2s from the last two years, and a list of all your recurring debts. Student loans, car payments, credit card minimums, child support, anything that appears on your credit report as a monthly obligation. The calculator uses these numbers to compute your back-end ratio, and inaccurate debt listings are the single most common reason people get a number from the calculator that turns out to be wrong. Enter your gross monthly income before taxes. Include your spouse's income if they are on the application. USDA counts gross income, not take-home pay. Enter the home price you are targeting. Enter your estimated credit score range. Enter the interest rate your lender quoted you, not the rate you saw on a website. Enter your local property tax rate if you know it, or use the national average as a placeholder, but understand the placeholder will skew your results. Enter your estimated annual homeowner's insurance premium divided by twelve. The calculator will return a monthly payment and a maximum loan amount based on the ratio limits you selected. Cross-reference that maximum loan amount against the USDA claim limits for your county. If the calculator says you can buy a $250,000 home but the county maximum claim amount is $210,000, your real ceiling is $210,000, not $250,000. This mismatch happens constantly and ruins a lot of home shopping trips.

When a Calculator Is Not Enough
USDA loans have quirks that no calculator captures. The funding fee can be financed into the loan amount, which changes your loan-to-value calculation and affects your payment in a way most calculators do not reflect accurately. The income verification process is more detailed than conventional loans. USDA requires two full years of employment history, and gaps in employment need explanations. The appraisals are stricter. The processing times are longer. A calculator will tell you your payment on day one. It will not tell you your loan might take sixty to ninety days to close, or that your file could get returned to the lender twice during underwriting because of missing documentation. If you are serious about a USDA loan, use the calculator as a starting point, not a destination. Run the numbers. Get pre-qualified with a lender who actually does USDA loans regularly. Ask them to show you the income eligibility for your target county. Ask them to confirm whether you are looking at a guaranteed or direct loan path. Then go house hunting with a number that actually matches your real situation.


