Understanding the USDA Loan Estimate
The USDA Loan Estimate is the disclosure document lenders are required to give you within three business days of submitting a mortgage application. It replaced the old Good Faith Estimate and Truth in Lending disclosure back in 2015 under the TILA-RESPA integrated disclosure rule. The form breaks down your loan terms, projected monthly payment, closing costs, and cash needed to close. For USDA loans specifically, there are additional lines and calculations that differ from conventional or FHA estimates, mostly around the guarantee fee and the rural eligibility requirements. I spend more time than I care to admit sorting through these documents, and I can tell you that most people sign off on them without really reading past the numbers. That is a mistake. The format looks standardized, but the details underneath tell a very different story depending on which lender you are dealing with.
How to Get Your USDA Loan Estimate
You need to submit a mortgage application first. The lender then has three business days to deliver the Loan Estimate. This applies whether you apply online, over the phone, or in person. The clock starts when the lender receives six specific pieces of information: your name, your income, your approximate property value, the property address, the loan amount you want, and your estimated monthly expenses. Submit all six at once and you will get the estimate faster. Submit them in dribs and drabs and the lender will delay as long as they legally can. Here is where things get interesting with USDA loans. The property must be in an eligible rural area. If your lender runs the eligibility check after generating the estimate, you could end up with a Loan Estimate for a property that does not qualify. I dealt with this exact situation last year with a client who had already moved her deposit into escrow. The USDA eligibility checker showed her county was partially ineligible — the house sat just outside the boundary line. The Loan Estimate she received was completely valid on paper but useless for her actual purchase. We had to restart the process with a different property and she lost five days she could not afford to lose. The workaround is straightforward. Have your lender run the USDA eligibility verification before anything else. Most lenders use the USDA's online eligibility locator or a third-party service like Eligibility Express. Do not skip this step. A single verification check takes about ten minutes and prevents an entire cascade of wasted time later.
What the USDA Loan Estimate Looks Like Differently
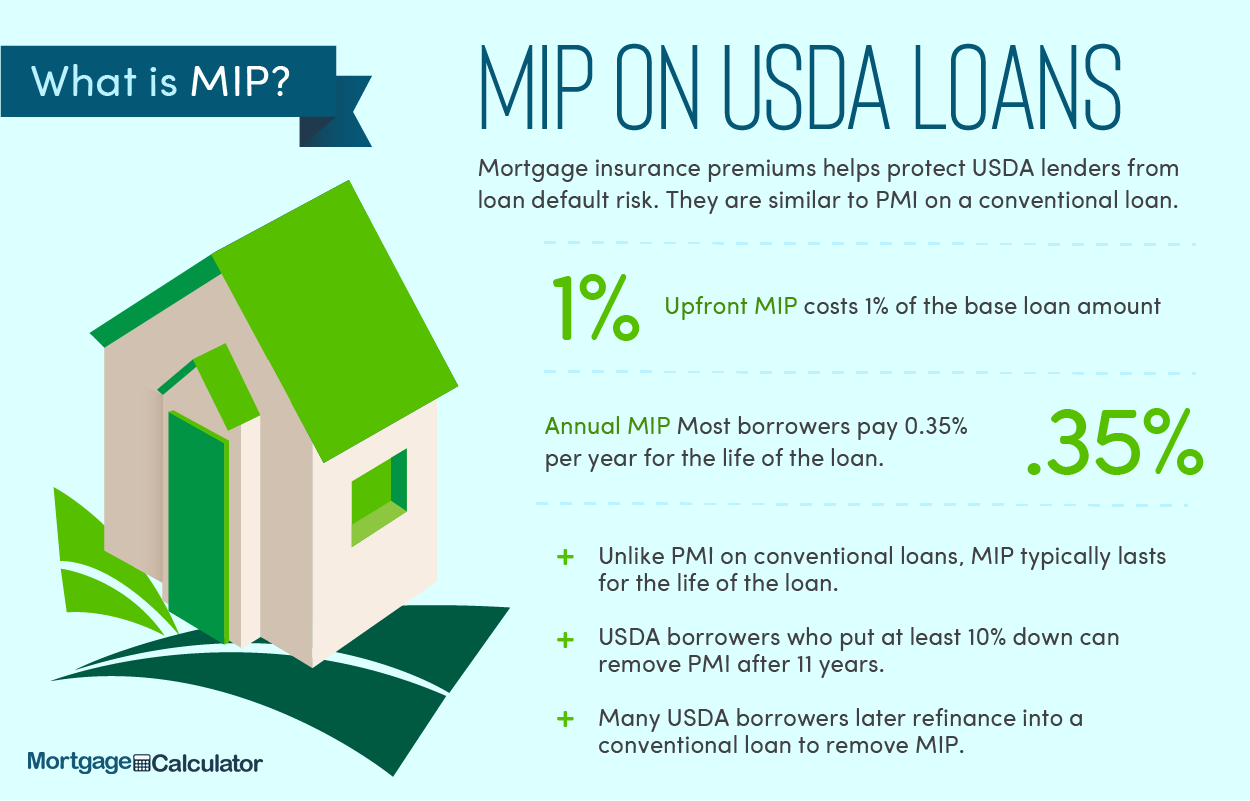
The Loan Estimate is a ten-page standardized form. Pages one and two cover the loan terms, projected payments, and costs. Page three details closing cost breakdowns. The rest are footnotes and disclosures. With a USDA loan, you will see a few specific differences worth noting. The front-end fee is different from a conventional loan. USDA charges an upfront guarantee fee of 1 percent of the loan amount, which can be financed into the loan balance. This shows up on page two under "Other costs" and page three under "Closing costs." Then there is the annual fee, roughly 0.35 percent of the loan balance, which gets split across twelve months on page one. Some lenders forget to explain this properly, and borrowers end up confused about why their monthly payment includes something called a "rural assistance fee." The interest rate section is standard, but USDA loans often have slightly lower rates than conventional loans because the government backing reduces lender risk. This means the comparison shopping matters less on rate alone and more on fees and service charges. Two lenders quoting the same rate can still have a $2,000 difference in closing costs on a USDA loan.
Get the Full Details

Page three is where the real negotiation happens. The lender must itemize every charge as either a lender charge or a third-party charge. You can shop certain third-party services yourself, like title insurance and home inspection. The form has a specific section for this on page three, labeled "Services You Can Shop For." Fill that out if you already have a title company you trust. It takes about five minutes and can save you hundreds of dollars.
Common Pitfalls That Cost Money
The most frequent issue I see is the appraised value coming in below the purchase price. USDA loans have strict appraisal requirements because the property must meet both a market value assessment and a municipal warranty inspection. If the appraisal comes in low, the Loan Estimate numbers become wrong. The lender has to issue a revised estimate, which resets the three-business-day clock. Your original Loan Estimate becomes void. This delays everything by at least a week. Another pitfall is the debt-to-income calculation. USDA uses a two-pronged DTI test. Your total DTI must stay below 41 percent, but your housing expense alone cannot exceed 29 percent of gross income. Some lenders calculate this incorrectly on the Loan Estimate, showing a number that looks fine on the surface but fails the second test. I recently caught this on a file where the lender had included a homeowner's association fee in the housing expense but then double-counted it in the monthly debt section. The estimate looked clean but the actual underwriting review caught the error and caused a two-week delay. Always spot-check the numbers yourself before accepting the estimate at face value. Income documentation is the third area where things go sideways. USDA requires two years of employment history and verification of all income sources. If you are self-employed, the Loan Estimate process can take longer because the lender needs to pull tax returns and calculate adjusted gross income with add-backs. Some lenders try to work around this by using a simpler income calculation on the estimate and then renegotiating later. That is risky. Stick with lenders who do it right the first time.
When the USDA Loan Estimate Is Not Enough
The Loan Estimate is an estimate, not a commitment. It does not guarantee that you will get the loan. The actual underwriting review can produce changes. The Conditional Approval stage comes later, and that is when any remaining issues surface. Think of the Loan Estimate as a budget, not a contract. There are also situations where the USDA Loan Estimate process completely breaks down. If you are buying a manufactured home, the valuation and eligibility rules differ significantly. Standard Loan Estimate templates do not handle this well. You need a lender who specifically understands USDA manufactured housing loans. Similarly, if the property is on land larger than one acre, the USDA program may not apply at all. Some borrowers are surprised to learn this after receiving a Loan Estimate. The maximum lot size for a standard USDA single-family loan is typically one acre within the eligible area. Larger parcels require a different program or may not qualify. If you are working with a contractor who wants to include renovation costs, a standard Loan Estimate will not capture that. You would need a USDA 203(k) rehabilitation loan, which has a completely different estimation process. Most lenders do not handle this hybrid well, and the estimates tend to be inaccurate until you get into the formal approval phase.
The bottom line is that the document itself is standardized, but the accuracy depends entirely on the lender's experience with USDA loans. Not all mortgage companies understand the nuances of the Rural Development program. Ask around. Check reviews. Verify that the person preparing your estimate has actually closed a USDA loan in the last six months. It makes a measurable difference in how smooth the rest of the process goes.