Understanding the USDA Mortgage Payment Calculator
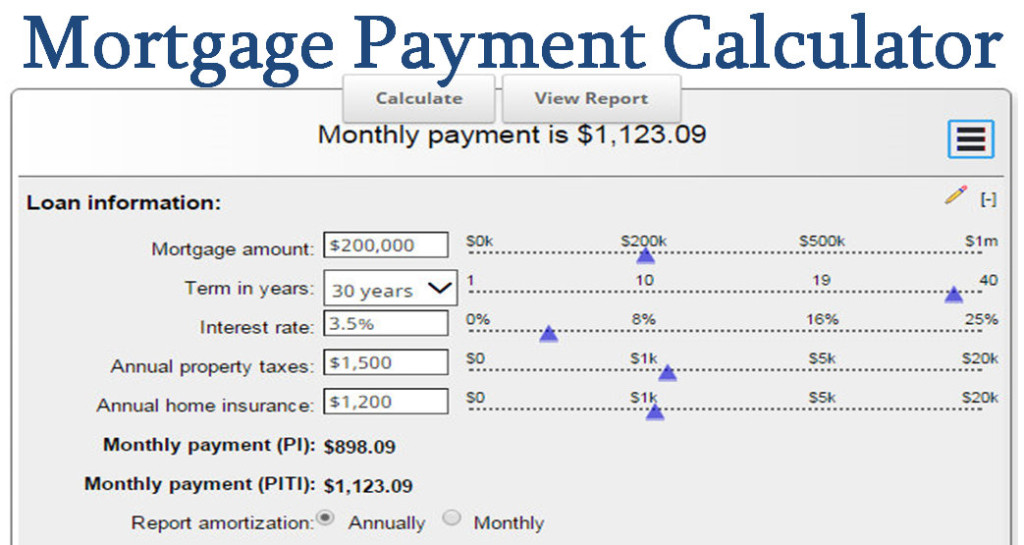
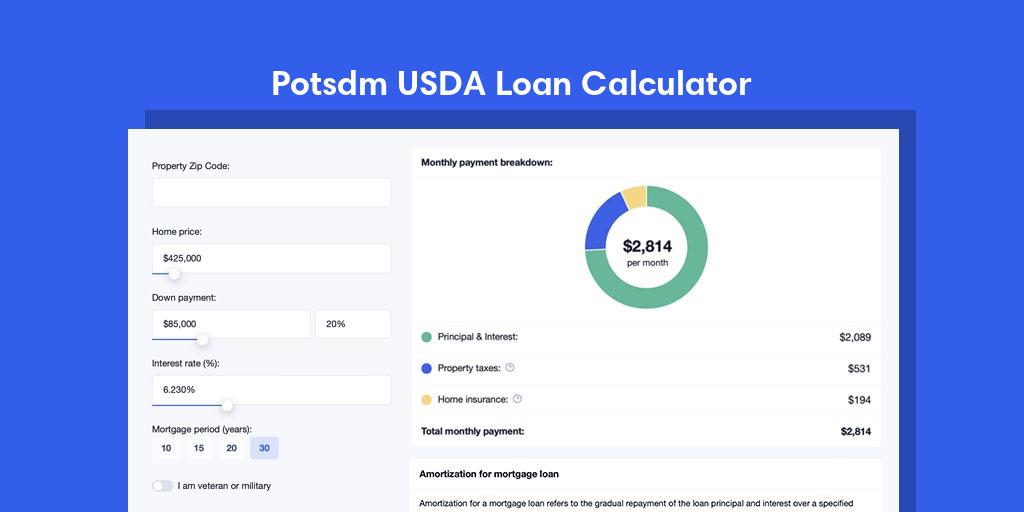
Most people assume a mortgage payment is just principal and interest. It isn't. Property taxes, homeowners insurance, and mortgage insurance premiums all get bundled into the monthly PITI figure, and that makes the real payment significantly higher than what most buyers expect when they first start looking. The USDA program has its own quirks that throw off standard calculations, which is why a dedicated calculator matters more here than it does for conventional loans. Enter your gross annual income first. That number determines whether you even qualify, since USDA has strict income limits based on household size and location. Enter the home price, your down payment amount, the interest rate, and the loan term. A standard 30-year fixed is the most common option, but 15-year terms are available too. The calculator will pull estimates for property taxes and homeowners insurance based on the county you're in, then add the USDA guarantee fee. You'll see two numbers: the front-end ratio, which is your total housing payment divided by your gross monthly income, and the back-end ratio, which folds in car payments, credit cards, and other debts. Both have to stay below USDA's typical 29% and 41% thresholds respectively. I worked with a client last year who used an online calculator and saw a monthly payment of $1,240, which looked perfectly affordable. When we ran the actual numbers through the USDA eligibility system, the guarantee fee calculation was different because the tool he used didn't account for the upfront financing of the fee into the loan balance. The real payment came out to $1,387. That extra $147 pushed his back-end ratio over 41%, and he had to reduce his purchase price by about eighteen thousand dollars to qualify. The difference came from a single calculation method that most free calculators gloss over.
The Reality Behind USDA Guarantee Fees
The USDA charges two separate fees that most calculators don't make obvious enough. There's an upfront guarantee fee of 1% of the loan amount, and an annual fee of 0.35% billed monthly. Here's the part nobody explains well: you can finance the upfront 1% fee into your loan, which means you're paying interest on that fee over the life of the loan. Some calculators show you the annual fee correctly but bury the fact that financing the upfront fee increases your total loan balance, which increases your monthly payment further. It's a compounding effect that matters more on larger loan amounts. I've seen people walk away from USDA loans because their calculated payment looked fine until someone reminded them that the annual fee never goes away. Unlike PMI on conventional loans, the USDA annual fee stays for the entire loan term no matter how much equity you build. That's a permanent cost increase that reduces your effective borrowing power. If you plan to sell within five years, the annual fee still hits every month, which changes your break-even analysis considerably compared to a conventional loan where PMI drops off once you hit 20% equity.
Common Pitfalls That Break These Calculations
Region matters enormously, and not just for income limits. Property tax rates vary by county within USDA-eligible areas, and a calculator using state averages instead of your specific township can be off by hundreds of dollars per month. I had a borrower in rural Georgia whose estimated payment dropped by $210 per month when we switched from a state-average tax estimate to the actual county millage rate. That change alone made the difference between qualification and denial. Another issue is how some calculators handle the debt-to-income ratio. They'll let you input debts but won't flag that USDA has specific rules about which debts count. Chapter 7 bankruptcy remains on your DTI for three years after discharge. Student loans in forbearance still count at whatever the programmed percentage of the balance is, usually 0.5% to 1%. Auto leases get counted fully. If your calculator doesn't follow these USDA-specific rules, the DTI number it gives you is essentially decorative. The biggest limitation I keep running into is that most free USDA calculators don't factor in rural development grants or state-level homeowner assistance programs that can offset the upfront guarantee fee. In some states, local housing authorities will cover that 1% fee entirely, which drops your monthly payment immediately but won't show up in any generic calculator. You have to know to ask about it separately. If you're in Alabama, Texas, or Arkansas, for example, there are active programs that cover the upfront fee that no online calculator will ever reference.
Get the Full Details

When a Calculator Isn't Enough
A calculator gives you a reasonable estimate, but it cannot replace an official eligibility determination from a USDA-approved lender. The income limits shift annually, the property eligibility is checked against a specific address database, and the lender's underwriting standards may impose overlays that a calculator can't account for. I've seen borrowers who were clearly within the payment ratios on paper get denied because the lender required a minimum credit score of 640 when USDA technically allows lower with manual underwriting. The calculator showed a perfect scenario. The actual underwriting told a different story. If you want a more precise picture, pull your actual property tax statement from the county assessor's office, get a concrete insurance quote from your agent, and run those real numbers through the calculator instead of the estimates it generates. The gap between generic estimates and your actual costs is usually where people get surprised. That habit alone will save you from the most common disappointment with USDA loan planning.