What You Actually Need to Know Before Starting
The User Guide For Investing Walkthrough isn't a single product or a download you can grab from a website. It's a category of documentation — step-by-step instructional content that helps beginners navigate the process of starting to invest. You'll find these guides scattered across brokerage help pages, financial education platforms, and independent blogs. Most of them are competent. Some of them are misleading. I spent about four years managing my own portfolio and helping friends set one up after I got tired of answering the same questions repeatedly. The main thing I learned is that the average guide skips the parts that actually matter — the small friction points where most people get stuck or make mistakes.
User Guide For Investing Walkthrough: What It Covers
A solid walking-through guide typically covers account setup, funding, asset selection, order types, and basic risk management. That's the surface level. The good ones also address tax implications, fee structures, and the difference between active and passive approaches. Most don't go far enough into the second layer, which is where real problems show up. Here's how I approached it when I built my own version. I started with the mechanics — opening a brokerage account, choosing between a traditional IRA and a Roth, funding the account via bank transfer or wire — and then layered in the decisions that actually determine outcomes. Asset allocation comes first. Not stock picking. Allocation.
Account Setup and the Parts Nobody Talks About
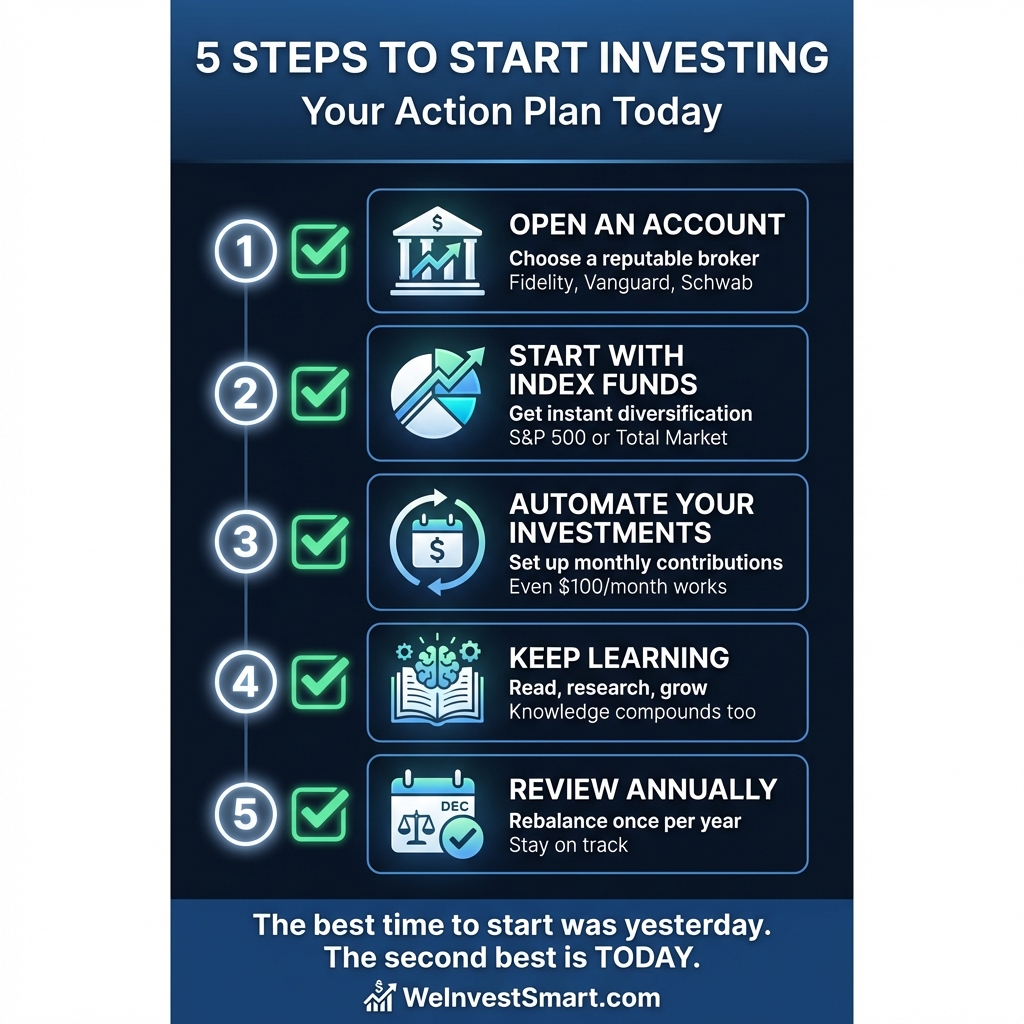
Opening a brokerage account takes about ten minutes if you've never done it. Ten to twenty minutes if you have. The trick is picking the right platform for your situation, not just the one with the flashiest landing page. Fidelity, Schwab, and Vanguard all offer zero-commission trading and solid educational material. For basic index fund investing, any of them works fine. The differences only matter when you're dealing with specific account types or international markets. I ran into a problem a few years ago that still bugs me. A friend opened a brokerage account without specifying whether it was a taxable account or a retirement account. He had no idea the tax treatment would be completely different once he started buying and selling. He ended up in a standard taxable brokerage account when he should have been in a Roth IRA because he was younger and in a lower tax bracket. He couldn't undo the account type after the fact — he had to close it out, potentially triggering tax consequences, and start over. I watched him spend three weeks dealing with customer service and form submissions that should have been unnecessary. The workaround is simple. Before you enter anything, write down what type of account you want and why. Taxable, traditional IRA, Roth IRA, 401(k) rollover. If you can't articulate the reason in one sentence, pause and research before proceeding.
Get the Full Details
Funding the Account: Methods and Timing
Bank transfers are the standard route. Most brokerages process ACH transfers within one to three business days. Wire transfers are faster — same day or next business day — but they often come with fees that eat into small deposits. If you're funding with less than $5,000, a wire transfer might cost you a meaningful percentage upfront. There's a nuance most guides miss. The timing of your deposit relative to market movements matters less than the timing of your first investment relative to your cash position. Keeping large sums uninvested in a brokerage account waiting for the "perfect entry point" is a common trap. Money sitting idle earns nothing while inflation quietly reduces its purchasing power. Don't overthink this. Dollar-cost averaging your initial deposit over two or three weeks is a reasonable compromise between acting immediately and avoiding a bad entry.
Building Your First Portfolio
The simplest portfolio that actually works looks like this: a broad U.S. total market index fund, an international total market index fund, and a total bond market fund. The exact percentages depend on your age, risk tolerance, and time horizon. A common rule of thumb — one hundred minus your age equals your stock percentage — is rough but not terrible as a starting point. It's not a formula. It's a heuristic. The more specific guidance I can give is this: keep expense ratios below 0.10 percent for core holdings. Every basis point above that is money leaving your account every year, compounding against you over decades. A 0.03 percent expense ratio on a $10,000 investment costs three dollars annually. A 0.80 percent ratio costs eighty dollars. Over thirty years at a 7 percent return, that difference becomes roughly $6,000 to $8,000 depending on exactly how you calculate it. I once managed a portfolio for someone who kept adding individual stocks to their "core" allocation. Each stock came with a higher expense ratio when you factored in the implicit costs of research time and trading friction. The portfolio wasn't outperforming the index. It was underperforming by about 1.2 percent per year after all costs. That person needed a User Guide For Investing Walkthrough that explained why simple index funds exist, not one that taught them how to pick stocks.
Order Types and What Happens When You Mess Up
Market orders execute immediately at the current price. Limit orders execute only at your specified price or better. Most beginners use market orders because they want to get in fast. That's usually fine for large-cap stocks and ETFs with tight spreads. It's dangerous for smaller, less liquid positions where the spread between bid and ask can be several percent. I made an order mistake once — entered a market buy instead of a limit buy on a mid-cap ETF during a period of elevated volatility. The fill price was about 4 percent higher than the quoted price. Not catastrophic, but entirely preventable. Now I use limit orders for everything except the most liquid instruments, and I set the limit within 0.5 percent of the current price. It rarely causes a missed trade, and it eliminates surprise fills.
Common Pitfalls That Ruin Returns
The first pitfall is fee blindness. Trading commissions may be zero, but spreads, management fees, and tax drag add up. Track your total cost as a percentage of assets under management. If it's above 0.50 percent per year across your entire portfolio, something is wrong. The second pitfall is behavior. Investors who check their portfolios daily and react to short-term movement consistently underperform those who check quarterly or annually. This isn't theoretical. It's been measured repeatedly. The act of checking creates an urge to act, and acting in response to noise destroys returns. The third pitfall is tax inefficiency. Holding internationally developed market funds in taxable accounts instead of tax-advantaged accounts can create unnecessary complexity and potential withholding issues. Some foreign dividends face double taxation depending on your country and treaty agreements. Put those holdings in an IRA where they grow tax-deferred.
When the Guide Doesn't Apply
Standard investing walkthroughs assume you have a stable income, an emergency fund, and no high-interest debt. None of that is mentioned because it seems obvious to the writer, but it's not obvious to everyone. If you're carrying credit card debt at 20 percent interest, investing before paying that off is mathematically irrational. No guide will tell you this because it's not part of the investing framework — it's a prerequisite. Similarly, if you're within five years of needing the money for a specific purpose — a house down payment, a child's tuition, a major medical expense — a standard long-term investing approach is inappropriate. That money belongs in a high-yield savings account or a short-term CD, not in equities. The guide won't warn you about this unless you ask the right questions.
What to Do After You Finish the Walkthrough
Most people treat the end of a guide as the finish line. It's not. The actual work begins after you've set everything up. Rebalancing annually, reviewing expense ratios every two years, checking that your asset allocation hasn't drifted more than five percentage points from your target — these are the ongoing tasks that matter. Skipping them doesn't crash your portfolio immediately, but over five or ten years the drift compounds just as much as fees do. I track my allocations using a simple spreadsheet. Columns for each fund, current weight, target weight, and the adjustment needed. Takes about fifteen minutes a quarter. The alternative is forgetting about it entirely and discovering two years later that your portfolio has somehow become 80 percent tech stocks because you bought more of what went up without meaning to.