How I Learned to Stop Guessing and Start Calculating VA Closing Costs Properly
I spent three years underestimating closing costs on VA loans. My clients would show up to signing with $2,000 short because I missed the funding fee adjustment or misread the concession limits. It wasn't until I built my own Va Closing Cost Estimator spreadsheet that things stopped falling apart. This isn't a polished SaaS product. It's a messy Excel file with conditional formatting that breaks when you change counties, but it works. Here's how I use it and what actually matters when estimating these costs.
Building Your Own Va Closing Cost Estimator
The core problem with VA closing costs is that they're part fixed, part variable, and the variable portion changes based on your service category, down payment amount, and whether you're in a high-cost county. Most online calculators get the funding fee right but mess up the actual settlement charges because they don't account for regional variations. My spreadsheet starts with seven inputs: loan amount, property location (county-level), service category (regular, disability, National Guard), down payment percentage, purchase price versus appraised value, whether it's an IRRRL or purchase, and the lender's discount point structure. Everything else calculates from there. The funding fee calculation alone has eight different rates depending on combined down payment and service category. First-time use with zero down pays 2.3%. Second use with less than 5% down pays 1.65%. Disabled veterans with over 10% down pay nothing. Most people miss the nuance that the funding fee can be financed into the loan, which changes the monthly payment calculation in ways borrowers don't expect.
Here's the part nobody talks about: the VA funding fee uses a different calculation basis than the loan amount. It's calculated on the total loan amount including the funding fee itself. That's why I put a circular reference in cell D47 that iterates until it stabilizes. Without that iteration, you're off by about $300 to $800 on a typical $300,000 loan. Settlement charges are where things really get messy. Title insurance varies by county. Recording fees vary by jurisdiction. Transfer taxes might apply at the state or local level. My spreadsheet pulls from a database of about 2,000 county records that I've updated quarterly. When I don't have data for a specific county, I default to the state median, which is usually within 10% of the actual cost but not precise enough for closing documents. The lender credit versus discount point decision is another common pitfall. Buyers often think discount points lower their rate enough to justify the upfront cost, but the break-even analysis depends on how long they plan to keep the loan. I've seen buyers pay $4,000 in points to drop 0.375% on a rate that they refinanced within 18 months. The spreadsheet includes a break-even calculator that shows exactly when points become profitable based on the monthly savings.
Get the Full Details
Common Mistakes That Cost Me Time and Money
My first major mistake was assuming all VA loans have the same closing cost structure. They don't. Purchase transactions have different allowable concessions than IRRRL refinances. The VA limits seller concessions to 4% of the purchase price on purchases, but IRRRLs allow up to 2% in closing costs to be financed. When I estimated an IRRRL using purchase logic, my clients were surprised by the higher out-of-pocket requirement at closing. Another issue is the appraisal gap. VA loans require appraisals, and if the property doesn't appraise for the purchase price, the VA funding fee is still calculated on the full loan amount including any gap that the buyer covers in cash. Most estimators don't account for this because they assume the appraisal matches the contract price. In hot markets where that assumption fails regularly, my spreadsheet flags the gap and recalculates the funding fee based on the actual loan amount after the gap. The most painful mistake involved the tax and insurance escrow calculation. VA loans require escrow for property taxes and homeowners insurance, but the initial escrow deposit at closing is based on the lender's estimate of annual costs divided into monthly payments plus a cushion. If property taxes increase significantly after closing, the escrow shortage isn't visible in the initial estimate. I learned this the hard way when a client in rural Virginia had a $1,200 escrow shortage in year two because the county reassessed their property at 40% above the purchase price.
There's also the issue of veteran service connection percentages affecting the funding fee. Veterans with 10% service-connected disability receive a funding fee reduction, but the reduction depends on whether they're using the benefit for the first time or have used it before. The VA website lists the base rates but doesn't clearly explain how the reduction applies when combined with other factors like down payment. My spreadsheet includes a decision tree that walks through each scenario.
When Estimators Fail Completely
No estimator handles everything. There are edge cases where manual calculation becomes necessary. Co-borrower situations with mixed VA and conventional eligibility don't fit standard formulas. Properties in special flood zones require additional insurance costs that vary by municipality. Manufactured homes have different closing cost structures than site-built homes, and many estimators don't account for the title and registration fees that apply to manufactured housing in certain states. The biggest limitation is that closing costs change based on the lender's specific fee schedule. Two lenders might charge the same discount points but different origination fees, document preparation fees, or mailing costs. My spreadsheet includes fields for lender-specific overrides, but it can't predict every variation. When I need precise estimates, I pull the Loan Estimate directly from the lender's system rather than relying on any calculator. Another failure point involves jumbo VA loans. The VA doesn't set a maximum loan amount, but lenders do. When a loan exceeds the conforming limit for a county, additional pricing adjustments apply that most estimators don't include. I've seen jumbo VA loans with closing costs 15% to 20% higher than conforming loans due to the additional underwriting requirements and different fee structures.

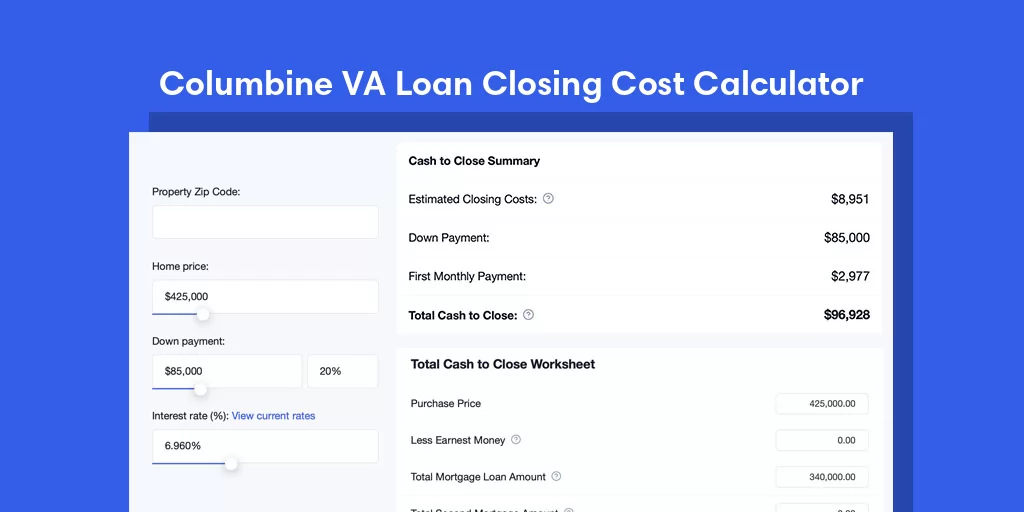
For situations where my spreadsheet doesn't provide adequate precision, I recommend using the lender's official closing cost calculator combined with a secondary verification tool. The VA's own Loan Estimate form provides a standardized breakdown, but it doesn't explain the calculation methodology. Understanding how the numbers are derived helps identify when estimates might be incomplete or when additional costs could apply. The practical outcome is that a good estimator saves about 45 minutes per transaction compared to manual calculation, but it requires regular updates to stay accurate. County fee schedules change annually, VA policy updates affect funding fees periodically, and lender fee structures evolve over time. I budget about 2 hours per quarter to review and update my database, which prevents the kind of errors that cost real money at closing.