Getting the VA Entitlement Calculation Right Without Losing Your Mind
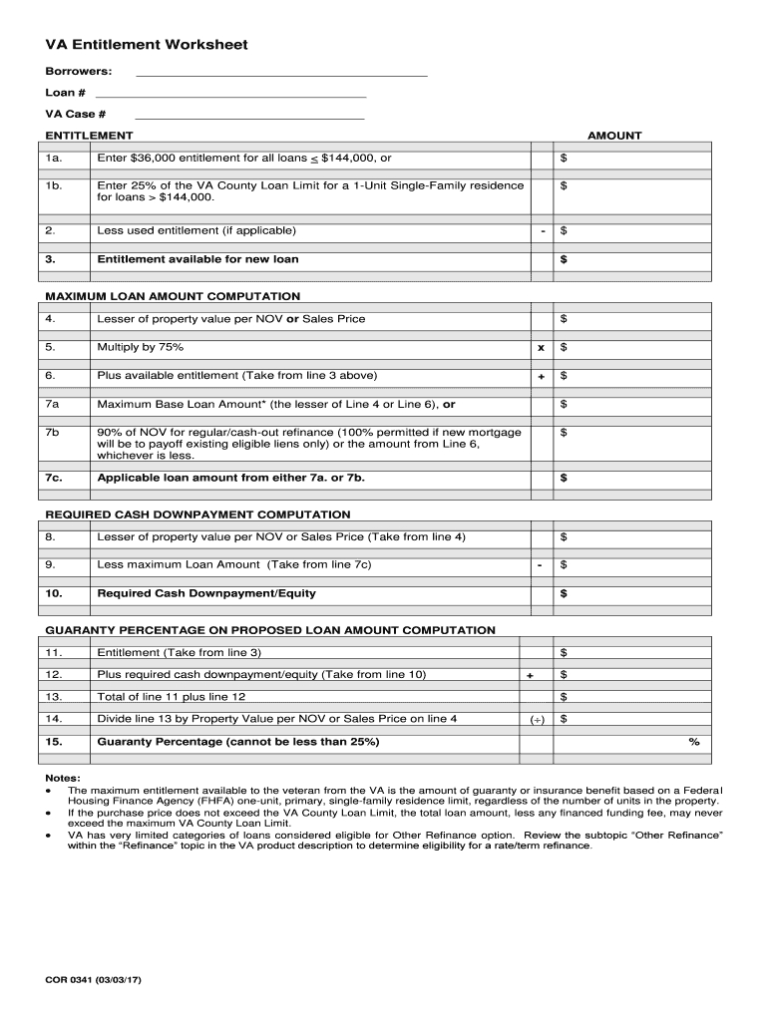
Most people approach VA loan entitlement calculations expecting a simple yes or no answer. It doesn't work that way. The numbers shift depending on county loan limits, whether you've used entitlement before, if you have remaining basic entitlement, and whether the purchase price clears the conforming loan threshold for your area. I've been filling these out for years, and the worksheet still trips people up when they hit the less common edge cases. Start by pulling your Certificate of Eligibility from the VA or your eClosing portal. You need the specific dollar figure listed there, not a guess. The worksheet asks for your purchase price, your down payment (if any), and whether this is a first-use or second-use of entitlement. Input those into the corresponding fields. The formula calculates your effective loan limit minus the purchase price to determine how much entitlement is consumed, then subtracts that from your total available entitlement to show what remains. The result tells you whether you're fully covered or if there's a shortfall requiring additional documentation or a higher down payment. That's the straightforward version. The actual form has a second section for restoration calculations if you've paid off a prior VA loan, which is where things get murky quickly.
I ran into a case recently where a borrower had partially restored their entitlement from a prior VA loan payoff but also carried a balance on a second VA loan they'd refinanced out of. The worksheet's standard layout assumes either a clean restoration or an active concurrent loan, not both scenarios layered together. I had to manually compute the remaining entitlement from the paid-off loan separately, then apply it against the new transaction while cross-referencing the active loan's outstanding balance. Took about twenty minutes of spreadsheet work instead of the five the worksheet promised.
What the Worksheet Misses and Why It Matters
One thing nobody mentions upfront is that the worksheet uses county-level conforming loan limits as its benchmark, but those limits change every January based on FHFA adjustments. If you pull a worksheet from last year's version and the county limit went up, your calculated remaining entitlement will be wrong. I've seen borrowers get flagged at closing because the underwriter pulled a fresh limit and the numbers no longer matched what the worksheet showed. Always verify the current year's conforming limits for your specific county before trusting the output. Another counter-intuitive detail: having a prior VA loan doesn't automatically disqualify you from using full entitlement again. If the prior loan is paid in full and the entitlement has been restored, you can theoretically use your full entitlement once more even while a second VA loan sits on someone else's profile. The worksheet won't always surface this clearly because it treats prior usage as a simple deduction rather than a conditional restoration calculation. The bigger limitation is that the standard worksheet doesn't account for jumbo loan scenarios in high-cost counties. If your purchase price exceeds the conforming limit, the excess entitlement calculation requires manual intervention. The form will show you a number, but that number isn't the final word. The VA uses a separate surplus entitlement process for those transactions, and the worksheet doesn't model it. You'd need to contact the VA directly or run a loan estimate through the VA e-Validation system to get an authoritative figure.
Get the Full Details

There's also the question of funding fees baked into the calculation. The worksheet focuses purely on entitlement availability, not on how the funding fee affects your loan amount. A 2.3 percent funding fee on a $400,000 loan adds roughly $9,200 to the financed amount, which shifts your entitlement consumption slightly. It's a small difference but one that shows up when the numbers are already tight at the edge of a county limit.
Practical Steps Before You Start
Get your COE first. Without the exact entitlement figure, everything else is approximation. Download the current worksheet from a VA-approved source or use the lender's internal version, make sure it's marked with the current year. Verify the conforming loan limit for your county on the FHFA website. Run the numbers twice — once with the worksheet and once as a manual check. If the two outputs diverge by more than a few hundred dollars, something in your inputs is off or you're hitting one of the edge cases the form doesn't handle well. If you're dealing with a partial restoration or a concurrent VA loan situation, the worksheet gives you a starting point. It does not give you the final answer. You'll need to supplement it with a manual calculation or a VA representative's confirmation before you commit to a purchase price. The process usually takes fifteen to thirty minutes for a straightforward first-time use case. Expect an hour or more if your situation involves prior loans, restored entitlement, or a high-cost county jumbo scenario.