How the VA loan payment estimation actually works in practice
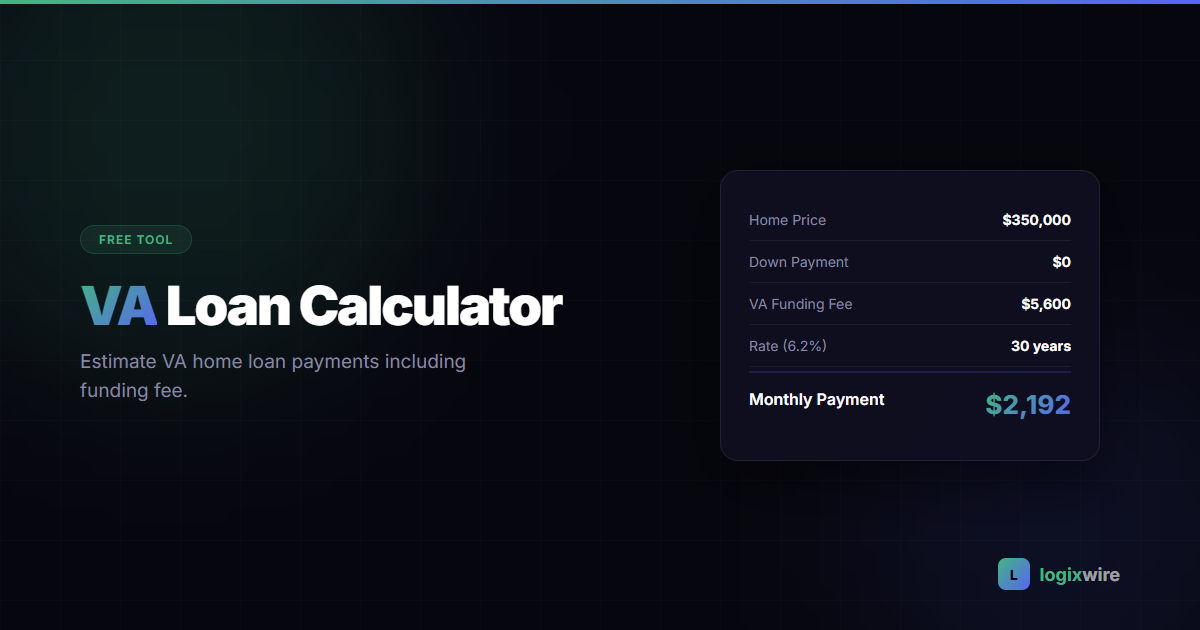
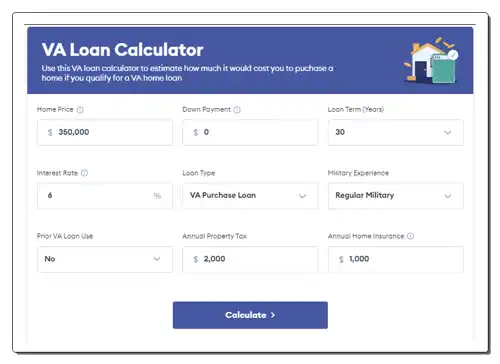
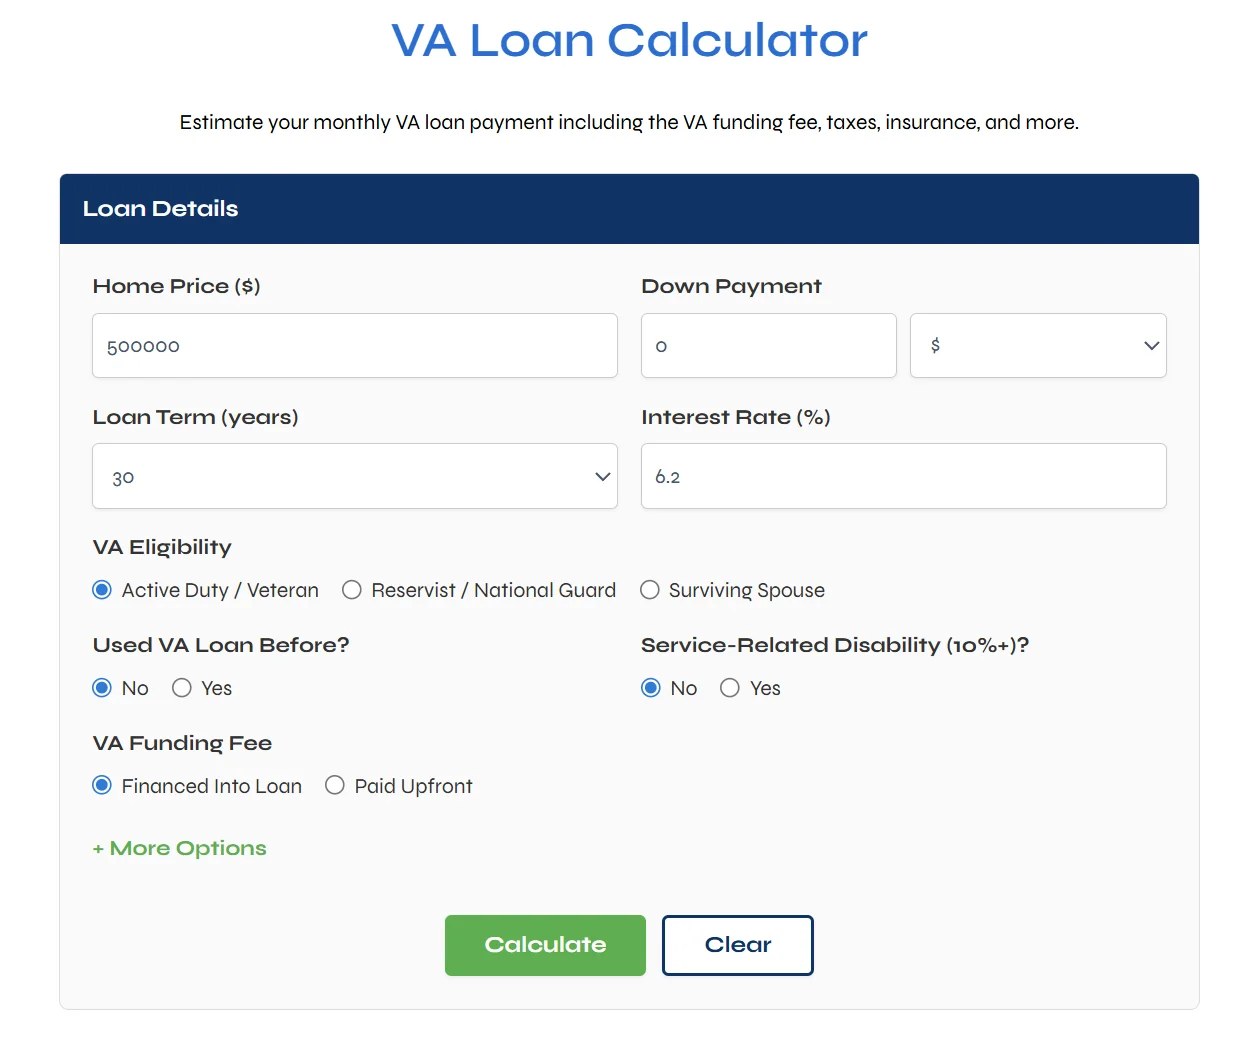
Most people open a Va Home Loan Payment Estimator and type in numbers without realizing how much wiggle room is built into those results. The output you get back is an approximation based on what you enter, not a binding figure from your lender. I've watched borrowers panic over estimates that turned out to be $40 a month off once actual paperwork hit the underwriter's desk. That gap isn't an error in the tool, it's just how estimation works before full documentation. The basic inputs are straightforward. You put in your loan amount, your interest rate, your loan term, and the property tax and insurance estimates for the area. The estimator then calculates your principal and interest portion, adds the monthly escrow components, and gives you a total payment figure. Simple enough on the surface. What most people skip over is the funding fee. For a first-time VA loan with no down payment in 2024, the funding fee sits at 2.3 percent of your loan amount. If you're using the loan for the second time with less than five percent down, it drops to 1.6 percent. If you've used it more than twice, it climbs back up to 2.3 percent again. The funding fee rolls into your loan balance if you don't pay it upfront, which bumps your monthly payment higher than the raw loan amount would suggest.
Using a Va Home Loan Payment Estimator without wasting your time
Start with the VA loan amount minus your down payment if you're putting anything down. The minimum down payment for a VA loan is zero, which is the whole point, but some lenders will still want a down payment if the appraisal comes in under the contract price. That changes everything in your estimate. I had a case last year where a borrower ran their numbers through an estimator showing a $1,850 monthly payment, then the appraisal came in $12,000 low. They either walked away or restructured the deal, and the payment estimate they'd been working from was completely irrelevant by the end. Another thing that trips people up is how they handle the residual income requirement. The VA doesn't use a single debt-to-income cutoff the way conventional loans do. They look at whether your remaining income after expenses covers your basic living costs for your family size and region. A Va Home Loan Payment Estimator won't flag whether you qualify under that standard because it only calculates the payment, not the eligibility. You need to run that separately or have a VA-literate loan officer look at your full picture. I found this out the hard way when a borrower's payment estimate looked perfectly fine at 38 percent of income, but his residual income fell short because he had three dependents in a high-cost region. He got denied anyway despite what the numbers suggested. Interest rate assumptions are another minefield. Most estimators default to whatever rate is trending that day, but your actual rate depends on your credit score, how much equity you have, and which discount points you choose. A 0.5 percent difference in your rate translates to roughly $28 per month on a $250,000 loan over thirty years. The estimator won't tell you that unless you adjust it manually. I usually recommend running three scenarios: your best-case rate, the average market rate, and a conservative rate thirty basis points higher just in case your credit profile isn't as strong as you think.
What these tools don't cover and why that matters
HOA fees aren't included in any standard VA payment estimator. If the property has a homeowners association, that's a real monthly cost sitting on top of your estimated payment. I saw a veteran in Florida who got approved for a townhouse with a $340 monthly HOA fee that his estimator never mentioned. His actual housing payment ended up $340 higher than anything he'd planned around. Mortgage insurance doesn't apply to VA loans, which is the main advantage, but some estimators still show a mortgage insurance line item by default because they're built for conventional loans. Make sure that field is zeroed out before you trust the total. It happens constantly, and it skews the numbers by fifty to two hundred dollars depending on the loan amount. Property taxes vary wildly by county, and many estimators pull from generic national averages rather than your specific tax rate. In Texas, property taxes can add four or five hundred dollars a month to your payment. In states like Hawaii or New Jersey with higher rates, it's even steeper. You need to plug in the actual annual tax amount divided by twelve, not an estimate from a generic calculator. Same goes for homeowners insurance, which ranges from $80 to $250 a month depending on your location and coverage.
Get the Full Details
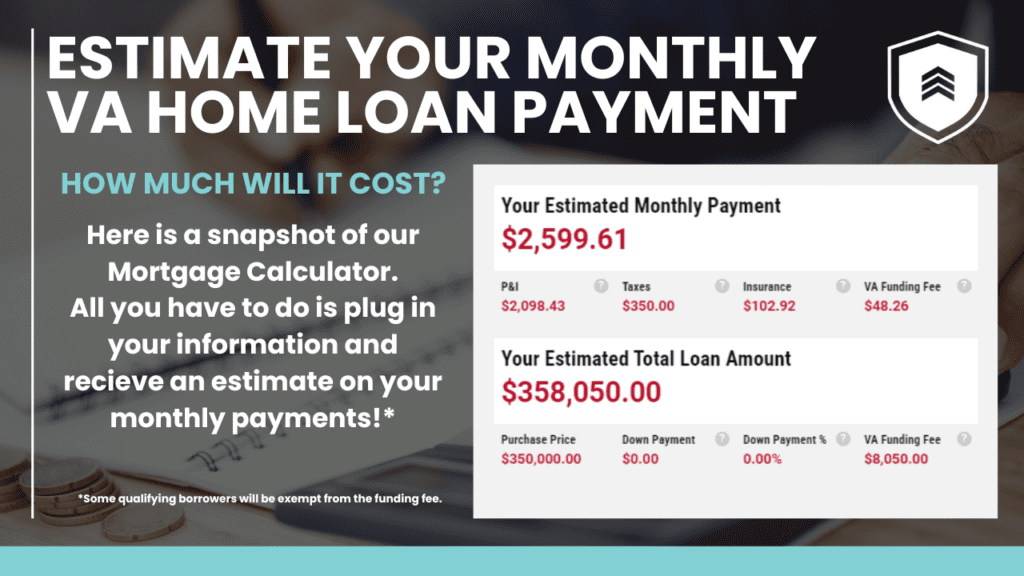
There's also the MERS processing fee, document preparation fees, and various other lender charges that don't show up in a payment estimate at all. Those affect your closing costs, not your monthly payment, but they're part of the real cost of the loan. A good VA-literate loan officer will lay out all of this before you sign anything. An estimator gives you a starting point, not a final answer. I generally tell people to use a Va Home Loan Payment Estimator as a rough screening tool, not a decision-making instrument. Get the ballpark figure, then move to a real estimate from a VA-experienced lender who understands residual income, funding fee structures, and how appraisal gaps can completely rewrite your numbers. That process usually takes about twenty minutes if the loan officer is competent and has the right tools. Anything longer and something's probably getting complicated, which means you should have already done your homework before booking the appointment.