Understanding How VA Loan Amounts Actually Work
The VA loan amount calculation isn't some mysterious process, but it's also not as simple as looking up a number on the VA website and calling it done. I spent years watching loan officers and borrowers get tripped up by this because they assumed the process was linear when it really involves several moving parts that interact in ways most people don't expect. At its core, a VA Loan Amount Calculation Worksheet helps you determine two things simultaneously: your entitlement and your remaining borrowing capacity. The VA doesn't set a hard maximum loan amount for its guaranteed loans. Instead, the limitation comes from what the VA will actually guarantee on your behalf, which is a percentage of your loan relative to county loan limits. That distinction matters more than most people realize.
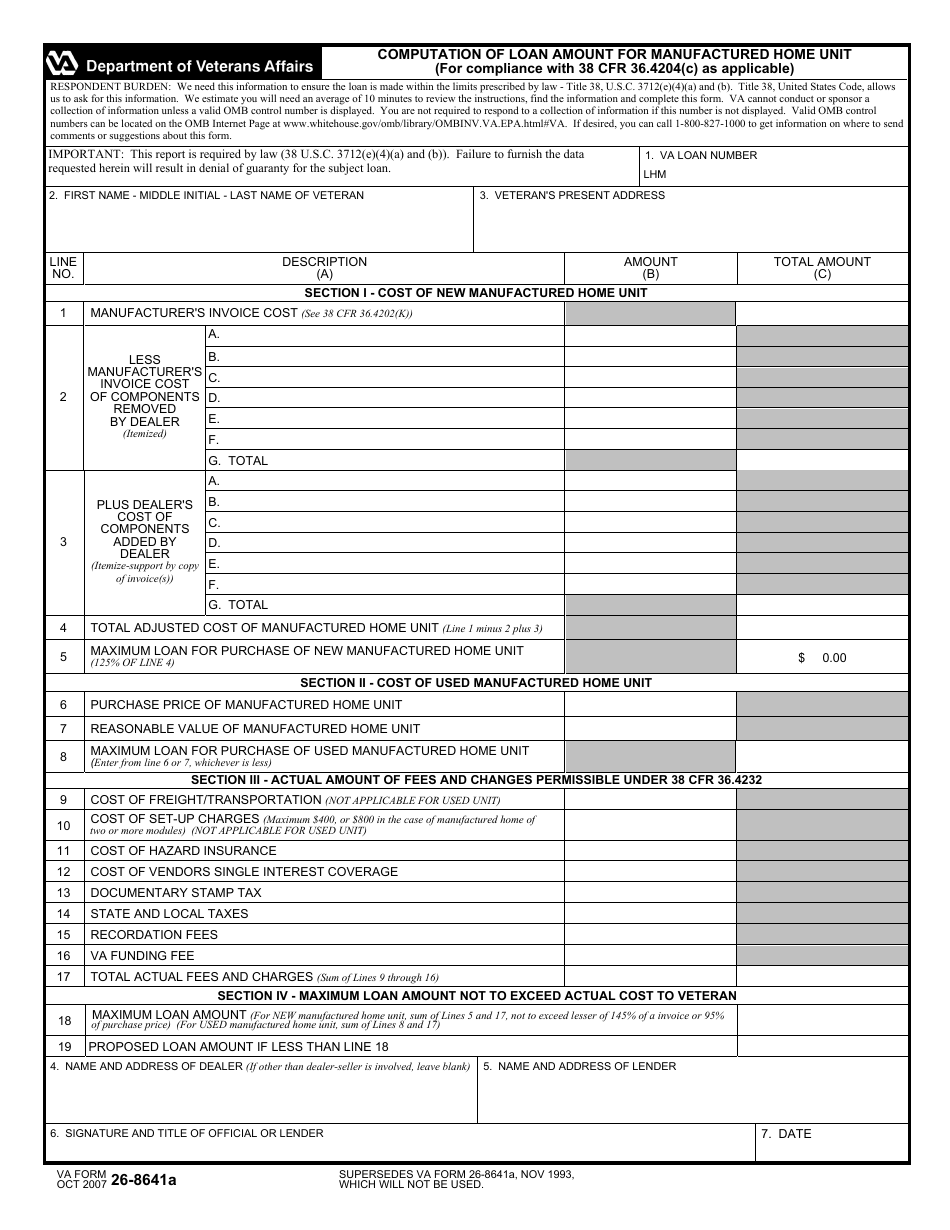
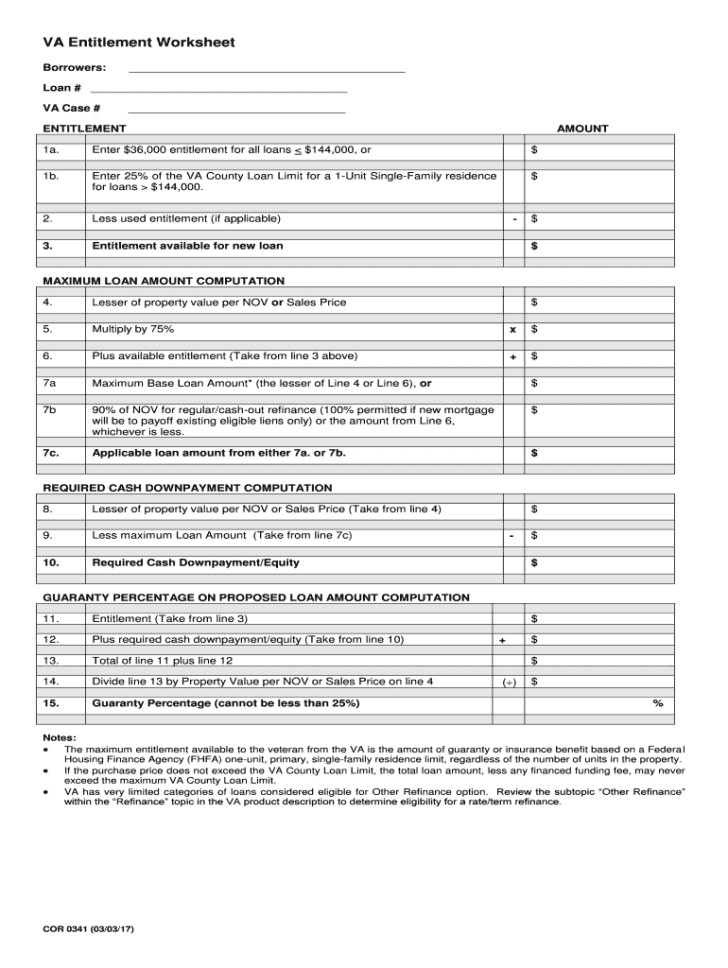
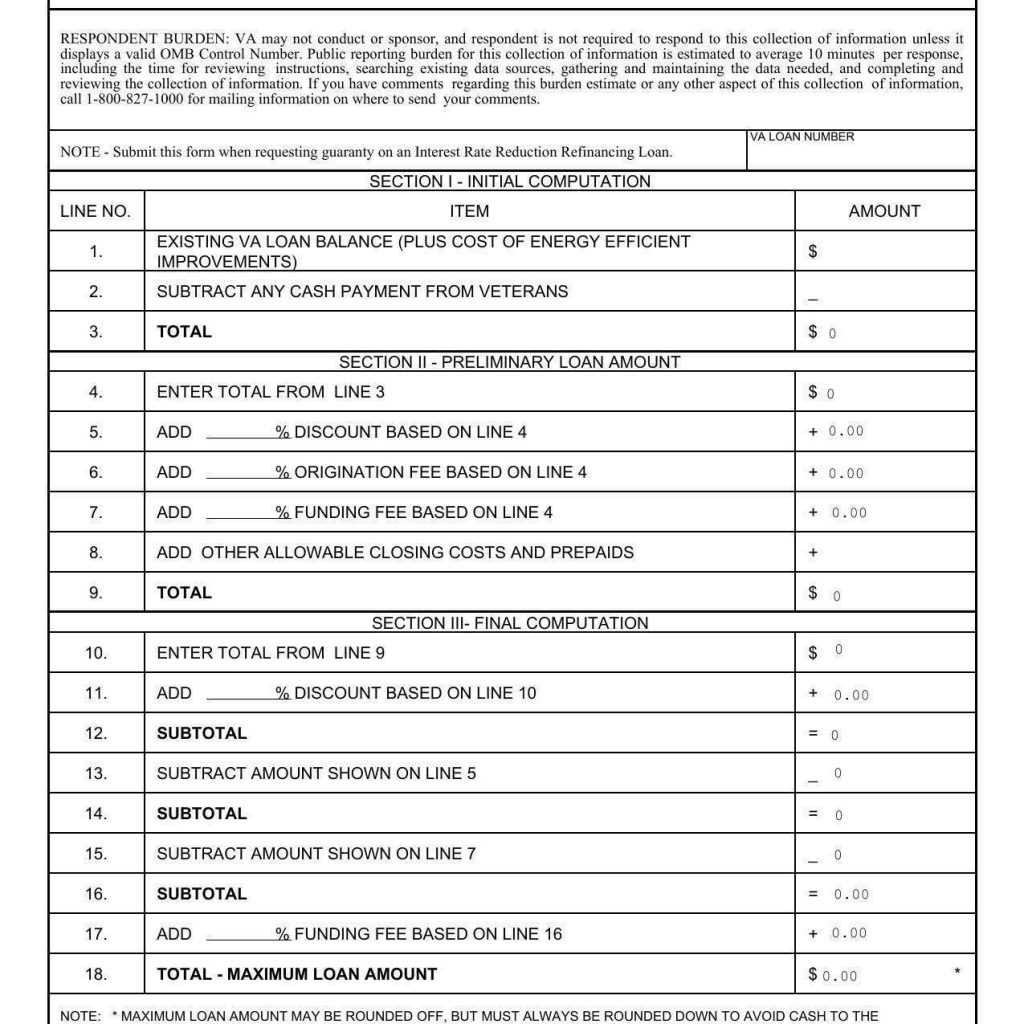
VA Loan Amount Calculation Worksheet
Here's how the calculation actually works in practice. Start with your basic entitlement, which is $36,000 for most veterans. That's the baseline the VA will guarantee 25% of without any county limit restrictions. Then there's the bonus entitlement, which is the difference between your county's conforming loan limit and the baseline conforming limit of $484,350 (as of 2024, these numbers shift annually). Your total entitlement is basically the basic plus the bonus. To find your available entitlement, you subtract any existing entitlement that's still tied up in an active VA loan from your total. Let me walk through a real example. Say you're in Orange County, California, where the 2024 conforming loan limit is $1,149,825. Your total entitlement would be $36,000 plus the bonus portion, which is 25% of the difference between $1,149,825 and $484,350. That bonus works out to $166,368.75. Your total entitlement is $202,368.75. If you've never used a VA loan before, that's the full amount you have available. Now here's where it gets interesting and where most people miss the nuance. The VA guarantees 25% of your loan amount up to your county's conforming limit. So if your total entitlement is $202,368.75, that means the VA could guarantee a loan of up to roughly $809,475 at 25% coverage without you needing a down payment. That's the no-down-payment threshold. Loans above that amount require a down payment equal to 25% of the difference between the loan amount and your county limit. This is what creates what lenders call "excess entitlement" or the scenario where you need to bring cash to the table even with a VA loan.
I ran into a situation last year with a veteran who had already used his VA loan benefit once and was trying to buy a second property in a high-cost county. He had paid down his previous VA loan significantly, so his remaining entitlement was substantial but not enough for the full purchase price without a down payment. The complication was that his previous loan hadn't been sold to the VA yet — the borrower had refinanced it into a conventional loan instead of doing a VA IRRRL. That meant the VA still considered his original entitlement tied up, even though he wasn't using it anymore. I had him request a Certificate of Eligibility update from the VA and provide documentation showing the prior loan payoff, which cleared up the entitlement issue. Without that paperwork, the lender would have calculated his available entitlement incorrectly and he might have been forced into an unnecessary down payment.
Get the Full Details

Building Your Own Worksheet
You don't need fancy software to do this. A basic spreadsheet or even a well-organized piece of paper will work fine. The key sections you need are your basic entitlement, your county's current conforming loan limit, your existing VA loan balance and remaining entitlement if applicable, and the resulting maximum loan amount with and without a down payment. The county loan limit changes every year based on FHFA adjustments, so make sure you're using the current figure for your specific county. Using last year's numbers will throw off your entire calculation. You can find your county's limit at the FHFA website, and it varies dramatically depending on whether you're in a standard county or a high-cost county. Here's a practical breakdown of what goes in each section of the worksheet:
- Basic Entitlement: Always $36,000 unless you're in a special circumstance like a Native American direct loan program.
- Bonus Entitlement: Calculated as 25% of the difference between your county limit and the baseline conforming limit.
- Total Entitlement: Basic plus bonus combined.
- Existing Entitlement Used: If you have an outstanding VA loan, this is 25% of the current loan balance, not the full balance. This is a common error point.
- Remaining Available Entitlement: Total minus what's currently in use.
- No-Down-Payment Maximum: Remaining entitlement divided by 0.25.
That last line is the number most people actually care about. It tells you the maximum loan you can get without putting any money down. Everything above that requires a down payment of 25% of the excess over your county limit. The most frequent mistake I see is calculating remaining entitlement based on the outstanding loan balance instead of 25% of that balance. If someone owes $200,000 on their existing VA loan, that's not $200,000 of entitlement used up. It's $50,000 — that's 25% of $200,000. Getting this wrong makes your remaining entitlement look much smaller than it actually is, which can lead to an unnecessarily large down payment request. Another pitfall is assuming that selling your home automatically frees up your entitlement. It doesn't. You need to have the VA restore your entitlement, which typically happens when the loan is paid in full and the property is no longer owned. If you've sold the home but still owe on the loan, your entitlement remains tied up. Even if you've paid off the loan but haven't formally requested restoration through the VA, your entitlement stays marked as used until the VA updates their records. This is something that comes up constantly in refinance scenarios where borrowers assume everything is automatic.
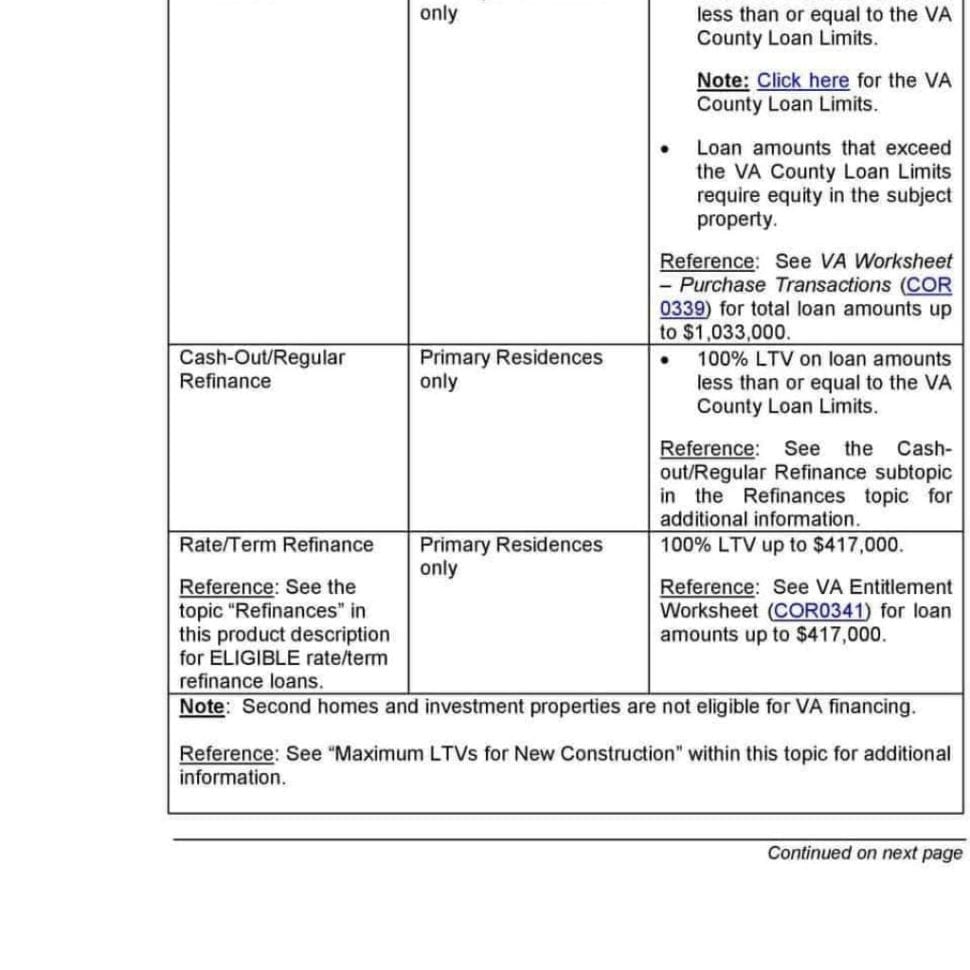
There's also the issue of Jumbo VA loans. If you're buying in a high-cost area and need a loan above the conforming limit, you're looking at what's technically a Jumbo VA loan. The VA will still guarantee it, but lenders face different risk parameters and some won't touch it at all. Even willing lenders may require a larger down payment than the worksheet suggests because they're pricing in the additional risk. The worksheet gives you the VA's mathematical guarantee, not necessarily what any given lender will actually fund. One more thing that trips people up: the difference between the VA's loan limit and what the VA guarantees. The VA doesn't have a maximum loan amount per se. What exists is a maximum loan amount where the VA provides full guaranty without requiring a down payment. Above that, you can still get a VA loan, but you'll likely need to put money down. Some lenders conflate these two concepts and either deny loans they should approve or push unnecessary down payments.
When the Worksheet Falls Short
Even with a perfectly calculated worksheet, there are scenarios where the math doesn't tell the whole story. Debt-to-income ratios still apply. The VA doesn't set a hard DTI ceiling, but most lenders have their own thresholds, typically around 41% to 45% depending on the lender and your residual income. Your VA loan amount isn't just about entitlement — it's also about whether you can service the debt. A worksheet won't tell you that. Residual income requirements are another factor that the VA enforces more strictly than many people expect. These vary by family size and region. If your projected monthly income after all housing and non-housing expenses doesn't meet the residual income threshold for your area and household size, the VA may still approve the loan but the lender might not. Again, the worksheet doesn't account for this. For combat-related or service-connected disability cases, there are additional considerations. Some veterans qualify for exemption from the funding fee, and a few specific scenarios allow for adjusted calculations. If you're in that category, a standard worksheet might not capture all the adjustments available to you. You'd want to work with someone familiar with those provisions rather than relying solely on a generic template.
Below is a simple worksheet structure you can copy into a spreadsheet or print out for manual use. The formulas in a spreadsheet version would be straightforward — basic arithmetic operations on the cells containing your entitlement figures and county limits.
VA Loan Amount Calculation Worksheet Template
Section 1: Your Basic Information County of Purchase: _______________ 2024 County Conforming Loan Limit: $__________
Baseline Conforming Limit (2024): $484,350 Section 2: Entitlement Calculation Basic Entitlement: $36,000
Bonus Entitlement: (County Limit minus $484,350) × 0.25 = $__________ Total Entitlement: $36,000 + Bonus = $__________ Section 3: Existing VA Loan Impact (if applicable)
Outstanding VA Loan Balance: $__________ Entitlement Currently Used: Loan Balance × 0.25 = $__________ Remaining Available Entitlement: Total minus Used = $__________
Section 4: Maximum Loan Amounts No-Down-Payment Maximum: Remaining Entitlement ÷ 0.25 = $__________ Target Purchase Price: $__________
Down Payment Required (if any): If target exceeds no-down-payment max, calculate 25% of the excess over county limit This structure covers the vast majority of VA loan scenarios you'll encounter. The ones that don't fit here are typically involving Native American direct loans, assumable VA loans with credit qualification, or specialized VA programs for manufactured housing. For those, you'd need guidance beyond a standard worksheet, and in those cases working with a VA-experienced loan officer is less of a luxury and more of a necessity. The bottom line is that the calculation itself is mechanical. The difficulty comes from knowing which numbers to plug in and understanding where the VA's rules diverge from conventional lending assumptions. Get the entitlement math right, verify your county limits, and then run your numbers through a lender's actual underwriting guidelines before you fall in love with a property. The worksheet gets you to the starting line. Everything after that depends on the lender, the property, and the current market conditions.