Why VA Loan Calculators Are More Tricky Than They Look
You plug in the purchase price, select VA loan, and hit calculate. The output shows a clean monthly payment and calls it a day. That's where most people get tripped up because the calculator doesn't actually tell you everything it should. I've been working with VA loans long enough that I've watched this process break deals at closing. The gap between what the calculator shows and what actually happens is bigger than most borrowers expect.
How to Use a Va Loan Calculator Mortgage Calculator Without Missing the Critical Details
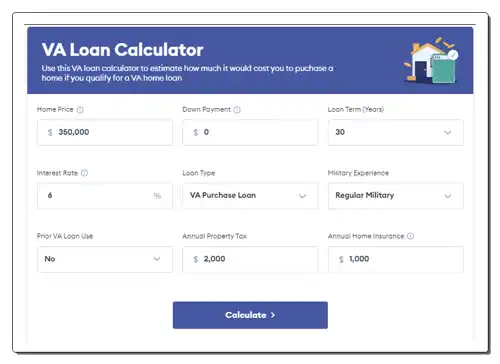
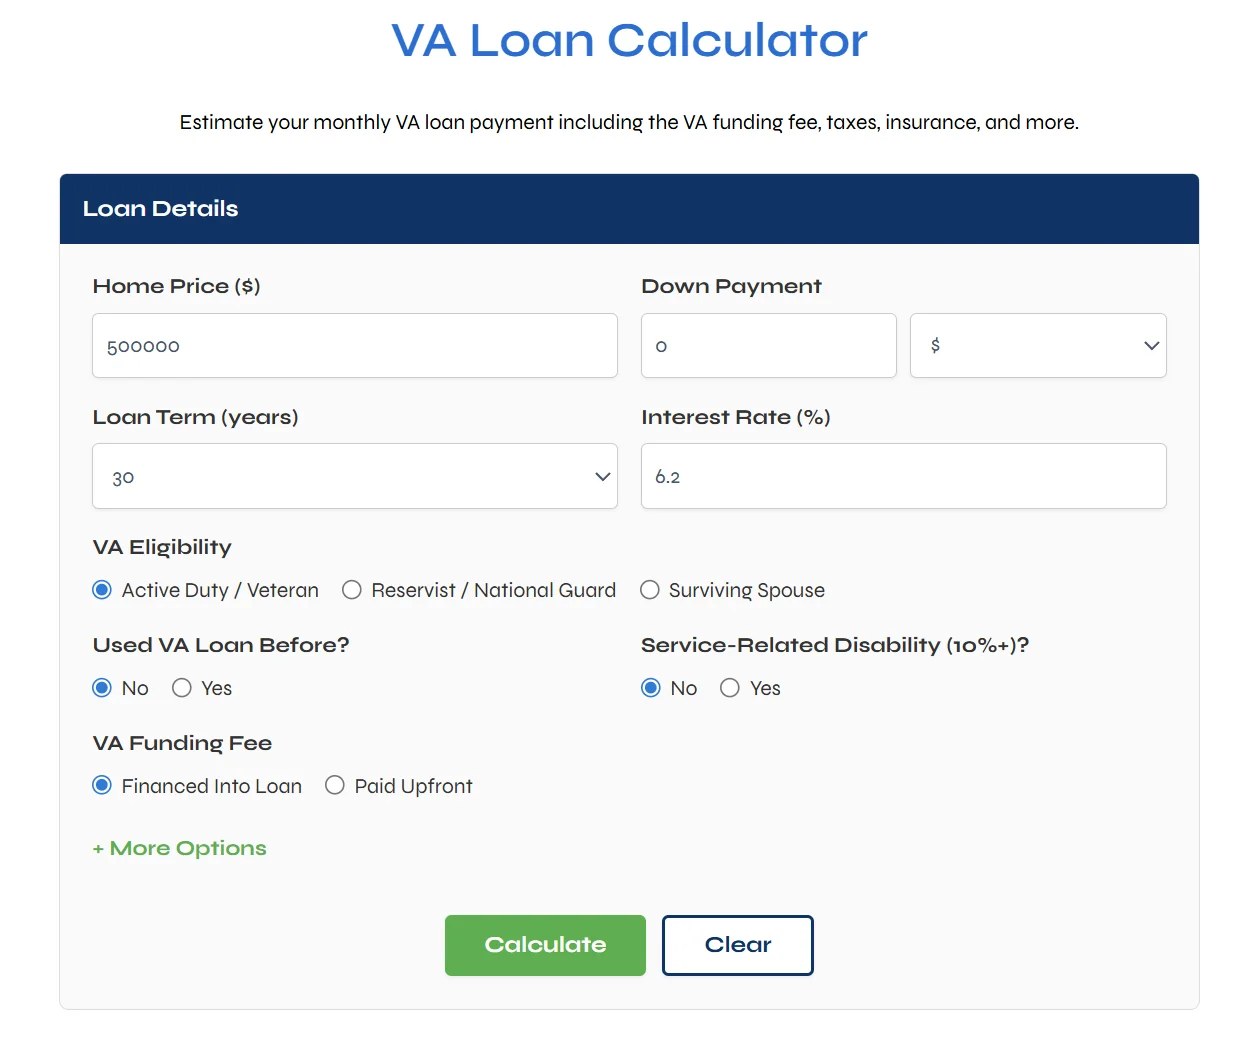
Start by understanding that VA loans don't require a down payment, which makes them attractive, but it also means the funding fee becomes a major cost factor that most people underweight. The funding fee for a first-use VA loan with no down payment currently sits at 2.3% of the loan amount as of 2025. On a $400,000 home, that's roughly $9,200 added to your mortgage balance. A basic calculator will show you the payment, but it won't always make that fee calculation transparent unless you dig into the settings.Here's how I use the tool correctly now. I enter the full purchase price, set the down payment to zero since that's typical for VA loans, check the funding fee box, and then adjust the interest rate to what I've actually seen lenders offering that week. I don't just pick the rate from the board. I look at what my last three borrowers actually closed at, because those numbers tend to cluster around 6.5 to 7.25% right now depending on the market. The difference between 6.5% and 7.0% on a $409,200 VA loan is about $175 per month. That's the kind of detail that matters when you're advising someone. The biggest mistake I see is people ignoring the VA funding fee. It's not optional. It's not something you can negotiate away at closing unless you qualify for an exemption due to a service-connected disability. If you're not disabled-related, the fee gets rolled into the loan and you pay interest on it for the life of the loan. Some calculators separate this out. Some bury it. You need to verify the output includes it before you trust the number.
What Most VA Loan Calculators Miss
Property taxes and homeowner's insurance get estimated using county averages, but they're rarely accurate for the specific property. I had a case last year where the calculator showed taxes at $2,400 a year based on the county median, but the actual property was in a special flood zone assessment district that added $1,800 annually on top of that. The borrower found out at closing. The monthly payment difference was $275 more than the calculator predicted. That's a deal-breaker if you're working near the debt-to-income limit. Another thing that standard calculators don't show clearly: VA loans have a residual value requirement. The VA needs to be confident the borrower can handle the payment even after other debts are paid. The calculator might show you can afford $2,800 a month, but if your credit card payments and car notes push your back-end ratio above 41%, the VA appraiser or underwriter could still flag it. The calculator is a screening tool, not a guarantee of approval. I also run into issues with the disability exemption calculation. If a borrower has a 10% service-connected disability rating, they get a partial waiver on the funding fee. The standard VA Loan Calculator Mortgage Calculator interface doesn't always ask about disability status upfront. You might need to manually adjust or skip the funding fee to see the true payment scenario. I always ask this question early in the conversation. It changes the math significantly for eligible veterans.
Get the Full Details

A Real Problem I Ran Into and How I Solved It
Working with a borrower who was purchasing a manufactured home through a VA loan, I hit a wall. The calculator kept showing results that assumed a traditional site-built property. The loan limits, the funding fee percentage, and even the interest rate adjustments all came out wrong for a manufactured home purchase. The manufacturer had to be HUD-certified, the land needed to be owned, and the loan term was different. I ended up pulling the HUD appraisal guidelines manually, calculating the funding fee at the 2.3% rate for first-use, and then adjusting the loan-to-value ratio based on the manufactured home's depreciation schedule. It took about 45 minutes of manual work that no online calculator would do automatically. The workaround was to use the calculator for a baseline number, then apply the VA's manufactured housing addendum adjustments by hand. If you're dealing with non-traditional properties, treat the calculator as a starting point, not a final answer.When to Trust the Calculator and When to Walk Away
The tool works fine for quick back-of-the-envelope estimates on standard single-family homes. If you want to know whether a $350,000 home with a 7% interest rate lands somewhere in the neighborhood of $2,200 to $2,500 a month including taxes and insurance, it gets you close. But for anything involving second-trier status, partial disability waivers, jumbo VA loans, manufactured housing, or investment properties with roommates, the calculator starts to drift. Jumbo VA loans above the county conforming limit have different rules. The funding fee doesn't change, but the loan amount, the debt-to-income ratios the underwriter applies, and the reserve requirements all shift in ways the basic tool won't show. If you need precision, run the numbers through a proper VA loan estimator that asks about funding fee exemptions, then cross-check with a lender who can pull actual rate sheets. I usually do both. The calculator gives me a quick reference point. The lender gives me the real number. There's no shame in using a calculator for orientation. There is shame in presenting its output as final advice without verification.
Bottom Line on Using These Tools
VA Loan Calculator Mortgage Calculator tools are useful if you understand their blind spots. They show payment estimates. They don't show approval certainty. They estimate taxes. They miss special assessments. They handle standard cases well and stumble on anything that isn't a straightforward purchase of a site-built home by a first-time VA borrower with full entitlement. I've found that the most reliable approach is to use the calculator for initial scoping, verify the funding fee calculation manually, and then confirm the final number with an actual lender before making any decisions. That's how I avoid the kind of embarrassment where a borrower shows up at closing and the payment is $300 higher than what they thought it would be.