How to Actually Use a Va Loan Points Calculator
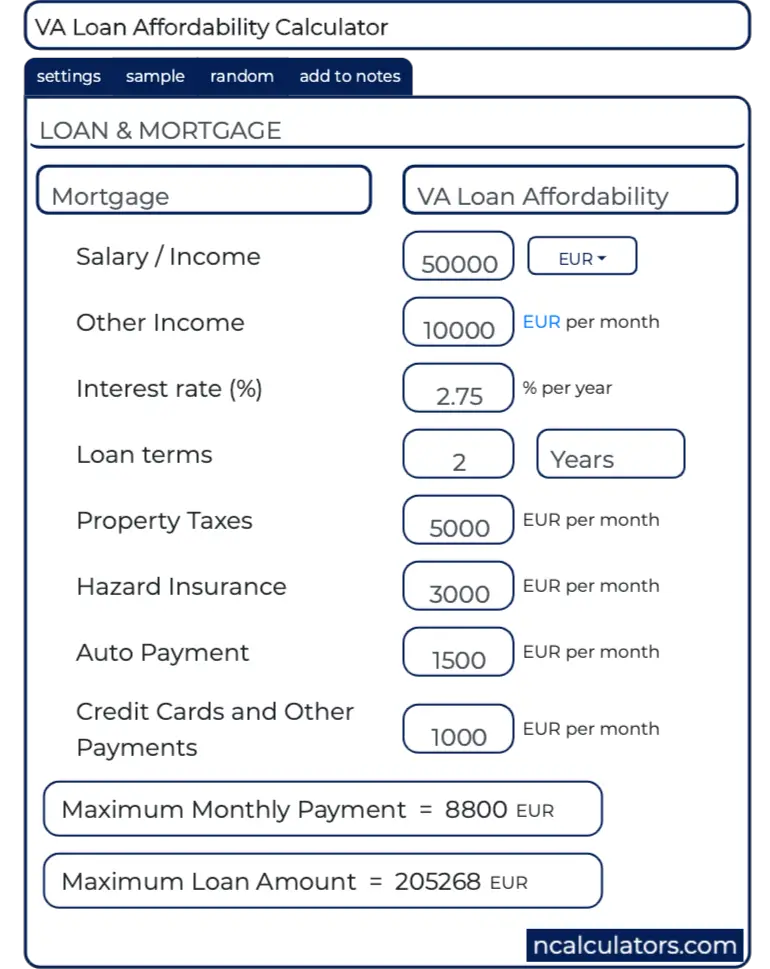
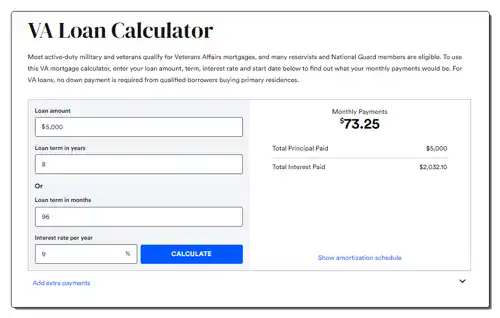
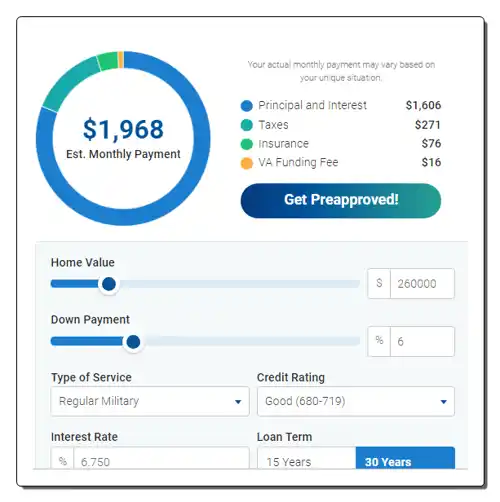
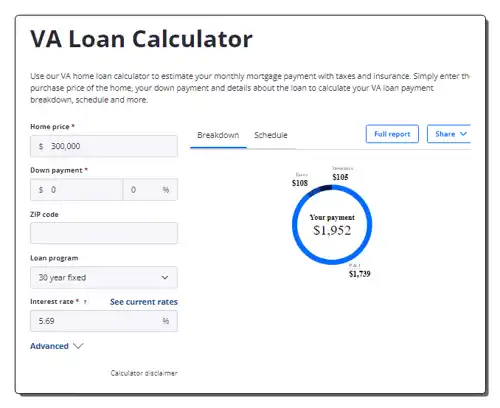
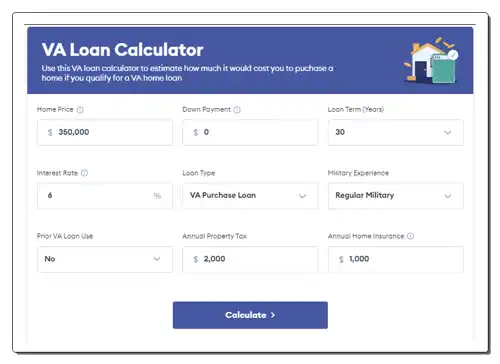
Buying discount points on a VA loan isn't magic. You pay one percent of the loan amount upfront, and your rate drops somewhere between 0.125% and 0.25%. Most people I talk to treat it like a straightforward calculation. It's not that simple, and the tools out there usually don't tell you everything you need to know before you sign. A proper calculator takes three inputs — your loan amount, your base interest rate, and how many points you want to buy — then outputs the total cost of those points, the new rate, your monthly payment difference, and how long it takes to break even. That's the useful part. Everything else is filler. The formula is basic arithmetic. One point equals one percent of the loan amount. So on a $350,000 VA loan, one point costs $3,500. Two points cost $7,000. The rate reduction is typically quoted by your lender as a flat 0.125% to 0.25% per point, though that varies by market conditions and which lender you're talking to. Your new monthly payment gets recalculated using the reduced rate, and then you divide the total point cost by the monthly savings to get your breakeven period in months.
I built my own spreadsheet for this because the free calculators online consistently mess up the breakeven math. They'll show you a 34-month break-even on paper but never factor in whether you're rolling the points into the loan or paying them at closing. Those two scenarios produce very different monthly numbers, and the free tools usually assume you're paying out of pocket even when the borrower is financing everything.
The Mechanics Behind the Calculation
Here's the part nobody emphasizes enough. VA discount points are only tax-deductible as mortgage interest if they don't exceed the total lender-charged origination charges on the loan. If you buy two points on a $300,000 loan, that's $6,000 in points. If your total lender fees (origination, underwriting, processing) add up to only $4,500, then only $4,500 of those points are deductible. The remaining $1,500 gets capitalized into your loan cost basis instead. This is a real edge case I ran into last fall with a client who was refinancing his VA loan. His lender had structured the origination fees unusually low to compete on price, which meant most of his points couldn't be deducted. We spent an afternoon reworking the numbers and ended up having him pay the points out of pocket rather than finance them, since the tax deduction he was counting on didn't actually apply the way he thought it would. The calculation itself is straightforward. You take the point cost and divide it by the monthly payment reduction. For example: a $400,000 VA loan at 6.5% with one point bought at $4,000 drops the rate to 6.25%. The monthly payment goes from about $2,528 to $2,467 — a $61 difference. Divide $4,000 by $61 and you get roughly 66 months to break even. That's over five and a half years. If you sell or refinance before then, you've lost money on the points.
Get the Full Details
Where the Calculation Breaks Down
The biggest problem with any Va Loan Points Calculator is that it assumes a static rate environment. In practice, rates move. A point buydown that makes sense at today's rates might not make sense next month if rates drop on their own. I've seen borrowers lock in a rate reduction by buying points, then watch the market rate fall below their buydown rate three weeks later. They're stuck with a higher payment than they needed to be making, and the points are a sunk cost. Another limitation: these calculators don't account for the VA funding fee unless you specifically tell them to. The funding fee is separate from points and can be financed into the loan, but it's a significant cost that interacts with your overall numbers. If you're buying points and financing the funding fee at the same time, your monthly payment savings from the lower rate might be smaller than you expect because your principal is larger. There's also the question of whether it's cheaper to finance the points or pay them at closing. Financing them means you're borrowing money to reduce your rate, which is a circular calculation. On a $300,000 loan, financing one point adds $3,000 to your balance. At 6.5% over 30 years, that $3,000 costs you about $21 per month in additional payment. If the point buydown saves you $40 per month, your net savings is only $19. The breakeven stretches from maybe 75 months to over 150 months depending on how you structure it. Most free calculators won't show you this distinction.
What to Do Instead of Trusting a Calculator
Build your own table. Put the loan amount in cell A1, the base rate in A2, the points cost per percent in A3, the monthly savings per point in A4, and divide A3 by A4 for breakeven months. It takes about ten minutes and you get exact numbers for your specific situation instead of rounded estimates from a web tool. You can adjust each variable independently and see how changes in rate or loan amount affect the outcome. I prefer this approach because it forces you to look at each number individually rather than feeding it all into a black box and hoping the output is right. The black-box calculators are convenient but they operate on generic assumptions that don't always match your loan terms. VA loans have specific rules around what counts as a discount point versus an origination charge, and those rules change depending on whether you're buying a home or refinancing. A static calculator doesn't know that difference. The bottom line is that a Va Loan Points Calculator is a starting point, not a decision tool. The math is simple enough to do yourself in minutes. What matters more is understanding when those points actually work for you — which typically means staying in the home for at least five to seven years, having a clear rate reduction quoted in writing from your lender, and knowing exactly how much of the point cost is deductible versus capitalized. Without that context, the calculator gives you a number that sounds good until you find out it doesn't apply to your situation.