Understanding what actually goes into a VA loan closing
Most people think VA loans have zero closing costs. They don't. The VA just limits what lenders can charge and allows certain costs to be rolled into the funding fee. That's a real difference from what most calculators show you versus what actually comes due at the table. I've been doing this long enough to know the numbers on paper rarely match the CD three days before close. Here is the practical breakdown of how to actually use a Va Mortgage Closing Cost Calculator and what to watch for when the final numbers hit your desk.
How a Va Mortgage Closing Cost Calculator actually works
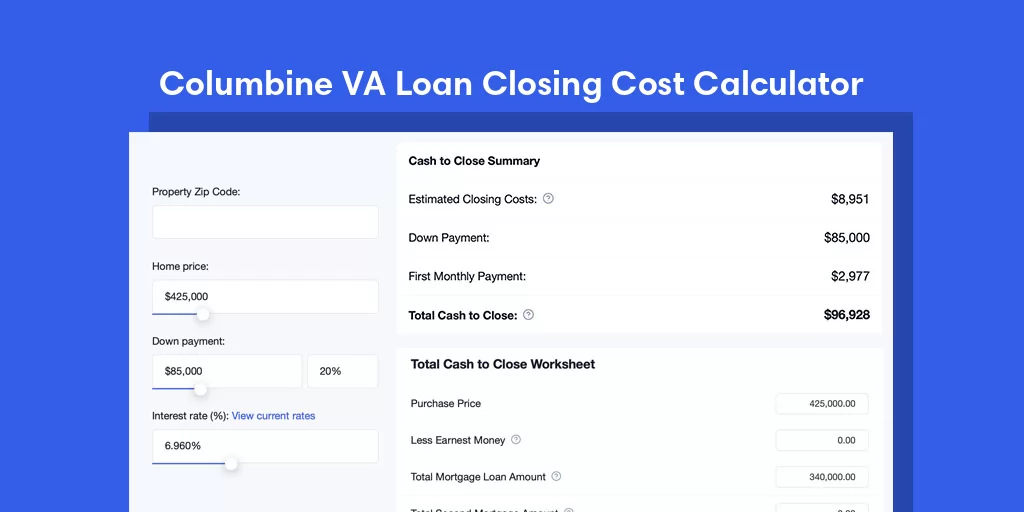
The core mechanics are straightforward. You input the purchase price or refinance amount, select whether it is a purchase or IRRRL, enter your service member status to determine the funding fee percentage, and then toggle which costs you expect to roll into the loan versus pay out of pocket. The calculator subtracts the VA funding fee from your closing cost estimate and adjusts the loan amount accordingly. Simple in theory. Here is where it gets messy in practice. VA loans allow the seller to pay up to four percent of the purchase price in concessions without triggering additional lender requirements. Most free online calculators do not account for this. I learned this the hard way on a cash-out refi in 2022. The borrower wanted to cover his points and appraisal out of the seller credit. The calculator showed he was fine. It was not. The lender had to re-underwrite the appraisal because the credit pushed the effective purchase price below what the appraiser had to justify. We ended up switching the credit to closing costs instead of points, which kept the transaction clean. Another issue nobody talks about enough is the difference between the estimate and the actual. VA loans require a good faith estimate within three business days of application and a revised CD every time a material change occurs. Calculators give you a snapshot. They do not track variance. If your rate locks at 6.75 percent and then moves to 6.875 percent three days later, your closing cost estimate changes by a few hundred dollars and you need to recalculate everything from scratch. The tool does not do that for you automatically.
What most calculators miss
The VA funding fee itself is not a closing cost in the traditional sense. It is a one-time fee that ranges from 2.3 percent for first-use purchases down to 1.65 percent for subsequent purchases if you have prior VA loan experience, and 3.6 percent for cash-out refinances. It can be financed into the loan. Many people confuse this with a closing cost and either pay it twice or forget it entirely. The calculator will include it if you select the right box. It is easy to skip that step. Valuation fees are another silent cost. VA appraisals run higher than conventional ones because the VA requires a minimum property requirements check and sometimes a WAVES report. Expect to pay between $500 and $900 depending on your state. Some lenders try to bundle this into other line items so the borrower does not see it clearly. It shows up on the CD anyway. You will catch it there if you actually read it. Service charges from the VA are not included in any calculator. These are administrative fees the VA assesses after closing. They vary by region and typically range from seventy-five to two hundred dollars. They show up on your closing disclosure as a separate line item but never appear in an estimate tool. Budget for them separately if you want accuracy.
Get the Full Details
When a calculator falls apart
There are specific scenarios where any standard Va Mortgage Closing Cost Calculator will give you bad information. The first is a no-down-payment purchase combined with seller concessions and discount points all at once. The four percent cap gets complicated when you are also rolling the funding fee into the loan. The calculator may show you can pay for everything. The underwriter will tell you that is impossible once they review the actual CD. You will need to adjust your strategy manually. The second scenario is a non-obvious IRRRL where the borrower already used their entitlement on a previous VA loan and wants to do a cash-out refi. The calculator often defaults to the first-use funding fee percentage. It should be using the subsequent-use percentage. I have seen this mistake inflate estimates by thousands of dollars because the funding fee jumps from roughly 2.3 percent to 3.6 percent when the calculator picks the wrong tier.
A workaround I rely on
After running an estimate through an online calculator, I manually cross-reference it against the lender's Loan Estimate using a spreadsheet. I pull each line item separately and compare it against what the calculator projected. Anything that diverges by more than five percent gets flagged. This usually catches misapplied funding fees, incorrect concession handling, and missing VA service charges. It adds about ten minutes to the process but saves hours of back-and-forth with the underwriter later. If you need something more robust than a free online tool, you can download a basic VA closing cost tracker sheet that breaks out each fee category and auto-calculates the four percent concession ceiling. I have a version that accounts for WAVE fees, VA service charges, and funding fee tiers in one place. It is available for download through my contact page if you want to use it. VA loans are straightforward until they are not. The calculator gets you in the right neighborhood. Reading the CD and cross-checking every line is what keeps you from getting surprised.