How to Actually Use a VA Mortgage Estimator Without Getting Misled
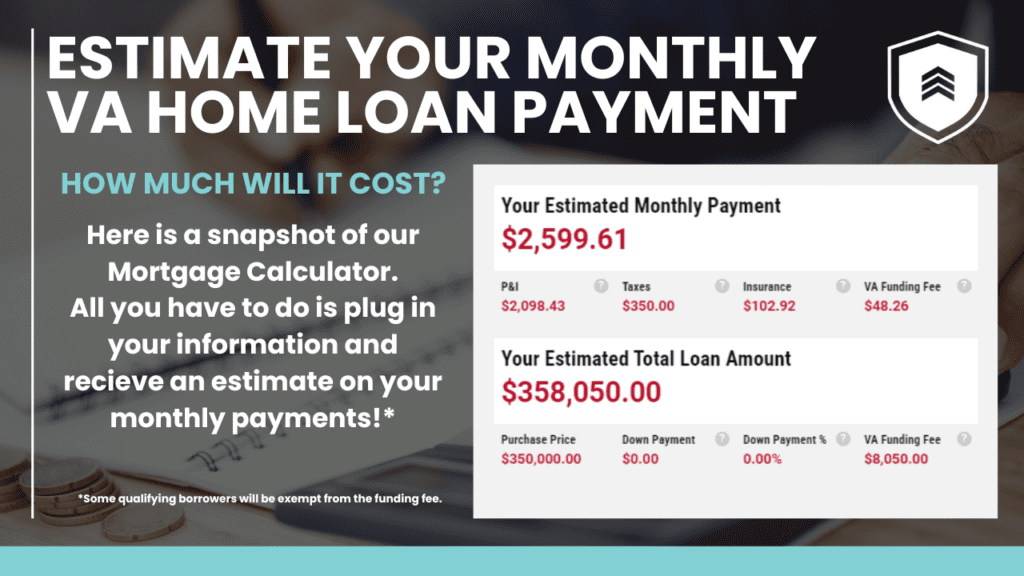
I've watched too many people run a VA mortgage estimator online and come out convinced they knew their actual monthly payment. The tools are fine for rough ballparks, but they leave out half the costs that show up on your Closing Disclosure. Here's how to get something useful out of one without the hype. Start by pulling up a calculator from a reputable lender site, not some ad-riddled aggregator. VA loans have a specific funding fee structure that a lot of free online tools completely botch. The VA funding fee ranges from 1.4% to 3.6% of the loan amount depending on your service category, down payment, and whether it's your first use or a subsequent use. The government gives you a formula, but most consumer-facing calculators just slap on a flat number and call it a day. I had a client last year who was quoted $38,000 in closing costs by an online estimator. The real number came in at $31,200 because the tool had overestimated the funding fee and didn't account for the seller-contribution ceiling of 4% that applies in most transactions. That's a $6,800 difference that changes the conversation entirely. Enter your property price, your down payment (zero if you're using full entitlement), and your estimated interest rate. Make sure the tool lets you toggle between first-use and subsequent-use funding fee percentages. If it doesn't, you're probably looking at a generic mortgage calculator dressed up with a VA badge. The output should break down principal and interest, property taxes, homeowners insurance, and the VA funding fee. Anything missing is a red flag.
The Funding Fee Changes Everything
Here's the thing most people don't realize about VA loans: the funding fee is not optional and it's not rolled into the interest rate. It's a one-time payment that gets financed into your loan balance if you don't pay it at closing. That means you're paying interest on top of the funding fee over the life of the loan. On a $350,000 home with zero down and a 2.5% funding fee (first-time use, regular military), you're looking at an additional $8,750 added to your loan balance. At 6.5% interest over 30 years, that extra $8,750 costs you roughly $10,900 in interest alone. The effective cost of borrowing just went up significantly, and a basic VA mortgage estimator won't always make that connection clear for you. The workaround I use is to calculate the funding fee separately and add it to the loan amount before running the payment estimation. So instead of entering $350,000 as your loan amount, you enter $358,750 and then mentally subtract the funding fee portion when you're looking at your actual equity position. It takes an extra minute but it stops you from being surprised later.
What the Estimator Won't Tell You
VA loan estimates are notoriously soft on secondary costs. The funding fee is the big one, but there are others that vary wildly by location and lender. Title insurance in some states can be $3,000 to $6,000 on a $300K purchase. Appraisal fees for VA loans run $550 to $900 because the VA requires a specific appraisal process that includes a property condition assessment. Some lenders charge an administrative "VA processing fee" that's not actually required by the VA and is pure profit markup. I've seen it go from $0 to $1,500 depending on who you're working with. The VA also has a residual income requirement that no estimator will check for you. This is different from the debt-to-income ratio. It looks at how much money is left over after bills in your specific household size and area. If you have a large family in a low-cost rural area, the threshold is lower. A family of eight in a high-cost suburban area needs significantly more left over. This disqualification happens quietly and usually right before closing, which is not a good place to find out. You'll need a processor who actually understands the residual income tables, not just a computer algorithm.
Get the Full Details

My Go-To Method for Accuracy
Run the online estimator for a baseline, then get a Loan Estimate from three different VA-experienced lenders within a week. The VA mandates that Lenders provide Loan Estimates within three business days of application, so this is fast. Compare the funding fee line items, the origination charges, and the third-party services. The ones that match across all three estimates are likely real market rates. The ones that differ are where you negotiate. I've cut lender fees by $2,000 to $4,000 just by showing them competing estimates. Lenders know you're comparing and it changes the conversation immediately. One more thing nobody talks about: VA loans have a conforming loan limit that varies by county. In most of the country, the base conforming limit for a single-family home is $548,250, but in high-cost counties it can go up to $822,375 or more. If your loan exceeds the conforming limit, you're still covered by the VA guarantee but some lenders will require a higher credit score or larger reserve deposits. An estimator won't flag this. Check your county's VA loan limit before you fall in love with a property that might complicate your financing.