What the Vacant Land Loan Calculator Actually Does
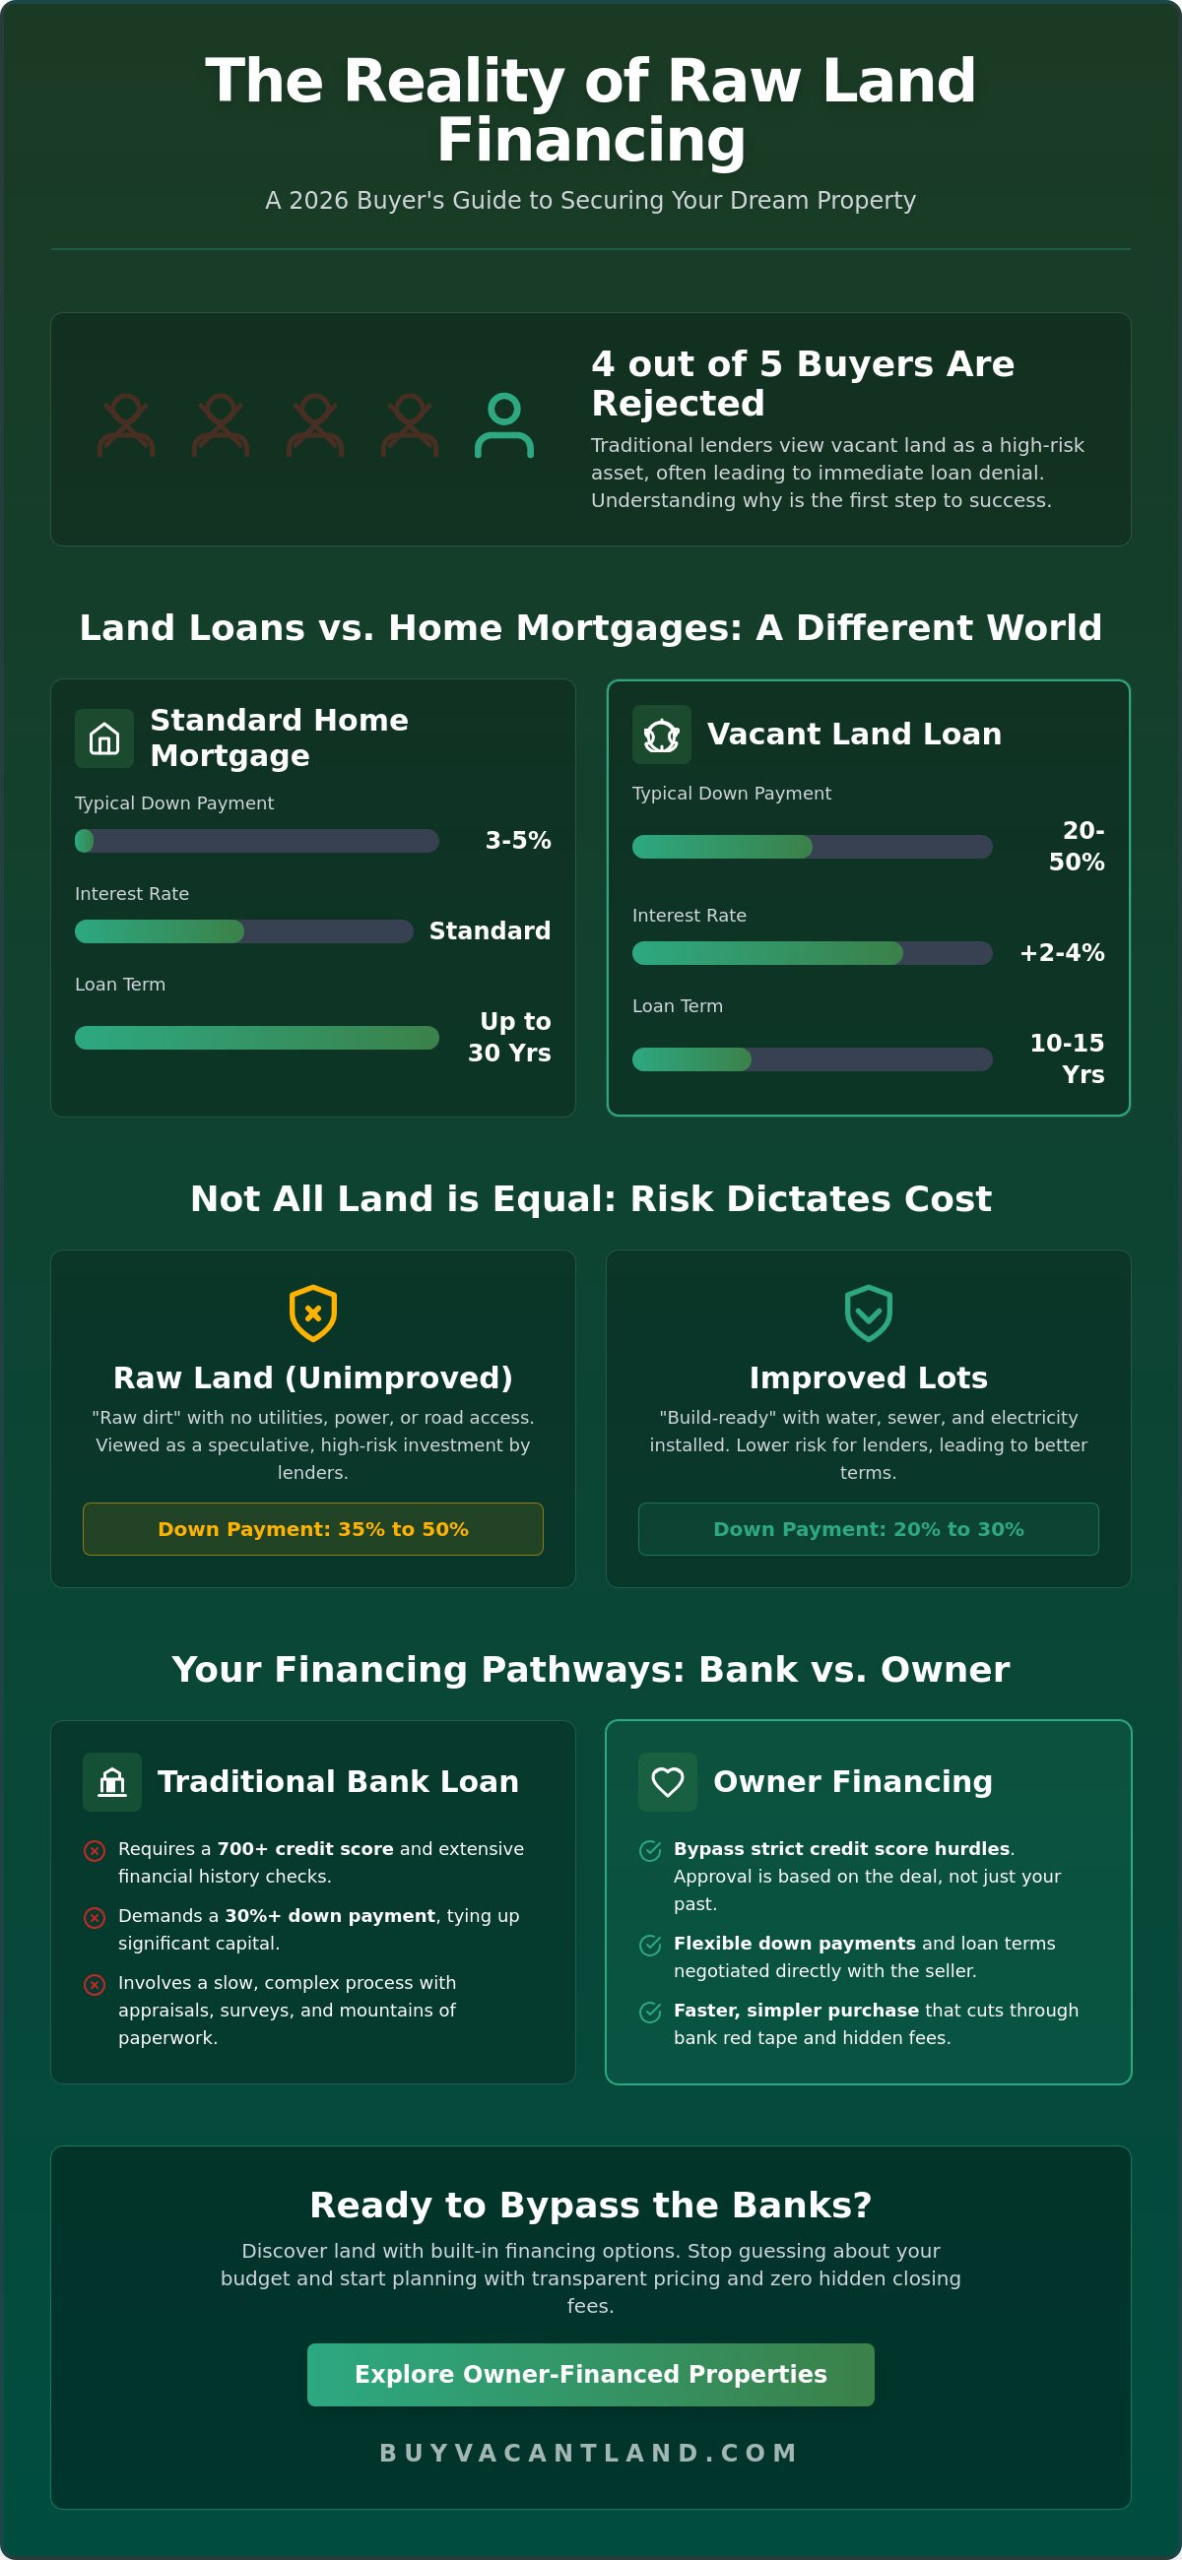
Most people building land loans are working with numbers that don't behave like regular mortgage math. A standard home loan calculator assumes you're buying an existing structure with an appraised value. Vacant land works differently because there is no collateral value to speak of until improvements are made. The Vacant Land Loan Calculator adjusts for that gap by factoring in higher loan-to-value ratios, shorter terms, and the risk premium lenders bake into these products. I spent three years working with rural lenders before I started building my own tools. The first thing I learned was that most online calculators are garbage for this purpose because they use residential mortgage assumptions. You plug in numbers and get back estimates that are off by 15 to 20 percent. That kind of error costs you a pre-approval letter.Vacant Land Loan Calculator
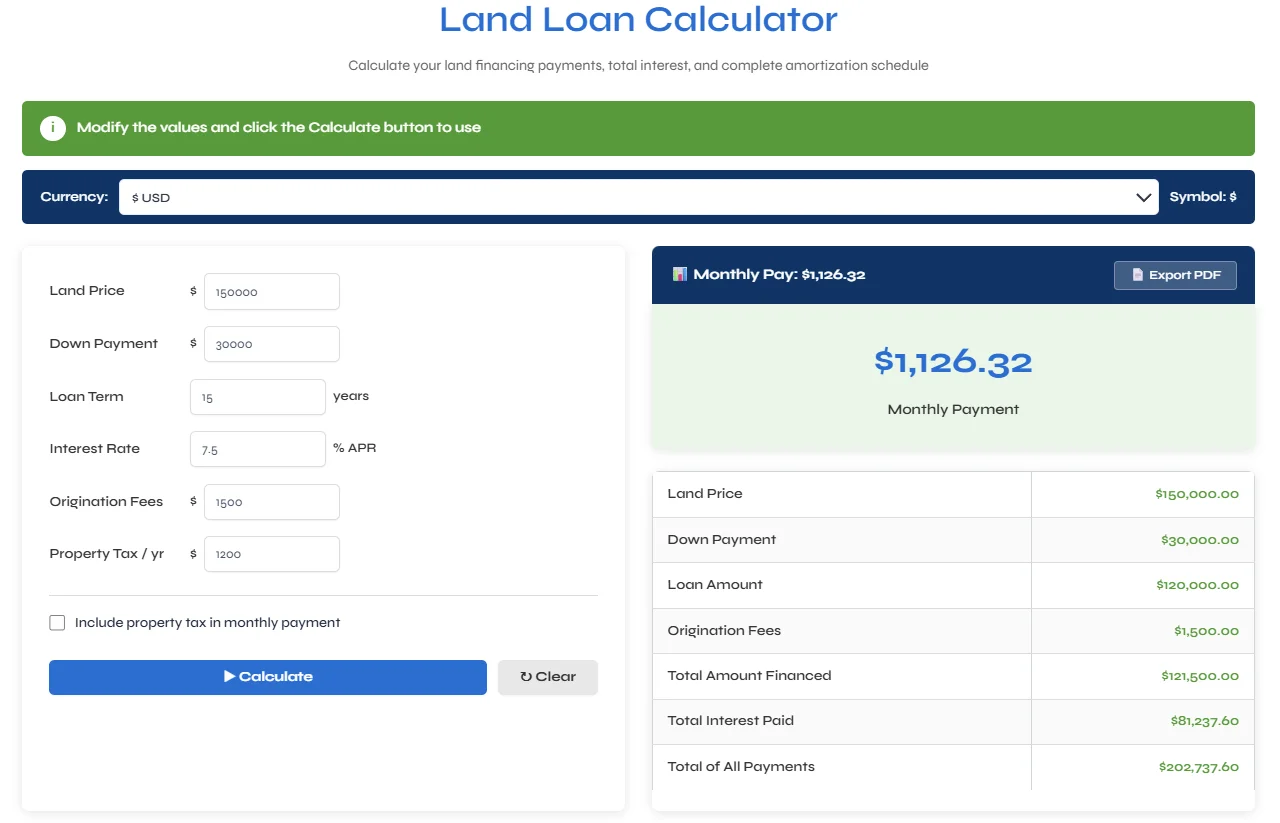
The core mechanics are straightforward once you understand the variables. You enter the purchase price, your down payment, the loan term, and the interest rate. What most people miss is that vacant land rates run 2 to 4 percentage points above conventional rates. On a $200,000 parcel at 9.5 percent over 15 years versus 6.5 percent over 30 years, your monthly payment jumps from roughly $1,328 to $2,152. That difference is not theoretical. I had a borrower tear up an application because the monthly payment blew past his debt-to-income ratio and he had no idea why the earlier calculator had made it look affordable. The other variable nobody accounts for is the loan-to-value ratio. Lenders typically finance 50 to 70 percent of raw land. Some go to 80 percent if the land has utilities, road access, and a cleared building permit. Without those items, expect the LTV to drop to 50 percent or lower. That means a $150,000 lot might require $75,000 to $100,000 down. The calculator should reflect this constraint, not just spit out a payment based on whatever rate you type in. Here is how I structure a calculation that actually works:
Start with the as-is appraised value, not the asking price. Assessors sometimes inflate land values in hot markets. Get a separate appraisal or pull recent comparable sales within a half-mile radius. Use the lower of the two numbers as your basis. Then apply the lender's maximum LTV for that specific parcel type. Divide the result by your required down payment percentage to confirm you have enough capital. Subtract the down payment from the purchase price to get the loan amount. Apply the interest rate and term to get the monthly payment. Factor in property taxes, which on vacant land can be surprisingly high if the county reassesses after purchase. Add escrow if your lender requires it. The total monthly obligation is your real number. I encountered a specific edge case that still comes to mind. A client was working with a rural parcel zoned agricultural. The calculator showed a payment around $1,400 a month based on 70 percent LTV. The lender, however, classified it as recreational land because the zoning allowed a weekend cabin but not a primary residence. That reclassification dropped the max LTV to 60 percent and pushed the rate up another half point. The actual payment came to $1,847. We went back and renegotiated the purchase price using the revised payment as leverage. The seller cut $12,000 off the contract. That $12,000 difference came directly from understanding how classification changes the underwriting math. Another thing people get wrong is the amortization structure. Many vacant land loans are interest-only for the first five years with a balloon payment at the end. If your calculator assumes full amortization over 15 or 20 years, you are looking at a monthly payment that does not exist. An interest-only $100,000 loan at 9 percent for five years costs $750 a month. A fully amortized version over 15 years at the same rate costs $1,016. The balloon payment due at year five is still $100,000 plus whatever principal you paid down during the interest-only period. Plan for that balloon or refinance before it hits.
There are also hidden costs that most calculators ignore. Impact fees from the county can range from $2,000 to $15,000 depending on whether you need to extend water, sewer, or electrical service to the lot. Soil percolation tests for septic systems run $1,500 to $3,000. Environmental assessments for wetlands or endangered species habitat can add another $2,500 to $5,000. These are not mandatory for every parcel but they trip up people who are not tracking them. Include them in your total project cost when you run the numbers. The main limitation of any calculator is that it cannot account for lender-specific overlays. One bank might require a higher down payment for land in a flood zone. Another might refuse to finance lots under a certain acreage. A third might insist on a higher credit score threshold. Run your numbers through the calculator first to get a baseline. Then call two or three lenders who actually do land loans and ask for their specific requirements. The variance between lenders can be massive and no generic tool captures that. If you are serious about this, build a spreadsheet with the variables I mentioned and test at least five scenarios. Vary the LTV from 50 to 70 percent. Test interest rates from 8 to 11 percent. Run both interest-only and fully amortized payments. See where your break-even point is between the monthly cash flow and the total project cost. That exercise takes about 45 minutes and saves you from walking into a lender with unrealistic expectations.
Get the Full Details
The tool itself is simple. The reality behind it is not. Most people who skip the detailed analysis end up with a parcel they cannot afford to develop and a loan they cannot refinance out of. Do the math properly before you make an offer.