The Mechanics of Getting a Number Right
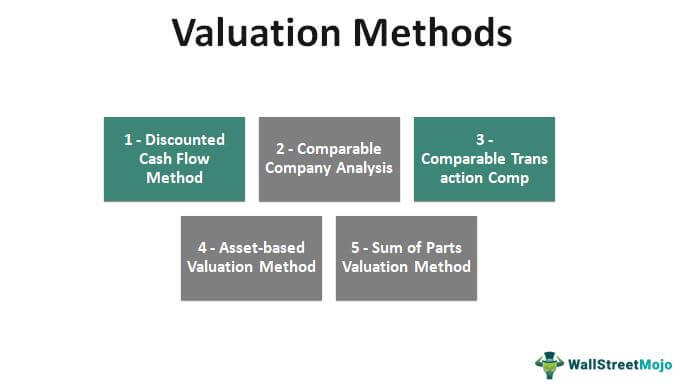
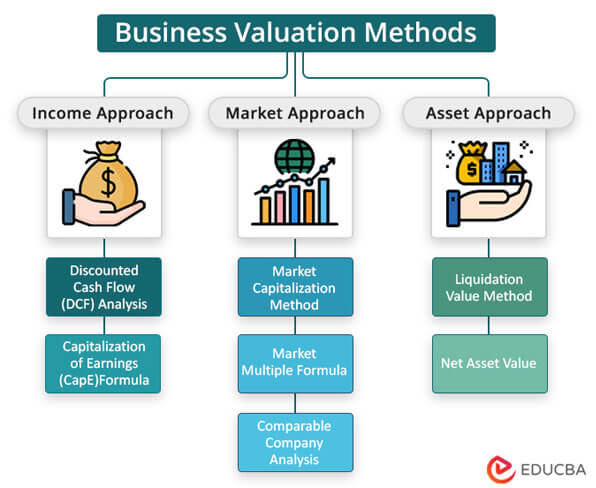
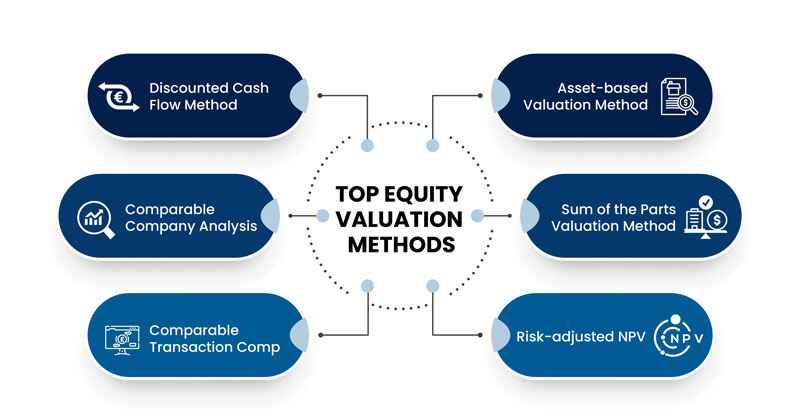
Most people treat Valuation And Analysis as a math problem. It isn't. It's an argument you dress up in spreadsheets. I've watched senior analysts burn through twelve hours building models that turned out to be sophisticated ways of saying "we don't know." The trick is figuring out which parts of the model actually move the needle and which parts are just noise dressed in five decimal places. The standard approach starts with selecting a method. Discounted cash flow is the default for established businesses. Market comparables work when there's enough liquidity. Asset-based methods surface when you're dealing with holding companies or distressed situations. Nobody tells you that the method choice often matters less than the assumptions baked into it. I learned that the hard way back in 2019 when a client handed me a SaaS company with thirty-eight months of runway and insisted on a DCF. The revenue projections were built on a single enterprise deal that hadn't closed yet. Three weeks later that deal fell apart and the entire model collapsed. I ended up switching to a hybrid approach—burn rate analysis for the near term layered under a revenue multiple for the terminal period. It took me twenty minutes to rebuild instead of the twelve hours I'd already spent.Setting Up Your Valuation And Analysis Framework
Start by defining what you're actually valuing. A controlling stake in a private company isn't the same thing as a minority stake in a public one, even if the underlying business is identical. Illiquidity discounts range from twenty to thirty-five percent depending on the market. Lack of voting control can knock another ten to fifteen percent off. I see people skip these adjustments constantly and then act confused when their number doesn't match what a buyer would actually pay. Build your financial model in a way that forces discipline. One sheet for historical financials pulled from actual reports. One sheet for your assumptions where every growth rate and margin sits alongside a source or a rationale. One sheet for the actual valuation calculation. When an auditor or a skeptical counterparty asks why your EBITDA margin is twelve percent instead of the industry average of nine, you need to point at something, not a gut feeling. The model should survive that question without requiring a separate presentation. For DCF work, the discount rate is where most people make mistakes. WACC calculations look precise but they're built on inputs that shift with market sentiment. Beta values from Yahoo Finance are backward-looking and often stale. The risk-free rate changes depending on which government bond you pick. I usually run three separate discount rates—one based on the CAPM, one using a build-up method, and one pulled from recent comparable transactions—and take a weighted middle rather than picking the prettiest number. This typically shifts my valuation by fifteen to twenty-five percent compared to a single-input approach.
Terminal value accounts for sixty to eighty percent of the total DCF output. That means the perpetuity growth rate you pick matters enormously. Anything above three percent starts requiring justification. The risk is that a zero-point-five percent change in your terminal growth rate can swing the valuation by ten to fifteen percent on high-growth companies. I keep terminal growth at two to two-point-five percent for mature businesses and explicitly note in the model when I push higher because the business has durable competitive advantages that justify it.
Working With Real Data
Historical financials are only useful if they're normalized. One-time expenses, owner perks disguised as operating costs, revenue recognized too early or too late—these all distort the picture. I spent three days once reconciling a manufacturing company's books because their COGS excluded a significant portion of freight costs that were booked under logistics instead. The gross margin looked like forty-two percent when it was really thirty-four. That gap changed the entire valuation story. When you don't have clean financials, like with early-stage companies or private businesses with informal bookkeeping, you work backward from cash flow. Revenue minus direct costs gives you a rough gross profit. Operating expenses get estimated from industry benchmarks adjusted for the company's actual headcount and footprint. It's less precise but more honest than forcing a GAAP framework onto data that never followed one. Market comparables require the same normalization. Public comps trade at different scales, with different capital structures, and under different market conditions than the company you're valuing. Price-to-earnings ratios mean nothing if one company has heavy debt and the other doesn't. EV/EBITDA is cleaner for cross-company comparison but still needs adjustment for growth trajectories and margin profiles. I use a band approach rather than a single multiple—taking the twenty-fifth percentile through the seventy-fifth percentile of comparable transactions and applying context-specific adjustments for size, risk, and growth.
Get the Full Details
When The Model Lies To You
Valuation models are only as good as their weakest assumption. A common failure mode is overconfidence in forecast accuracy. I've seen analysts project five years of revenue with annual precision when quarterly actuals for the same company had been swinging between forty and sixty percent of guidance. The model produced a clean output but the confidence interval around that number was wider than the result itself. Another trap is treating the output as a precise figure instead of a range. A DCF for a mid-market company typically has an error band of plus or minus thirty percent. Saying "this company is worth four million two hundred thousand dollars" signals that you misunderstand the exercise. "Between three and five point five million, most likely around four" is the honest answer and it's more useful to anyone making a decision. Sometimes the right answer is that you can't value it reliably. Pre-revenue companies with no clear path to monetization, businesses in industries undergoing structural disruption, assets with highly idiosyncratic characteristics—these resist standard methods. In those cases I fall back on scenario analysis: best case, base case, and worst case with explicit probabilities, or I acknowledge the limitation and recommend a different approach entirely, like option pricing for biotech pipelines or replacement cost for specialized equipment.
Practical Checks Before You Ship a Number
Run a sensitivity table on your two most uncertain inputs. Revenue growth and discount rate are the usual suspects. If a small change in either one moves your result by more than twenty percent, flag that prominently. Nobody trusts a valuation that's fragile on its key assumptions. Compare your result to what similar companies actually sold for. Not traded at—sold for. Transaction prices include control premiums and synergies that market multiples don't always capture. If your DCF says the company is worth twice what comparable recent deals paid, you need to explain why before anyone will take the number seriously. Document every assumption with a source or a clear rationale. "Based on industry standard" is not documentation. "Based on Gartner FY2024 SaaS margin survey, p. 47" is. When I hand a valuation to a client, the assumption sheet usually takes more time to assemble than the model itself because that's where the credibility lives.