Why Most Small Business Valuations Are Wrong Before You Even Start
The biggest mistake people make when doing a Valuation Of A Small Business is starting with the numbers instead of understanding what the business actually is. I watched a guy spend three weeks building aDCF model for a family-owned landscaping company that ran on owner-instigated contracts and seasonal cash flow. The model was technically perfect. It was also completely useless because the moment the owner retired, revenue dropped roughly forty percent within six months. You can't discount cash flows that don't exist. Before you open any spreadsheet, write down what the business does on a single sentence. Who buys from them. How often they buy. What would have to break for the business to stop working. That last question matters more than anything else because it tells you whether you're valuing a real operation or just someone's paycheck. Small businesses fall into three categories and each one needs a different approach. Service businesses like accounting firms or consulting shops. Product businesses like retail or manufacturing. Hybrid businesses that do both. Most valuations fail because people try to apply a product business method to a service business or vice versa.
Three Methods That Actually Work
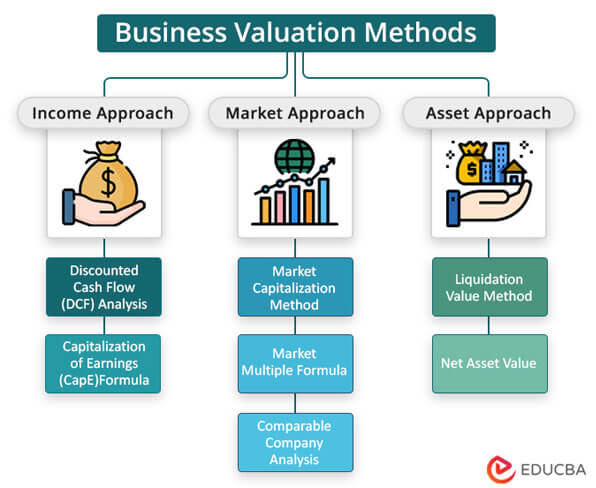
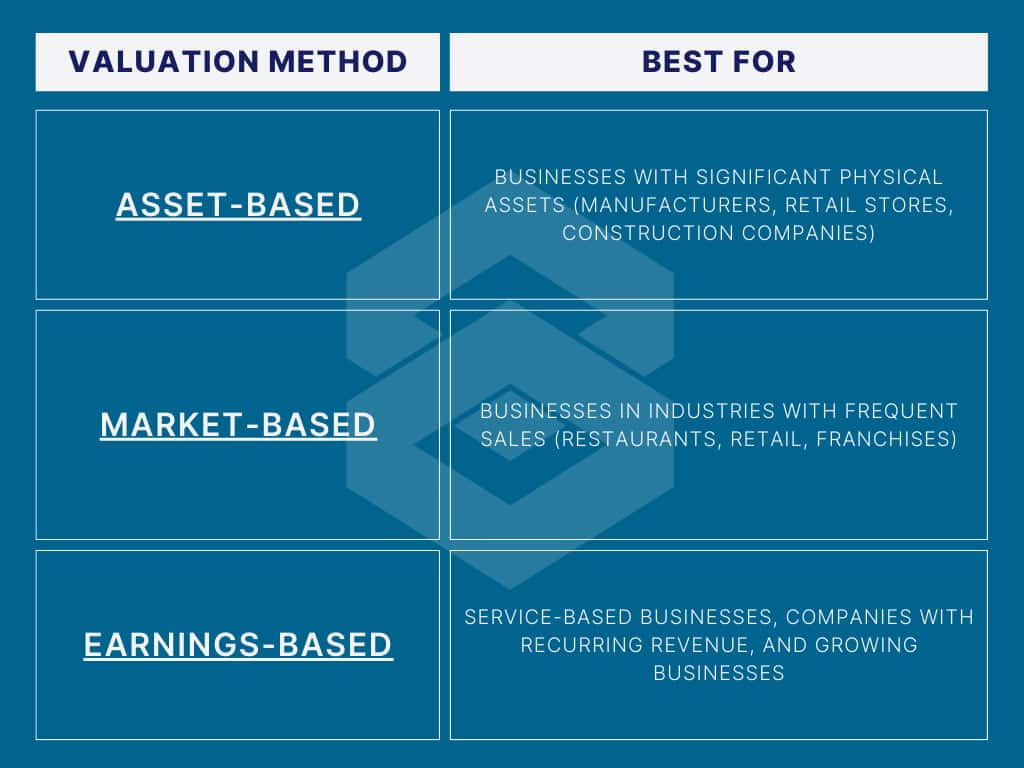
Asset-based valuation is the simplest method and honestly the most overlooked for small businesses. You take everything the business owns, subtract what it owes, and adjust the numbers to reflect what things would actually sell for, not what they're recorded at on the books. A delivery van might be worth forty thousand dollars on the balance sheet after depreciation. In reality, a used truck like that moves for maybe eighteen thousand at auction. Inventory gets trickier. Expired product, obsolete parts, and slow-moving stock need to be written down to zero or near-zero. I learned this the hard way valuing a small hardware store where the books showed two hundred thousand dollars in inventory. About thirty percent of it hadn't moved in three years. The buyer paid pennies on the dollar for that portion. Market-based valuation looks at what similar businesses have actually sold for. This is where most people get stuck because clean data is hard to find. Publubiz, BizBuySell, and various industry-specific brokers list asking prices, not sale prices. Asking prices are typically ten to twenty percent above what businesses actually sell for. Better sources include the IRS transaction databases for business sales over a certain threshold, industry associations that publish periodic surveys, and working with a business broker who can pull actual comparable sales data. For a local restaurant, you might find that establishments in your area sell for somewhere between two and four times seller's discretionary earnings. The range is wide because location, lease terms, and equipment condition swing things dramatically. Income-based valuation is what most people reach for and what they mess up the most. The SDE method is standard for smaller businesses, typically those under five million in revenue. You take the total revenue, subtract all operating expenses including a fair market salary for the owner if they were replaced, and you get the discretionary earnings number. Then you multiply it by an industry standard multiple. The multiple is where everything falls apart because people grab whatever number they find online without adjusting for risk.
The Multiple Problem Nobody Talks About
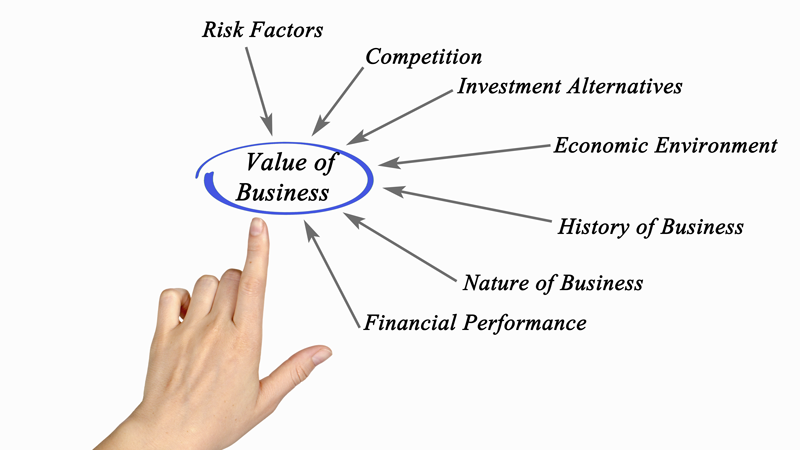
Online calculators love to say small businesses sell for two to four times earnings. That is a starting point, not an answer. The actual multiple depends on at least seven factors that most valuation guides ignore. Customer concentration is the first one. If the top three customers account for more than forty percent of revenue, the multiple drops significantly. Growth trajectory matters next. A business growing at fifteen percent annually commands a higher multiple than one flatlining or declining, even if current earnings look identical. Owner dependency is another critical factor. If the business relies on the owner for key relationships, specialized knowledge, or daily operations that no one else can handle, buyers will discount the value because they're buying a job, not a business. I worked on a valuation for a custom cabinet shop where the owner personally maintained relationships with three major general contractors. Those contracts generated sixty percent of revenue and had never been documented or transferred to anyone else. The book value suggested a twelve million dollar business. The realistic market value closer to six million because a buyer would need to rebuild those relationships from scratch. The workaround was to qualify the contract relationships, document the history, and show evidence that key contacts had engaged with other company employees. That didn't fix everything, but it pushed the multiple up from what would have been two point five times to closer to three point two.
Get the Full Details

What the Books Actually Hide
Small business financial statements are rarely accurate enough for valuation work. Common issues include personal expenses run through the business, revenue recognized when invoices are sent instead of when payment is received, and expense categorization that changes from year to year making trends impossible to read. Before doing any valuation, you need to normalize the financials. This means going through every line item and making adjustments that reflect the true economic picture. Add back expenses that are personal to the owner, one-time costs that won't recur, and owner compensation that's above or below market rate. Subtract expenses that will continue under new ownership but were missing from the reported numbers. The goal is to produce a set of adjusted financials that any reasonable buyer would accept as the baseline. This process usually takes two to four hours for a small business with clean records. It can take two to three days if the books are messy, which is more common than you'd think.
When Valuation Breaks Down Completely
Some businesses simply cannot be valued using standard methods. Startups without revenue are guessing games. Highly specialized niche businesses with no comparables have no market data to reference. Businesses in industries undergoing disruption need heavy discounts applied because historical performance predicts future results poorly. I valued a small print shop last year that had been profitable for eight years. The owner wanted eight million. Digital disruption had eliminated roughly sixty percent of their addressable market in two years, and their revenue was declining at twenty percent annually. Standard methods suggested a value around three million at best, and that was being generous because the equipment was twenty years old and needed replacement. The owner couldn't accept it. They kept listing at inflated prices for another year and eventually sold for less than half of what they originally wanted. Sometimes the best move is to exit before the numbers deteriorate further rather than waiting for a better offer that won't exist. Take the three methods, apply reasonable adjustments to each, and look for where they converge. If asset-based value says five million, market comparables suggest four to six million, and income-based valuation lands at four point five million, your best estimate sits around four and a half to five million. Don't present a single number. Present a range and explain what assumptions drive the high end versus the low end. Buyers and sellers both understand ranges better than precise figures because ranges force everyone to think about risk. The Valuation Of A Small Business process is fundamentally about translating a messy, living operation into a number that two strangers can agree to use as a starting point for negotiation. It's never going to be perfectly accurate. The best valuations acknowledge their own uncertainty and make it explicit rather than hiding behind false precision. A clean report with clear assumptions and a well-supported range beats a single suspiciously precise figure every time.