Estimating Your Retirement Costs Before They Become a Problem
Most people figure out how much they earn and where they want to live in retirement, but they rarely sit down and map out what it actually costs. Vanguard Retirement Expense Worksheet fills that gap by giving you a structured way to estimate annual spending across categories that matter. It is not a calculator that spits out a magic number. It is a planning scaffold. You put in your assumptions, see the categories add up, and then test whether your projected portfolio can cover them. I use it with clients about twice a year, and it has saved more than one person from running out of money at seventy-two.How the Vanguard Retirement Expense Worksheet Actually Works
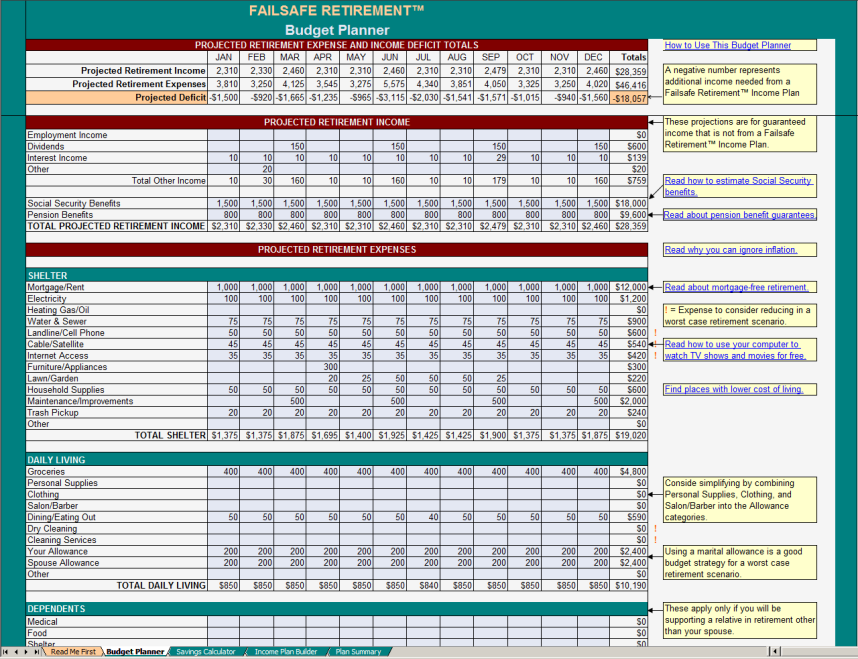
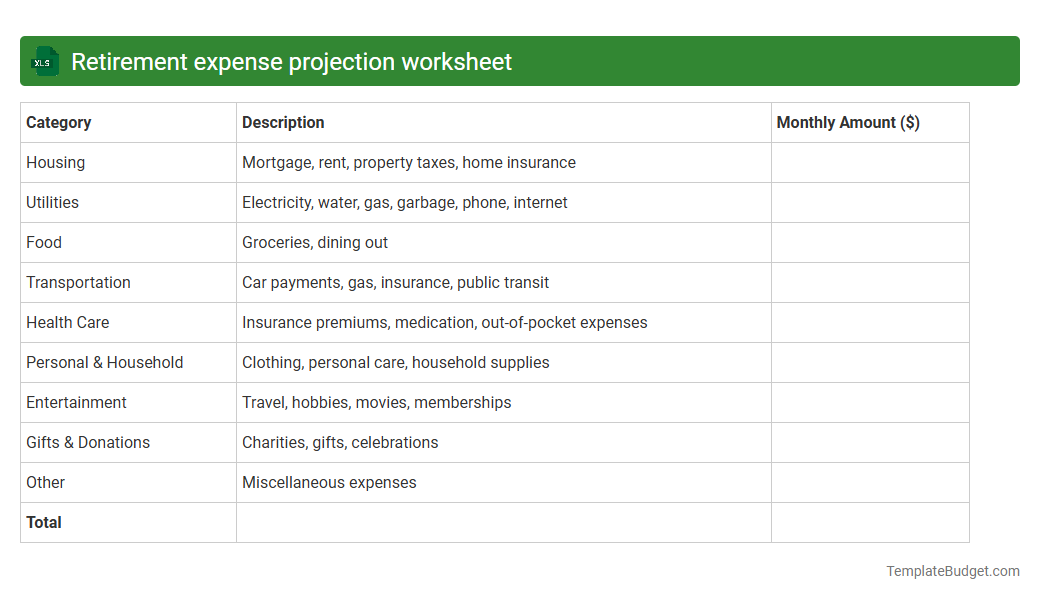
The worksheet breaks retirement expenses into categories like housing, healthcare, food, transportation, travel, and discretionary spending. You enter a monthly or annual figure for each line, and the tool sums them to a total. From there, you factor in sources of income such as Social Security, pensions, rental income, and withdrawals from accounts. The difference between your expenses and your income tells you how much you need to pull from your portfolio each year. That number is what matters. It drives everything else about sequence of returns risk, withdrawal strategy, and longevity planning. Here is the part most people miss. The worksheet does not automatically account for inflation. If you enter $4,000 a month for healthcare and do not build in a growth rate, your projection is stale the moment you write it down. Medicare premiums alone have been rising roughly 4 to 6 percent annually in recent years. Healthcare costs do not stay flat. I had a client who entered his current medical spending and never adjusted it. He ended up underestimating his total retirement expense by about twenty-three percent over a twenty-five year horizon. That gap changed his withdrawal strategy entirely. You also need to think about what happens when expenses shift. Most retirees spend differently in their early years than in their late years. The"flight to quality"phase tends to be heavier on travel and hobbies, while the later phase often carries more healthcare and in-home care costs. The worksheet lets you model multiple scenarios, but only if you create separate tabs or versions for different age ranges. I set up a baseline at age sixty-five, a second version at seventy-five, and a third at eighty-five. It takes about ten minutes once you get the template right, and it reveals whether your plan holds up or collapses somewhere in the middle.Quick walkthrough: Download the current version from Vanguard's website. Open it in Excel or Google Sheets. Enter your expected monthly expenses by category. Add your expected monthly income from Social Security, pensions, and other sources. Note the annual withdrawal gap. Then run a simple Monte Carlo or static withdrawal test using your portfolio assumptions to see if the gap is sustainable over your target timeline.
There are limitations worth stating plainly. The worksheet assumes a static lifestyle unless you manually adjust it. It does not model market downturns, tax law changes, or unexpected care needs. It treats your portfolio return as a constant if you do not layer in additional analysis. That makes it useful as a first pass, but dangerous if you treat the output as a guarantee. I have seen clients who hit a plausible-looking green light on the worksheet and then get wiped out by a sequence-of-returns event in their first three years of retirement. The tool did not cause that failure, but relying on it alone did. A better approach is to use the worksheet as a starting point and then stress-test it. Run the numbers with a 3 percent annual portfolio return instead of 5 percent. Add a healthcare spike of $200 a month starting at age seventy. Remove one source of income and see what breaks. If you want a more rigorous layer, plug the annual withdrawal requirement into a proper retirement calculator that models asset allocation, tax efficiency, and Monte Carlo probability. Vanguard itself offers a retirement income estimator that connects to the worksheet output if you want that next step. The worksheet is free, requires no account login to download, and works in both Excel and Google Sheets. It is most useful for people who are five to ten years from retirement or who have recently retired and want to validate whether their plan still makes sense. If you are twenty years out, it is still worth doing, but treat the numbers as directional rather than definitive.