How to Actually Run a Variance Analysis Without Losing Your Mind
Most people treat variance analysis like it is a quarterly chore. It is not. It is the single most useful thing in your month-end close, and the place where every hidden problem in your P&L shows up at once. If you are rolling your eyes already, good. That means you have been burned by a spreadsheet that looked clean on the surface but hid a mess underneath.
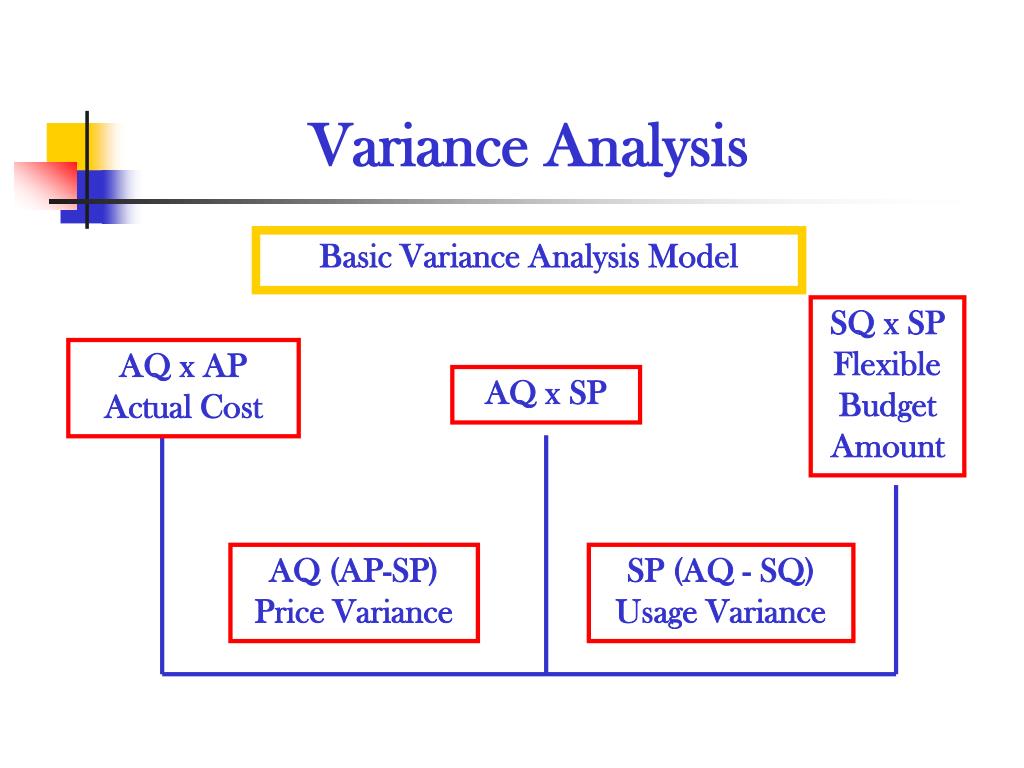
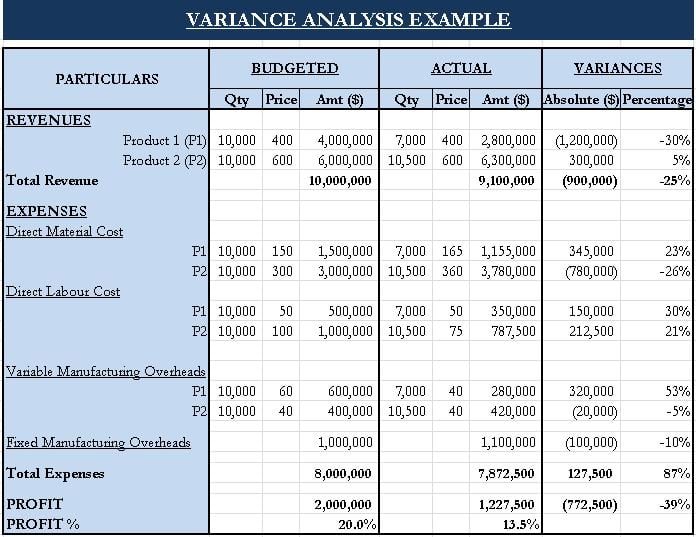
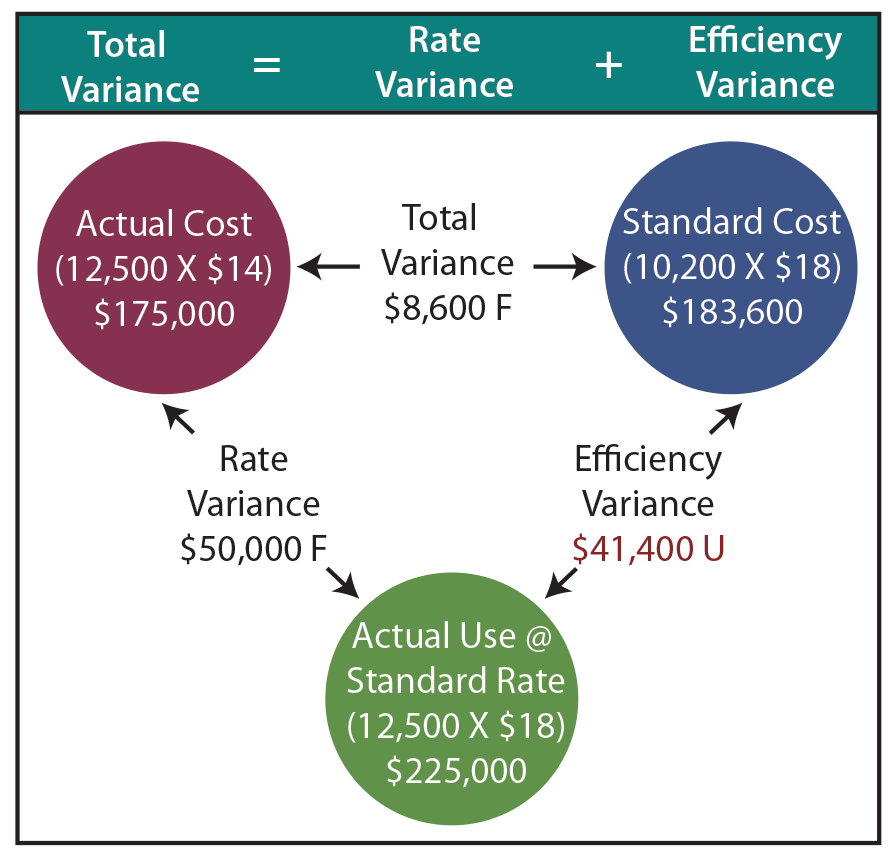
The basic mechanic is simple. You take a budget or standard, compare it to what actually happened, and isolate the difference. Revenue and cost come in several flavors of variance, and mixing them up is how you end up presenting numbers that sound right but mean nothing. The standard setup breaks cost variances into price (or rate) and efficiency (or volume). Revenue variances break into price and volume. Overhead adds another layer because it involves both spending and application rates.
Variance Analysis In Accounting becomes a habit once you stop treating it as a static report and start using it as a diagnostic tool. Here is how I set it up, what usually goes wrong, and where the method actually breaks down.
The Formula and the Framework
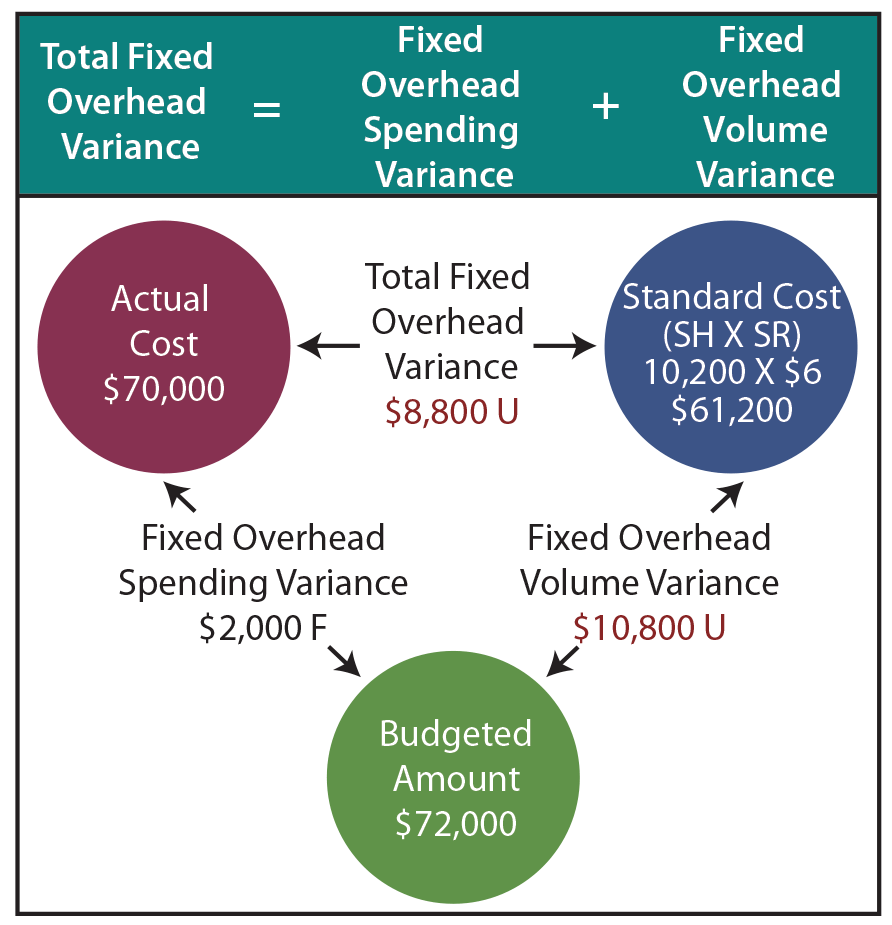
Start with the cost side. Direct material price variance equals actual quantity purchased times the difference between actual price and standard price. Direct material efficiency variance equals the difference between actual quantity used and standard quantity allowed for actual output, multiplied by the standard price. Labor follows the same pattern but uses hourly rates instead of unit prices. Variable overhead splits into a spending variance and an efficiency variance. Fixed overhead adds a budget variance and a volume variance.
Revenue variances use the same logic reversed. Sales price variance is actual quantity sold times the difference between actual selling price and standard selling price. Sales volume variance is the difference between actual and budgeted quantity sold, multiplied by the standard contribution margin.
I keep these formulas in a reference table rather than trusting memory. The references cut setup time on a new analysis from about forty-five minutes to roughly twelve minutes, assuming your data is already structured in a usable way.
A Real Example From Last Year
We ran a manufacturing line that produced a single product with a standard material cost of eight dollars per unit. Actual cost came in at nine dollars and twelve cents per unit. The raw difference looked alarming at first glance, but when we ran the price and efficiency splits, the price variance was only six cents per unit while the efficiency variance absorbed the rest. The issue was not a supplier price hike. It was scrap. We were using more material than the standard allowed because a feeding mechanism on the line was misaligned, causing rejects that we had to discard before packaging. Fixing the alignment brought the efficiency variance back to under one percent within three weeks. Without the split, we would have blamed the supplier and renegotiated a contract for no reason.
Common Pitfalls That Waste Time
The biggest mistake I see is using total variance without decomposing it. Total variance tells you there is a problem. It does not tell you where the problem lives. A ten percent unfavorable total variance could mean nothing if it is a timing issue, or it could mean a process is actively bleeding money. Decomposition is what separates noise from signal.
Another frequent error is mixing actual and standard quantities across different periods. When you pull data from multiple months without aligning the output base, the efficiency numbers become meaningless. I anchor every analysis to the actual output for the period, not the budgeted output, when calculating efficiency variances. Budgeted output belongs only in the volume variance section for fixed overhead.
A third issue is ignoring the mix. If your product line includes multiple SKUs with different material costs, blending them into a single standard hides real problems. I calculate variances by SKU whenever possible, even if it doubles the amount of work. The clarity is worth it.
Advanced Nuance: The Substitution Effect
Standard cost systems assume materials are interchangeable, but they rarely are. When a cheaper grade of steel replaced a more expensive one due to supply chain constraints, the raw material price variance showed a favorable result, which looked great in a boardroom presentation. However, the higher-grade steel was producing fewer defects. Once we isolated the substitution effect and calculated the true cost of increased rework, the net impact was unfavorable by about four percent. This kind of hidden trade-off shows up constantly when you are not tracking substitution separately.
Where Variance Analysis Fails Completely
The method breaks down when your standards are stale. I have seen companies run quarterly variance analyses with standards that were set eighteen months ago and never updated for material cost changes, process improvements, or product redesigns. The variances in those reports reflect outdated baselines rather than current operational issues. They are noise dressed up as insight.
Another failure point is high-mix, low-volume environments where overhead absorption rates become arbitrary. The allocation base you choose, whether it is direct labor hours, machine hours, or units produced, will distort the numbers. In these cases, activity-based costing provides a more accurate picture, though it requires significantly more data collection effort.
Variance analysis also struggles with service businesses where there is no physical output to measure efficiency against. The framework can be adapted using equivalent units or throughput metrics, but the results are less definitive and more open to interpretation.
My Practical Setup
I build the analysis in three layers. The first layer pulls raw data from the ERP or general ledger and matches it against standards. This is mostly automated if your chart of accounts is clean. The second layer calculates the variances by category. I use a pivot table structure that separates price, efficiency, mix, and volume components. The third layer is where the actual work happens. I review each significant variance, trace it to a source, and document whether it is controllable, transient, or structural.
Controllable variances get assigned to specific managers. Transient variances are flagged for monitoring. Structural variances are reported as known limitations in the standard system rather than hidden problems.
I usually run this process on day two or three of the close. If everything is well-organized, the mechanical calculation takes about fifteen to twenty minutes. The review and documentation step takes another thirty to forty-five minutes depending on the number of significant variances. A poorly organized setup with dirty data can stretch this to several hours.
Downloadable Template
I put together a file that handles the calculation layer automatically. It pulls actual and standard costs, computes price and efficiency variances for material, labor, and overhead, and flags anything above five percent for review. You can grab it here. Fill in your standards, plug in your actuals, and the rest runs itself.
The template assumes a standard absorption costing system. If you are using variable costing or process costing with equivalent units, you will need to adjust the calculations manually. No harm done, but it is worth noting upfront so you are not surprised when the numbers do not behave as expected.
.jpg "Variance Analysis Guide: 3 Examples in Budgets and Forecasts")