Understanding the vehicle lease vs buy calculator
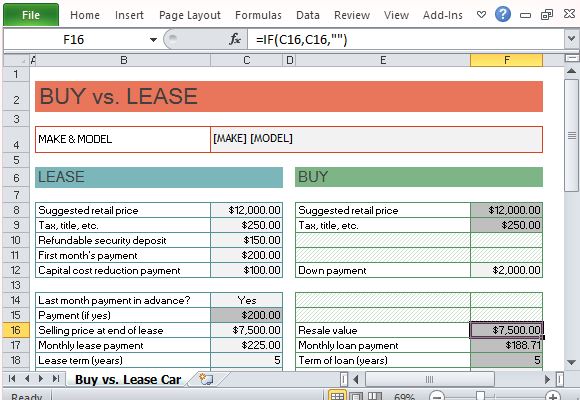
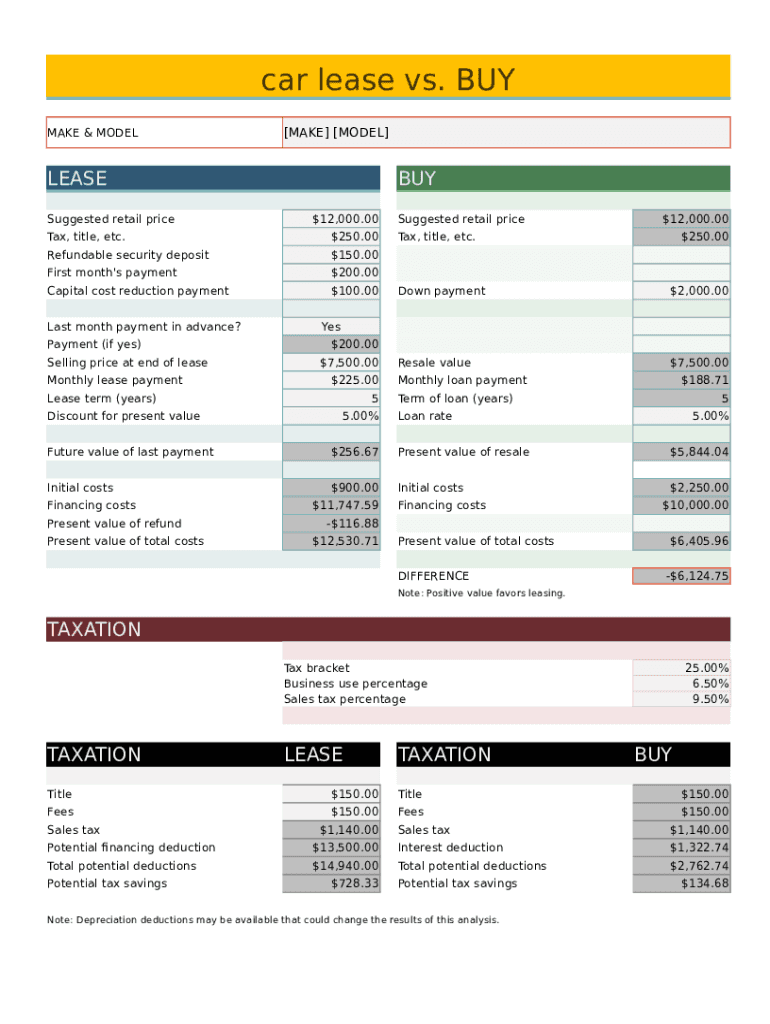
A Vehicle Lease Vs Buy Calculator is a tool that compares the total cost of leasing a car against purchasing one, either with financing or cash. It isn't a crystal ball. The output depends entirely on the inputs you feed it, and sloppy inputs will produce sloppy results. I've spent years working in auto finance, and the biggest problem I see isn't the calculator itself. It's people who treat the numbers as gospel without understanding what assumptions are hidden inside. Most free calculators online use a simplified formula. They take the vehicle's capitalized cost, the residual value at lease end, the money factor (which is just the lease equivalent of an interest rate), and the lease term. Then they calculate your monthly payment and total lease cost over the life of the contract. For the purchase side, they use a standard amortization formula with the loan amount, annual percentage rate, and term length. The difference between the two total costs is what the calculator presents as your savings or extra expense from choosing one route over the other.
How to use a Vehicle Lease Vs Buy Calculator effectively
Start by gathering real numbers, not estimates pulled from a dealership poster. You need the actual selling price the dealer is willing to accept, not the MSRP. The manufacturer suggested retail price is almost never the starting point for either a lease or a purchase negotiation. I once ran a comparison on a mid-range crossover where the calculator showed leasing would save roughly four thousand dollars over three years. That result evaporated the moment I plugged in the actual out-the-door price including documentation fees, destination charges, and sales tax applied to the full capitalized cost upfront. The lease deal was slightly more expensive after all numbers were real. Here's the practical workflow. Enter the negotiated purchase price as the capitalized cost. Input the residual value as a percentage of MSRP or as a dollar figure if your lease agreement provides one. Most manufacturers publish residual value tables, but these vary significantly by market and model year. The money factor should be converted to an equivalent annual interest rate by multiplying by 2400 if you want to compare it directly to a loan APR. A money factor of 0.00125 equals roughly a 3 percent APR. For the purchase side, enter your actual loan rate, not the promotional rate the dealer quoted in thirty seconds. Those promotional rates often require conditions you won't meet, like specific credit tiers or trade-in requirements. Set both scenarios to the same time horizon. A three-year lease compared against a six-year auto loan tells you nothing useful. The loan will have far more interest paid over its life, making purchase look artificially expensive. Match the terms. Match the down payment. Match everything you can control, then watch what changes.
The hidden factors that most calculators ignore
The standard Vehicle Lease Vs Buy Calculator will not account for maintenance costs, insurance differences, mileage overages, or early termination penalties. This is a significant gap. Leases often include maintenance packages, which reduces your out-of-pocket expense during the lease term. But they also impose mileage limits that typically range from ten thousand to fifteen thousand miles annually. If you drive twenty thousand miles per year regularly, leasing becomes quickly expensive due to excess mileage charges that run anywhere from fifteen to twenty-five cents per mile depending on the contract. Over three years at twenty thousand miles annually with a ten thousand mile allowance, you'd owe approximately nine thousand dollars in overage fees alone, which completely reverses any advantage the calculator showed you. Insurance is another variable. Leased vehicles usually require higher coverage levels, particularly comprehensive and collision with lower deductibles. Your monthly premium could be fifty to one hundred fifty dollars higher than if you owned the vehicle outright. Over three years that's six hundred to five thousand four hundred dollars, again swinging the math in unpredictable directions. I encountered a specific edge case that taught me how much these omissions matter. A client came to me with a calculator result showing a clear lease advantage on a luxury sedan. The numbers looked clean on paper. But when I dug into the lease agreement, I found a disposition fee of nine hundred ninety-five dollars due at the end of the lease if you didn't purchase the vehicle. The calculator didn't include this. I also discovered the lessee would be responsible for excessive wear and tear charges with no clear definition of what constituted excessive. I added both costs to the lease side, recalculated, and the purchase with financing became the cheaper option by approximately two thousand three hundred dollars over three years. The lesson here is straightforward. Always read the actual contract terms before trusting any calculator output.
Get the Full Details
Counter-intuitive situations where buying makes more sense
Most people assume leasing is always cheaper month to month and therefore cheaper overall. This is wrong in several common scenarios. If you plan to keep a vehicle for seven years or longer, purchasing is almost always the better financial decision. After the loan is paid off, you drive for free except for insurance, registration, and maintenance. A lease requires payment indefinitely. Over seven years, the payment gap alone can exceed twelve thousand dollars. Another situation where purchasing wins is when you have access to a low-interest loan or a manufacturer subsidy program. Some manufacturers offer subvented financing at rates as low as zero point nine percent APR for qualified buyers. At that rate, the cost of borrowing is minimal, and the ownership equity you build makes purchasing clearly superior. The calculator will reflect this correctly, but only if you enter the actual subsidized rate rather than the standard rate shown on the dealer's website. High-mileage drivers should also lean toward purchasing. Once you exceed your lease allowance consistently, the per-mile penalties compound every year. A purchase has no such penalty. You can drive as much as you want without writing a check to the leasing company.
When the calculator actually fails you
The Vehicle Lease Vs Buy Calculator breaks down in situations involving trade-ins, variable depreciation rates, or changing financial circumstances. If you're trading in an existing vehicle, the trade-in value affects both scenarios differently. In a purchase, the trade-in reduces your loan balance directly. In a lease, the trade-in may reduce your capitalized cost but doesn't work the same way. Some lessees roll trade-in equity into a new lease as a net capital cost reduction, while others lose that equity entirely if the trade-in value doesn't offset the new vehicle's price adequately. The calculator won't handle this nuance unless it's specifically designed for trade-in comparisons. Depreciation is another blind spot. Leases are priced based on expected residual values, which are forecasts. If the market shifts and actual residual values end up lower than projected, the leasing company absorbs that loss, not you. But if residual values are higher than projected, the lessor benefits. This asymmetry means the lease payment you agreed to might have been based on optimistic depreciation assumptions, and you're paying a premium for someone else's forecast error. My recommendation when the calculator gives ambiguous results is to build your own spreadsheet. Add rows for registration fees, estimated insurance premiums, maintenance costs beyond the warranty period, and any anticipated mileage overages. Use conservative estimates. If the purchase still looks cheaper after you include these realistic costs, go with the purchase. If the lease looks cheaper even with the added expenses, then the calculator was probably right and you have a legitimate reason to lease.