The Plumbing Nobody Talks About
Venture Capital Fund Accounting is fundamentally different from corporate accounting, and most people who try to set it up with a generic general ledger walk into a wall within six months. The problem is that a VC fund isn't one company. It's a collection of capital calls and distributions that flow in and out across a ten-year window, tied to multiple portfolio companies, each with its own valuation schedule, and each of those needs to be tracked separately for each limited partner's profit share. That structure doesn't fit neatly into QuickBooks or even most enterprise ERPs without significant modification. I spent three years doing this manually in spreadsheets before our firm finally moved to a dedicated fund accounting platform, and the thing I remember most clearly isn't the math. It's the waterfall distribution calculations. We had a fund with a catch-up provision that kicked in after the 7% preferred return hurdle, and somewhere between quarterly reporting cycle twelve and thirteen, I discovered that our spreadsheet had been compounding the management fee on committed capital instead of called capital since inception. That error inflated our Distributions to Partners by about 1.3% per quarter. It took us four days to reverse-calculate the impact across all LPs and draft the amendment notices.
Setting Up the Structure Correctly
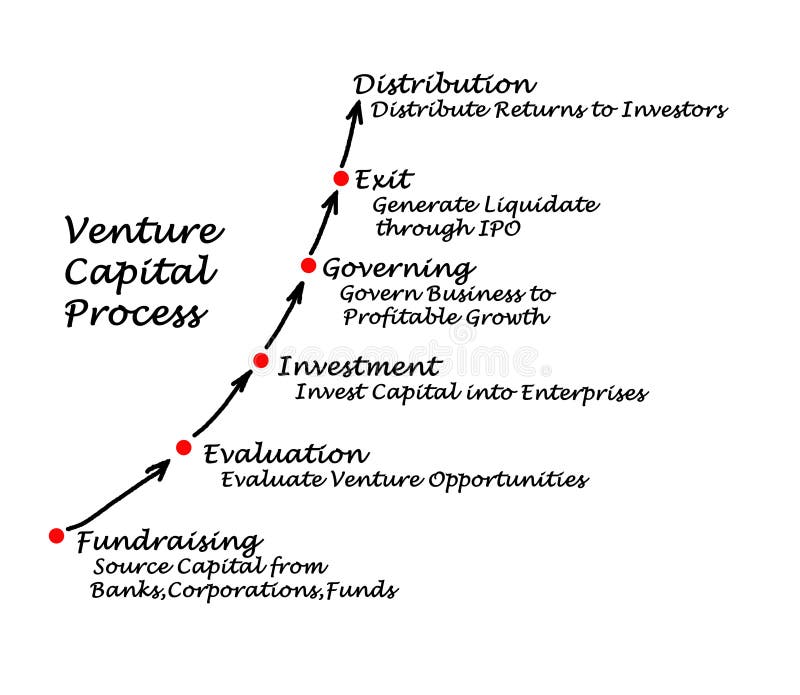
You need to think about Venture Capital Fund Accounting in terms of four parallel tracks that run simultaneously. The first is the fund-level books, where you track cash inflows from capital calls, management fee income, and distributions back to limited partners. The second is the portfolio company ledger, where each investment gets its own cost basis, valuation adjustments, and equity method or fair value accounting depending on ownership percentage and level of influence. The third is the partner-level subledger, which tracks each LP's capital account, their committed amount, their called amount to date, their share of income and losses, and their distributions received. The fourth is the waterfall, which governs how proceeds get split between the general partner and the limited partners across multiple tiers. The setup usually takes two to three weeks for a first-time implementation if you have clean capital call and distribution data, and about a day per quarter going forward for maintenance. The bottleneck is never the software. It's getting the portfolio companies to send their financials on time so you can mark those investments to fair value each quarter. Here is how I actually build the initial structure. First, create the fund entity with a chart of accounts that separates capital contributions from income and from management fees. Don't lump these together. Second, set up each portfolio company as a separate investment object with fields for acquisition date, cost basis, ownership percentage, valuation method, and last valuation date. Third, create the LP subledger with columns for commitment amount, contribution schedule, distribution watermarks, and clawback exposure. Fourth, build the waterfall calculation as a separate module that references the LP subledger and the fund-level cash account.
I use a hybrid approach now. The core tracking happens in a dedicated platform like eFront or Carta, but I keep a parallel spreadsheet for the waterfall calculations because the proprietary deal terms in our fund agreement don't map cleanly onto any off-the-shelf template. The spreadsheet feeds back into the platform quarterly for final validation. This adds maybe forty-five minutes per quarter but prevents the kind of silent drift that happens when you rely entirely on automated waterfalls with custom provisions.
Get the Full Details

The Valuation Problem
Valuing portfolio companies is where most fund accountants either cut corners or produce numbers that no auditor will accept. The standard approach is the 210A methodology, which means you're applying a set of recognized techniques to arrive at fair value. For Stage A through C investments where there's no public market, you typically use the recent transaction price method, the income approach with discounted cash flows, or the comparable company method. Each has a narrow window of when it's appropriate, and using the wrong one will get flagged in your audit. The recent transaction price method is the default for early-stage investments because it's straightforward. You take the price per share from the most recent funded round, adjust for any material events since that round closed, and that's your value. The adjustment part is where people get sloppy. A new term sheet with full ratchet anti-dilution is a material event. A single new board seat held by the lead investor is not. You need a documented rationale for every adjustment, and auditors will ask for that documentation during field work. For later-stage investments close to an IPO or acquisition, the market approach becomes more reliable. You look at trading multiples of comparable public companies or recent M&A transaction multiples and apply them to the portfolio company's financials. The issue here is timing. Public market multiples can swing wildly in a quarter, and if you value a portfolio company at a multiple that was valid in January but collapsed by March, your fund's net asset value will look volatile even though nothing fundamental changed in the company. I've seen firms smooth this by using a three-month average of comparable multiples, which reduces noise but introduces its own lag.
The income approach is the one that causes the most headaches. Discounted cash flow models require assumptions about growth rates, terminal values, discount rates, and capital structure that are essentially guesses dressed up as analysis. I use this method sparingly, only when there truly is no comparable transaction data and the company has stable, predictable revenue. When I do build a DCF, I document every assumption in a single source file and attach it to the quarterly valuation package. Auditors respect that transparency even when they disagree with the inputs. One thing that trips up almost everyone new to this: you need to value at the fund level, not just report what the portfolio companies report. A company might say its Series B round valued it at $50 million, but if that round was heavily discounted for the new investors and the existing cap table has conversion features that change the economics, your true economic exposure might be significantly different. Run the fully diluted equivalent share count through your capitalization table software and reconcile it against what the portfolio company reports. The discrepancy will tell you whether their valuation is being too aggressive or too conservative.
Waterfall Distributions and the Catch-Up Trap
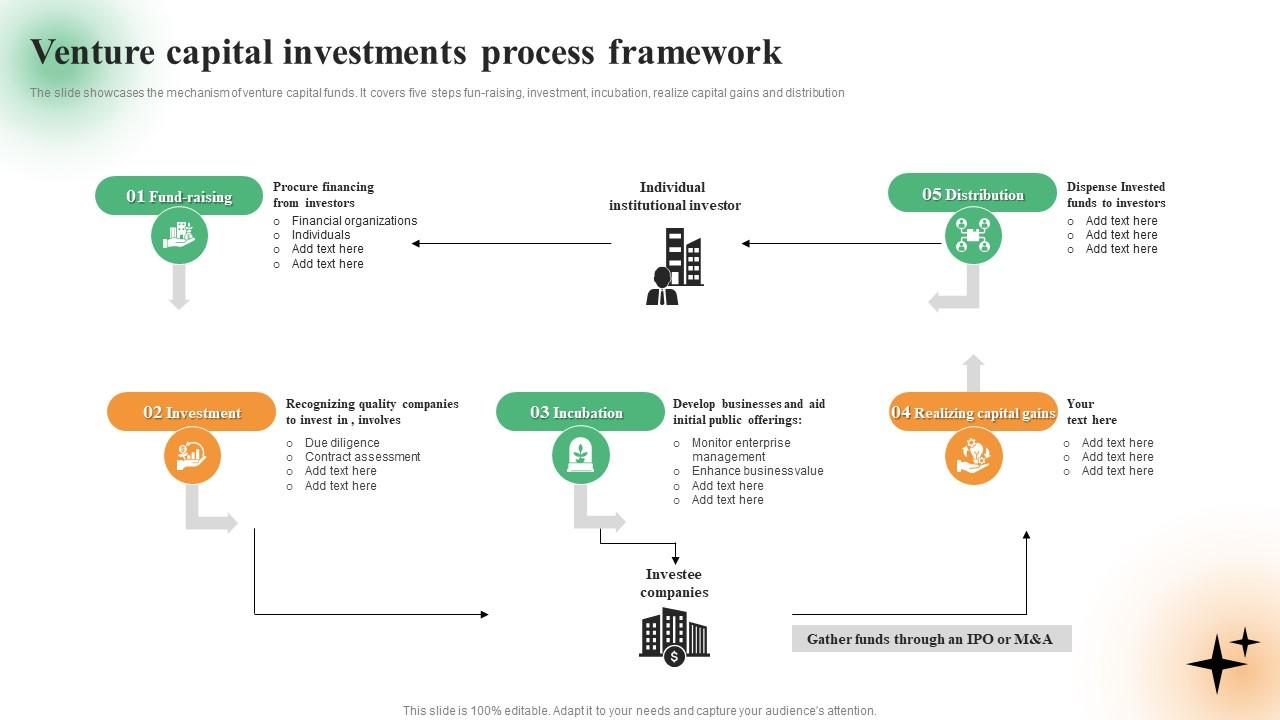
Waterfall distributions determine how exit proceeds get split between the general partner and limited partners, and this is where the actual money moves. Most funds use a three-tier structure: first, return capital to LPs until they've received back 100% of their committed contributions. Second, pay LPs a preferred return, usually 7 to 8% annually, compounded. Third, the catch-up provision kicks in, giving the GP a portion of subsequent distributions until the GP has received its promote, typically 20% of total profits. After that, the split follows the agreed ratio, commonly 80-20 in favor of LPs. The catch-up calculation is where I've seen the most errors. The catch-up is supposed to accelerate distributions to the GP so that once the preferred return hurdle is cleared, the GP ends up with its full promote percentage of total profits. But the formula assumes you're calculating on a total-fund basis, not deal-by-deal. Some funds use deal-by-deal waterfalls, which produce materially different outcomes and are generally unfavorable to LPs. You need to know which structure your fund agreement specifies and build the calculation accordingly. I've seen two funds with identical terms produce completely different GP promotes because one used overall and the other used deal-by-deal, and neither party caught it until the first major exit. Another detail that gets missed: the preferred return compounds on a quarterly basis, not annually, and it accrues from the date each capital call is made, not from the fund's inception date. If you calculate the preferred return from inception across the board, you'll understate the LP's hurdle for capital called late in the fund's life and overstate it for capital called early. This shifts profits toward the GP in one direction or the other depending on the timing mismatch.

For clawback protection, you need to model the worst-case scenario at signing. If an early exit generates a huge return that pushes the GP's promote above what it would be on an overall basis, the GP may owe money back to LPs when later deals underperform. Your accounting system should track cumulative GP promote paid versus cumulative GP promote entitled, and flag any positive balance that represents potential clawback exposure. I set this as a running quarterly metric in the dashboard so the CFO can see it before the annual audit comes knocking.
Common Pitfalls That Will Cost You
The first pitfall is mixing up committed capital with called capital in your fee calculations. Management fees are typically 2% of committed capital during the investment period and 2% of invested capital during the tail period, but the switch date is specified in the LPA. If you calculate fees on committed capital after the investment period closes, you're overcharging LPs. If you switch too early, you're undercharging and creating a revenue gap. Track this date explicitly and review it annually. The second pitfall is not tracking expenses at the fund level versus the portfolio company level. Fund-level expenses include audit fees, legal fees, board fees, and admin costs. Portfolio company expenses include board observer costs, watch committee fees, and follow-on diligence. These go into different buckets. Fund expenses reduce the fund's net return. Portfolio company expenses are typically borne by the company and don't affect the fund's P&L directly, though they may affect the company's cash position and therefore its valuation. Getting this wrong inflates or deflates your reported fund performance. The third pitfall is ignoring the tax implications of each transaction. Every capital call, distribution, and valuation adjustment can trigger taxable events for both the fund and the individual LPs, especially if the fund is structured as a partnership with international investors. Keep a parallel tax schedule alongside your accounting records. A single misplaced distribution classification can create a K-1 error that requires amended filings across multiple jurisdictions.
The fourth and most costly pitfall is relying on portfolio companies to value themselves. Companies will inflate their valuations to make their founders look good and to justify higher prices in future rounds. Cross-check their numbers against external data points: recent comparable raises in the same sector and stage, public comps, and any arm's-length transactions you're aware of. If a company reports a 40% step-up from its last round in a down market, that's a signal, not a fact.
Tools and What Actually Works
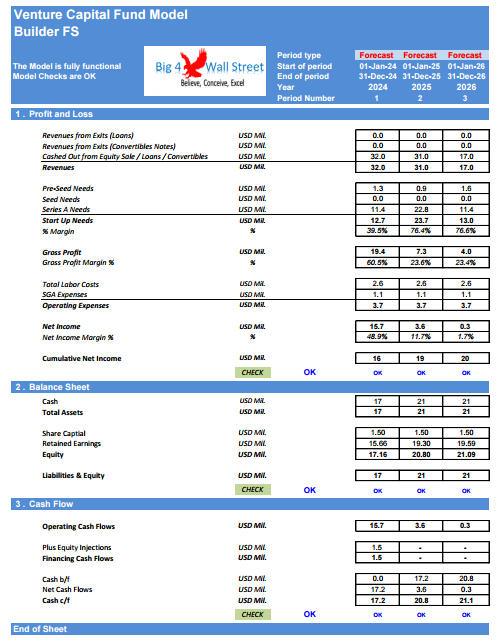
The dedicated platforms in this space are eFront, Carta, and Forge. eFront is the enterprise-grade option and handles complex fund structures well, but it costs roughly $15,000 to $30,000 annually per fund and requires a dedicated admin to operate it properly. Carta is cheaper at around $5,000 to $12,000 annually and has a much better onboarding experience, but it struggles with multi-tier waterfalls and custom LP agreements. Forge is focused more on secondary transactions and post-IPO holdings, so it's relevant if your fund holds late-stage positions or has a liquidation strategy that involves secondary sales. For smaller funds under $100 million in commitments, I've found that a well-built spreadsheet model combined with a basic subledger tool like Ledger or even a shared Airtable database can handle the work for the first five to seven years. The spreadsheet model should mirror the four-track structure I described above. The key is discipline in updating it. Quarterly valuation updates, monthly cash position reconciliation, and annual waterfall recalibration are the minimum cadence. Anything less and your numbers will quietly diverge from reality. If you're choosing a platform, insist on a live demo with your actual fund's capital call schedule and a sample portfolio company. Don't let the sales team run you through a canned demo with toy data. Feed your real data into their sandbox and watch where it breaks. The platform that handles your catch-up calculation without requiring a workaround is the one you should buy.
The Administrative Reality
Quarterly reporting for a mid-size venture fund with fifteen to twenty portfolio companies takes approximately 60 to 80 hours of focused work spread across the quarter. The bulk of that time isn't accounting. It's chasing portfolio companies for financial statements, reconciling valuation inputs, and preparing the LP reporting package. The actual journal entries and calculations, once the data is in front of you, take maybe four to six hours per quarter. Annual audit prep adds another 40 to 60 hours. Auditors will want to see your valuation methodology documentation, your capital call and distribution schedules, your waterfall calculations with supporting math, and your expense allocation methodology. Organize these documents in a single data room before the auditor arrives. I start this process in September for a December year-end, which gives me time to fix issues before the auditors show up in November. The biggest efficiency gain I made was automating the capital call and distribution schedule import. Instead of manually entering each call and distribution, I set up a CSV import template that the fund administrator populates from the commitment letters and bank statements. The template maps directly to the subledger fields, and the import takes about ten minutes instead of the two hours it used to take. The same applies to the valuation data import from our cap table software. Automate the boring parts so you can spend your time on the calculations that actually matter.
Venture Capital Fund Accounting is not a complex subject in theory. The complexity comes from the volume of edge cases, the pressure of tight reporting deadlines, and the fact that every fund agreement is slightly different. The people who do this well aren't the ones who know the most accounting standards. They're the ones who build systems that catch errors before they compound, who document every assumption, and who treat their LP reporting as a product that needs to be accurate, on time, and auditable.