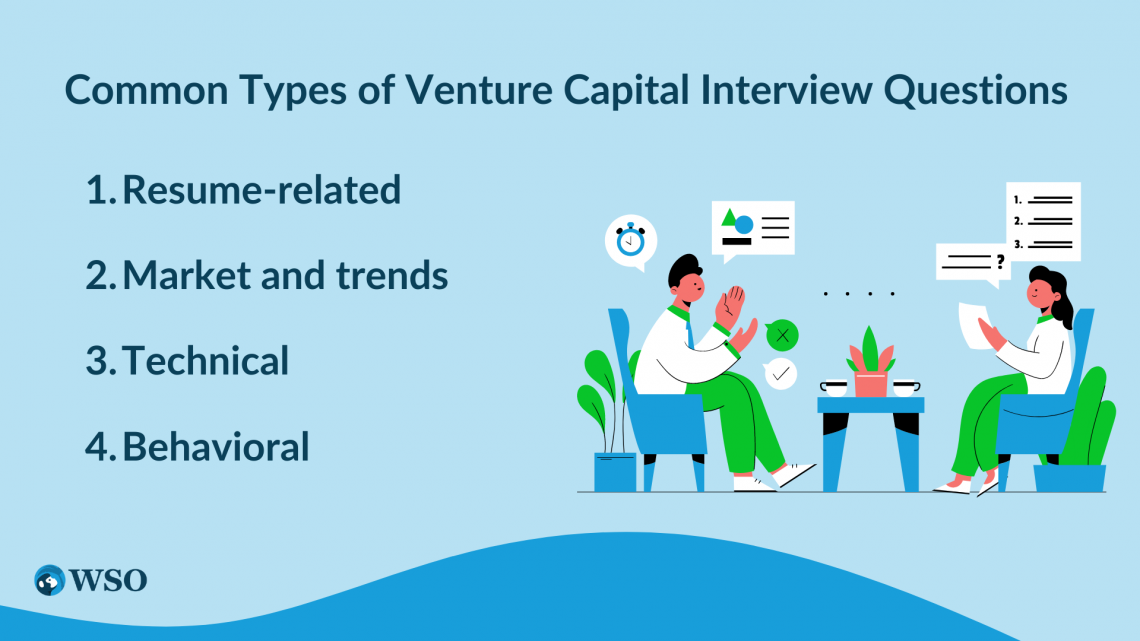
What People Actually Mean When They Say "Prepare for a VC Interview"
Most candidates walk into these conversations thinking they need to memorize valuation formulas or have three bulletproof case studies ready. That's only half the picture, and honestly, it's usually the part that doesn't matter in the actual room. A proper Venture Capital Interview Guide needs to address the fact that different firms ask radically different questions. A seed-stage fund in London will drill you on founder dynamics and product-market fit signals. A Series B firm in San Francisco is more likely to throw a market-sizing problem at you and watch how you handle pressure. The preparation has to match the actual format, not some generic template you found on a careers page. Here's how I've seen this play out across roughly a decade of running hiring processes at early-stage funds.
How to Approach a Venture Capital Interview Guide
Start by mapping the firm's actual investment thesis. Read their last ten portfolio announcements, the blog posts from their partners, and any public thesis documents. If a firm consistently writes about climate tech and deep infrastructure, don't prepare a consumer app case study. The mismatch is immediately obvious, and candidates who make it are usually filtered out before the second round. The next step is building a working knowledge of deal evaluation frameworks without turning them into a recitation. LBO math, cap table dynamics, dilution curves, and liquidation preferences are tools you need to speak fluently, not concepts you need to define on a whiteboard. Most interviewers already know the candidate can run a model. What they're testing is whether the candidate can use those numbers to make a call. I structure my own interview processes around three segments that usually total about ninety minutes. The first is a live case study where I give the candidate a one-page summary of a hypothetical startup and ask them to walk through an investment recommendation. The second is a rapid-fire round of questions that tests their ability to think out loud about market sizing, competitive moats, and timing. The third is where we talk about their actual points of view—what they want to invest in, why they're skeptical about common trends, and what they'd do differently from the current fund.
The case study portion is where most candidates fail, and not for the reasons they expect. They build elaborate financial models and then produce a vague recommendation at the end. Or they produce a strong recommendation but can't articulate which single assumption their whole argument depends on. I always ask the same question after they finish: "What would change your mind?" If they can't answer that within thirty seconds, the case study was mostly noise.
Get the Full Details

What the Venture Capital Interview Guide Actually Tests
Beyond the surface-level knowledge, these interviews measure three things that are nearly impossible to fake under time pressure. First is intellectual honesty. Can the candidate say "I don't know" without immediately covering it with jargon? Second is communication clarity. Can they explain a complex idea to someone who has never worked in that sector? Third is deal judgment. Do they have genuine opinions about businesses, or are they reciting talking points? I once had a candidate who spent forty-five minutes building an impressive three-statement model for a B2B SaaS company. When I asked what the single biggest risk to the investment was, she started listing market size, competition, and execution risk. I pushed back and asked which one would kill the deal first. She didn't have an answer. The model was competent. The judgment was absent. That's the gap most preparation materials don't address. They teach you how to build the model. They don't teach you what to do when the numbers point in two different directions.
Specific Scenarios and How to Handle Them
Market sizing questions come up constantly. You'll get something like "estimate the annual revenue of all independent coffee shops in Greater London." The correct approach isn't to start multiplying numbers immediately. It's to state your assumptions out loud, show the top-down and bottom-up calculations, and then reconcile them if they diverge. I've seen candidates lose points not for getting the number wrong—nobody expects the right answer—but for hiding their methodology behind a wall of confident-sounding arithmetic. Competitive analysis questions are different. You'll be asked to map a market and identify positions. The trap here is creating a matrix that looks comprehensive but actually says nothing useful. A good response identifies the two or three real competitors, explains why they're positioned differently, and states clearly which competitor the startup should avoid competing against directly. Anything more than that is usually overkill for an interview setting. There's also the portfolio construction question, which surfaces in later interview rounds. "If you had three checks to allocate this year, what would you invest in and why?" This is where I see the most variation in quality. Weak answers list three random sectors. Strong answers tie the three investments together through a coherent thesis, even if the sectors differ. The best candidates explain what they're choosing not to invest in and why that's as important as the selection itself.
What I Learned the Hard Way During My Own Hiring Process
A few years ago I was running a interview loop where I kept asking candidates to walk through a hypothetical deal from sourcing to exit. Almost everyone did it competently on paper. The problem emerged when I changed the conditions mid-pitch. I'd interrupt with something like "the founding team just lost their CTO" or "a larger competitor has just raised twice your target check size." The candidates who could adjust their thesis in real time were the ones who got offers. The ones who froze or tried to pretend the new information didn't exist didn't make it past the second round. That taught me to build dynamic elements into every interview from the start. A static case study tells you how someone thinks on a Tuesday afternoon. A shifting one tells you how they think when something goes wrong, which is the actual job.
Common Mistakes That Derail Candidates
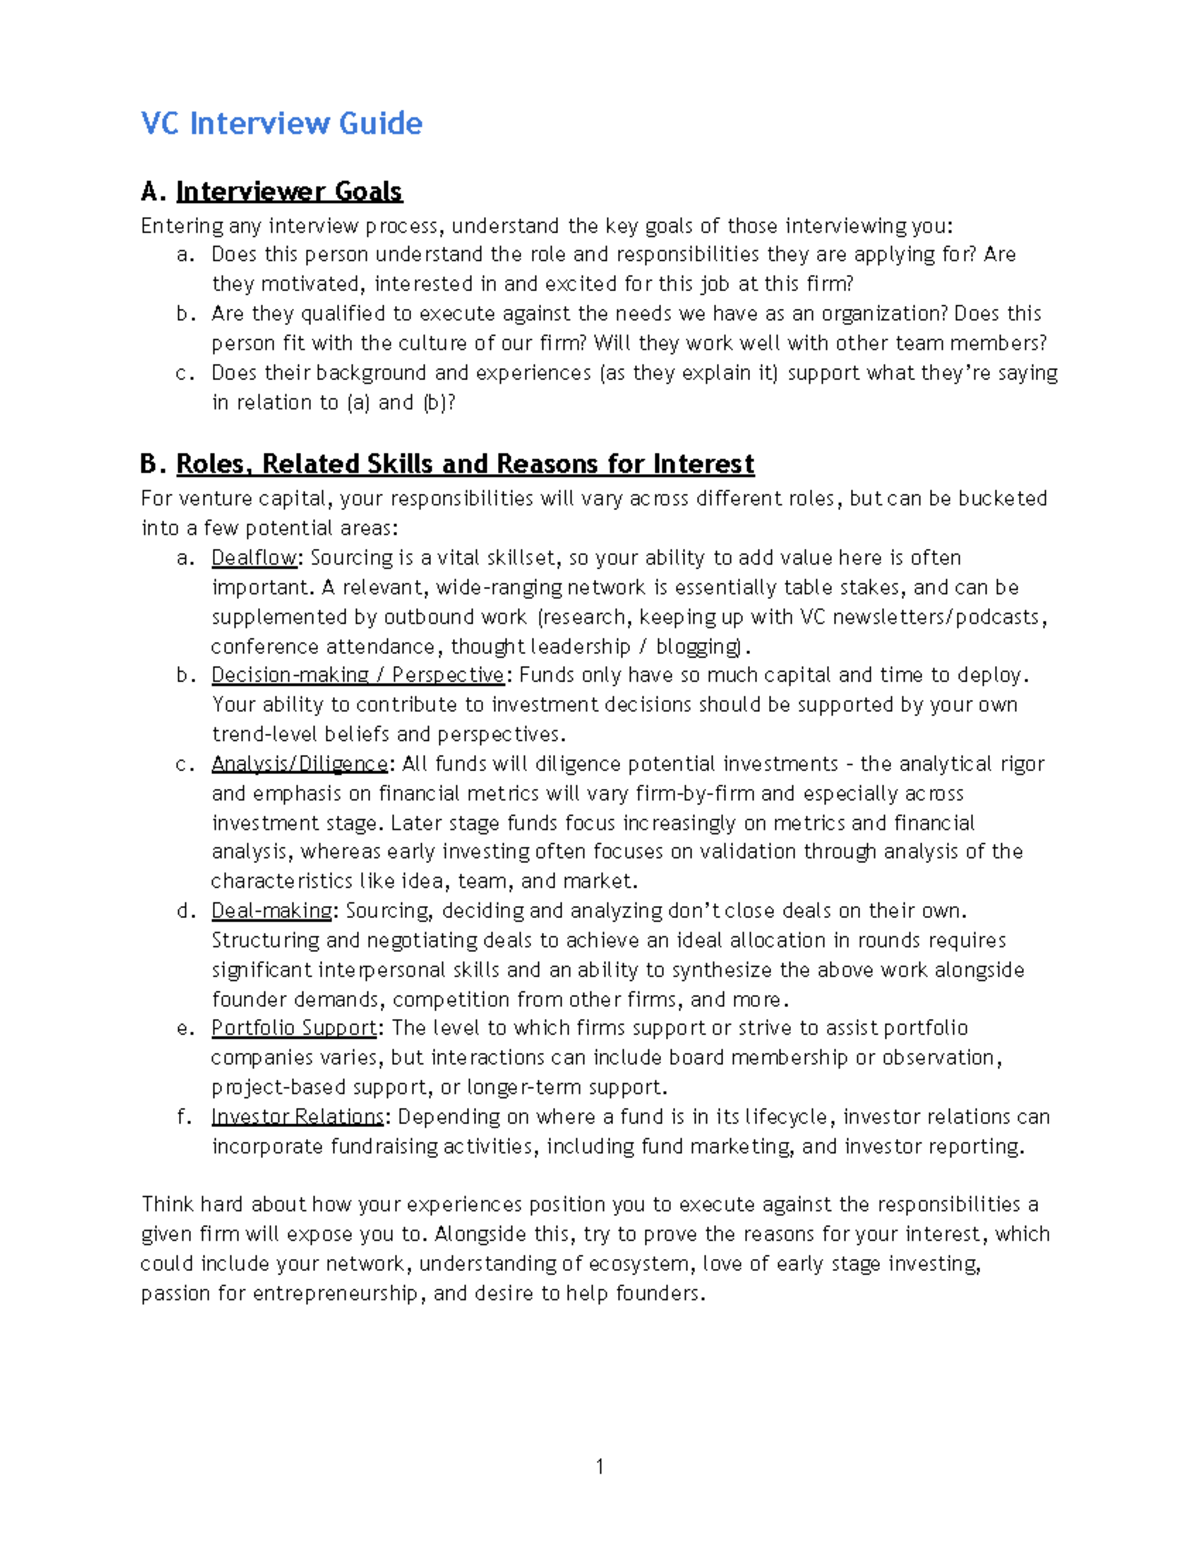
Over-indexing on quantitative skills at the expense of qualitative reasoning is the most frequent error. I've watched strong financiers get rejected from venture roles because they couldn't articulate a point of view about why a particular founder would succeed. Numbers don't win deals in seed-stage investing. Conviction does, and conviction requires something beyond a spreadsheet. Another mistake is rehearsing answers instead of practicing thinking. When someone delivers a perfectly memorized response about market trends or valuation multiples, it sounds polished until the interviewer asks a follow-up that isn't in their script. The candidate then visibly panics. It's better to practice improvising through uncomfortable questions than to perfect six prepared responses. Some candidates also fall into the trap of trying to impress with jargon. Terms like "unit economics," "network effects," and "coefficient of retention" mean nothing if they're dropped in without context or demonstrated understanding. Use the language when it's genuinely useful. Don't wear it like armor.
What This Approach Misses
Any structured interview guide has limitations that no amount of preparation can fully overcome. The most significant is the time compression problem. A real investment decision takes weeks of due diligence, founder conversations, reference checks, and internal debate. An interview compresses that into an hour. The format inherently rewards people who are good at performing under time pressure, which is a useful skill but not a perfect proxy for how someone will evaluate deals over months. There's also cultural bias baked into almost every process, deliberately or not. Interviewers tend to gravitate toward candidates who think similarly to them, come from similar backgrounds, or display the same communication style. This isn't a new problem in venture capital, and no interview guide eliminates it. The best you can do is be aware of it and actively look for signal in people who don't fit the expected mold. If you're preparing for an interview and the firm uses a case study format as its primary filter, consider whether that's the right signal for the role you're applying to. A firm that over-relies on case studies may be evaluating for a different skill set than what the job actually requires. That's worth flagging during your own evaluation of them.
Downloadable Venture Capital Interview Guide
I put together a one-page reference sheet that covers the core frameworks, typical question types, and the adjustment prompts I use during interviews. It includes market sizing templates, a competitive positioning checklist, and a list of follow-up questions that expose weak reasoning. You can find it attached to this thread, and I update it whenever the market shifts in a way that changes what good candidates look like. Last quarter's revision focused on how AI-native startups are changing the way we evaluate early-stage deals, which isn't covered in most existing guides. Use it as a starting point, not a script. The value is in understanding the structure of the thinking, not in memorizing specific answers. If you can walk into a room and think clearly about an unfamiliar business under time pressure, you're in a better position than someone who has prepared a perfect answer to a question that was never going to come up.