How Verification Of Income Actually Works In Practice
Verification of income is the process of confirming that a person's stated earnings are real and accurate. Lenders do it before approving loans. Landlords do it before signing lease agreements. Insurance companies check it when underwriting policies. The concept is straightforward, but the execution is where things get messy. I've sat through more compliance calls than I care to count, watching applicants try to explain why their W-2 doesn't match their bank deposits. The gap between what someone says they earn and what documentation proves they earn is where most failures happen.
The Standard Verification Of Income Methods
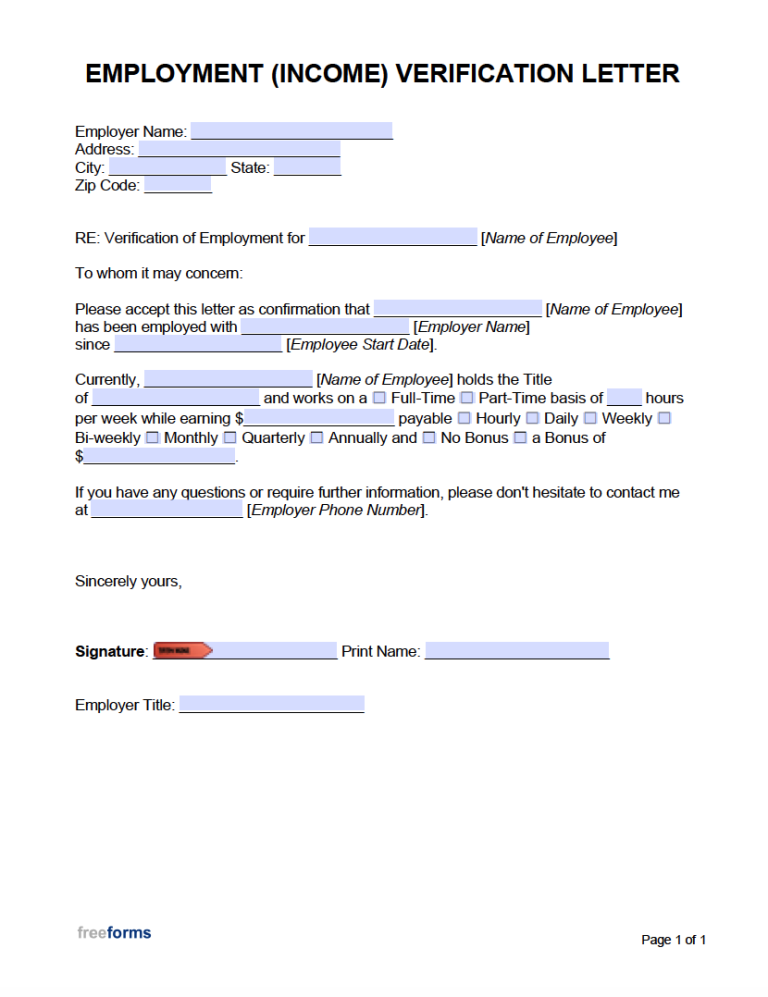
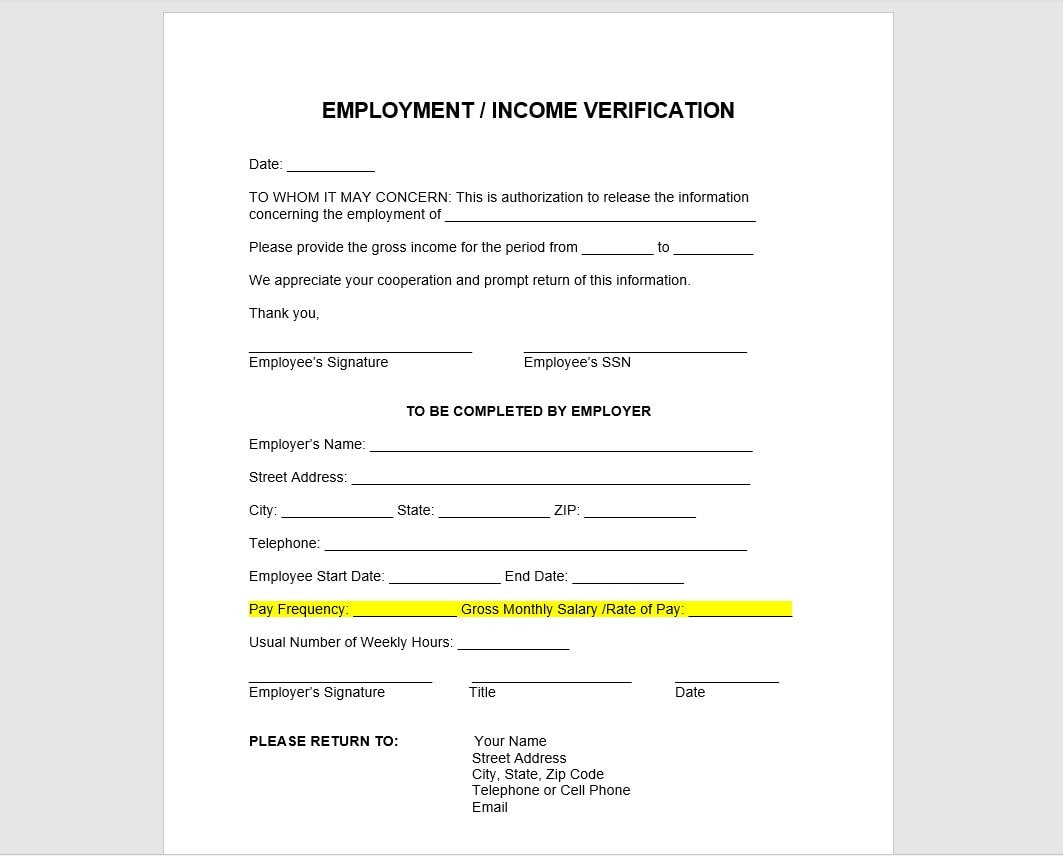
There are several established ways to verify income, and each has its own failure modes. Pay stubs are the most common first step. They show recent earnings, year-to-date totals, and deductions. But pay stubs are easy to forge and even easier to misunderstand. A gross amount of $4,500 biweekly does not mean the same thing as a net deposit of $2,800 into a checking account. Underwriters know this and usually ask for both. Tax returns, specifically the 1040 with all schedules, give a fuller picture. They show annual income across all sources. But tax returns lag by at least a year. If someone changed jobs in March and their most recent return reflects December employment, the document is essentially useless for current verification. I had a commercial loan application where the borrower had doubled their income through a promotion six months prior, and the underwriter nearly rejected the deal because the tax return told an outdated story. The fix was pulling a year-to-date profit and loss statement from their accounting software and cross-referencing it with twelve months of bank statements. That took about twenty minutes and resolved the issue entirely. Employer verification through direct contact is the traditional route. A lender calls the payroll department or sends a form that gets signed by HR. This method is considered the gold standard because it comes from a neutral third party. The problem is that many employers will only confirm employment dates and job titles, not actual salary figures, citing internal policy. You end up circling back to pay stubs and tax returns anyway. The callback typically takes two to three business days, sometimes longer if the employer's HR department is understaffed.
Digital verification services have changed the landscape considerably. Platforms like The Work Number (also called Equifax Workforce Solutions) allow instant income verification through automated data feeds. Employers upload payroll data, and lenders can pull real-time verification without making a phone call. This cuts verification time from days to minutes in most cases. However, the data quality depends entirely on whether the employer reports accurately and consistently. I've seen cases where a small business owner manually entered payroll data into The Work Number and made arithmetic errors that flagged the entire application for manual review. Digital verification is fast but not infallible. Bank statement analysis is increasingly common, especially for self-employed borrowers or those with non-traditional income streams. Instead of relying on documents people produce, the lender looks at actual cash flow. Twelve to twenty-four months of statements get run through analysis software that categorizes deposits, identifies patterns, and calculates average monthly income. This approach reveals inconsistencies that paper documents hide. A borrower might show steady W-2 income on paper but have irregular deposits suggesting secondary employment that wasn't reported. Or they might show large periodic deposits that are actually loan proceeds rather than earned income. The software flags these discrepancies for manual review.
Get the Full Details
What People Get Wrong About Income Verification
The biggest mistake I see is treating verification as a one-time event. Income is dynamic. A salaried employee who starts receiving overtime, a commission-based worker whose quota changed mid-year, a freelancer who lost a major client—these all affect verifiable income and they happen constantly. Verification at application time is a snapshot, not a guarantee. Many borrowers don't realize that if their income changes significantly before closing, the lender may require updated documentation even if the initial verification passed without issues. Another common error is misunderstanding what counts as income. Child support payments, Social Security benefits, alimony, rental income, and pension distributions all count as qualifying income in many lending scenarios, but they each have different documentation requirements. Some income types require two years of history. Others need proof of continuing likelihood. A borrower once tried to use a one-time legal settlement as primary income for a mortgage application. The settlement check was real, the bank statement showed the deposit, but settlement income is generally considered non-recurring and cannot support a long-term debt obligation. The application had to be restructured around a different income source entirely. Self-employed verification deserves special attention because it's where most applications break down. Profit and loss statements are useful but unverified. Bank deposits conflate revenue with personal deposits and loan proceeds. Tax returns show deductions that may not reflect current operations. The standard approach for self-employed verification is two years of tax returns plus year-to-date financial statements, and even then, underwriters tend to use the lower of gross income or adjusted gross income after adding back certain deductions. This calculation routinely surprises people who believe their business income is higher than it actually qualifies as on paper.
The Gaps and Limitations You Need to Know About
Income verification has real blind spots. Gig economy workers with income spread across multiple platforms are increasingly common, and traditional verification infrastructure wasn't built for that pattern. A rideshare driver might earn legitimate income from three different apps with no single W-2 or consistent pay stub. The Work Number doesn't capture this type of income at all. Bank statement analysis is the fallback, but it requires more time and produces more questions than answers when the deposit patterns are fragmented. Cash-based employment remains another hard problem. Construction workers, restaurant staff, domestic employees—these populations often receive partial or full payment in cash. There is no digital trail. Verification typically relies on self-attestation supplemented by bank deposits and sometimes employer affidavits, which carries less weight with underwriters. Some lenders simply won't work with this income profile. Others require a longer track record and more conservative debt-to-income calculations. International income adds its own complications. A borrower earning in euros or yen needs currency conversion documented, and the verification process depends on whether the foreign employer cooperates with US-based verification requests. Some countries have different employment record-keeping standards. Documentation that looks legitimate in one jurisdiction may not meet US underwriting requirements. I handled a case where a borrower provided an employment letter from a UK-based company that looked properly formatted but didn't include the specific information US lenders require, like annual salary figure and employment type classification. We had to request a revised letter and wait an additional five business days for it to arrive.
The verification process also struggles with income volatility. A consultant who billed $120,000 last year but only $45,000 this year presents a genuine underwriting dilemma. Averaging the two years smooths the picture but may overstate current ability to repay. Using only the most recent year understates historical earning capacity. Each lender has its own policy on handling variable income, and the differences between lenders on this point can be significant. Shopping around matters more for borderline cases than most people realize.
Preparing For A Smooth Verification Process
If you're about to go through income verification, organize your documents before you start. Having everything in one place isn't just convenient—it prevents mistakes that happen when you're scrambling to find a pay stub from three months ago while someone is on hold with payroll. Gather your most recent pay stubs, your W-2s from the last two years, your tax returns from the last two years with all schedules, and your bank statements from the last two to three months. If you're self-employed, have your year-to-date profit and loss statement ready as well. Be accurate about your income. Intentional misrepresentation on income documentation is fraud, and it's prosecuted. Even unintentional errors can cause delays. If there's a discrepancy between what you reported on your application and what your documents show, address it proactively rather than waiting for the underwriter to find it. A brief explanation goes a long way. "I started a side consulting gig in April that isn't reflected on my W-2" is much easier to work with than a confusing deposit pattern that requires interrogation to explain. Expect the process to take anywhere from a few days to a couple of weeks depending on your employment situation and how responsive your employer is. Digital verification can be fast. Manual verification involving phone calls and document collection takes longer. Planning for the longer timeline prevents panic when things don't move as quickly as you'd like.
The bottom line is that verification of income is a practical process with known procedures, but it operates in a world where human behavior is messy and documentation is imperfect. The people who navigate it successfully are the ones who understand what the verifier is actually looking for and prepare accordingly rather than treating it as a bureaucratic hurdle to clear and move on from.