Understanding Vertical Integration in American Industry
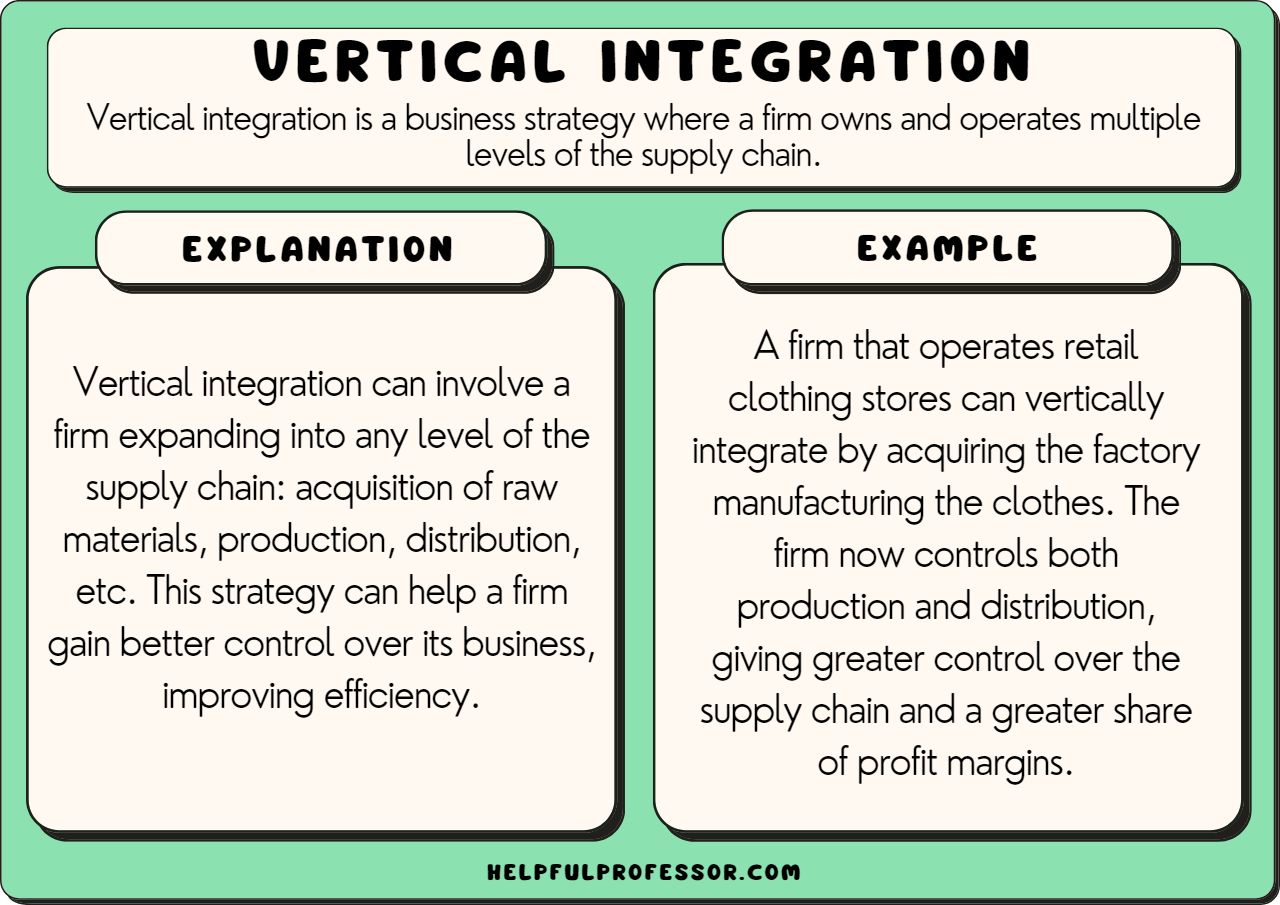
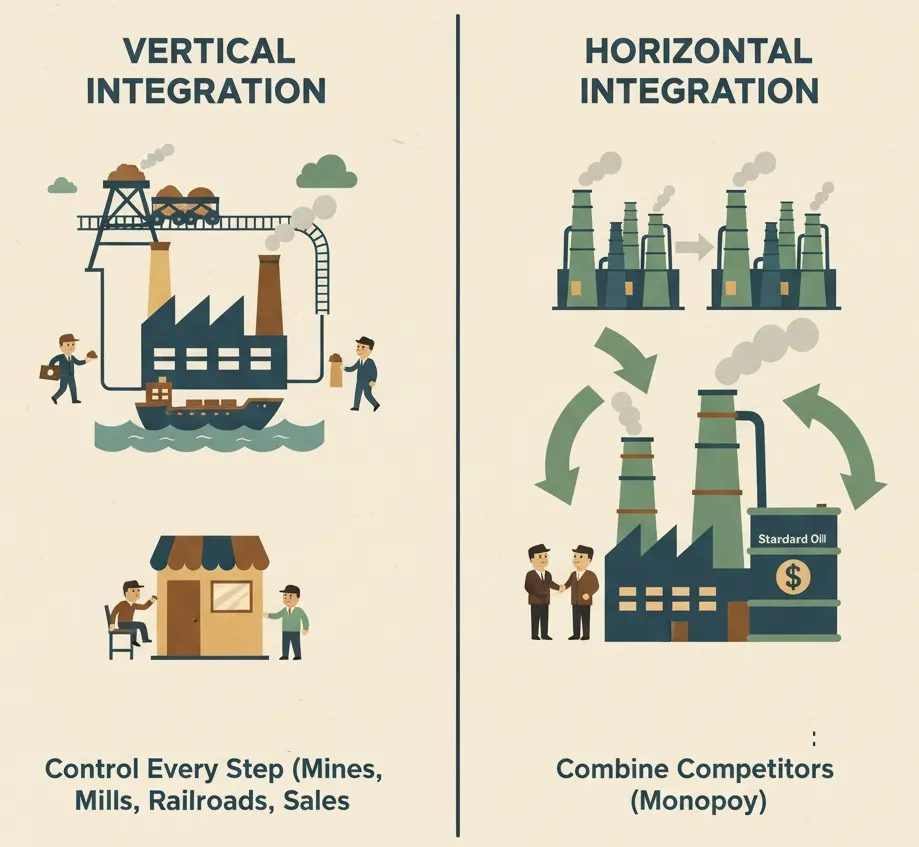
Vertical integration is a business strategy where a company takes control of multiple stages of its supply chain, either by owning its suppliers or its distributors. In the United States, this concept became most famous during the late 19th and early 20th centuries when industrial magnates built massive conglomerates that controlled everything from raw materials to finished products. The standard Vertical Integration Definition Us History context centers on figures like Andrew Carnegie, John D. Rockefeller, and Henry Ford, each of whom used vertical integration to reduce costs, increase efficiency, and dominate their respective industries. Carnegie Steel is probably the most textbook example. He owned iron mines, coal fields, railroads, and shipping lines, then moved the finished product through his own mills. Rockefeller did something similar with Standard Oil, buying pipelines, tank cars, and refineries so the company wasn't dependent on anyone else's transportation or processing capacity. These weren't minor decisions, they were structural shifts that redefined how entire industries operated.
What the Vertical Integration Definition Us History Actually Covers
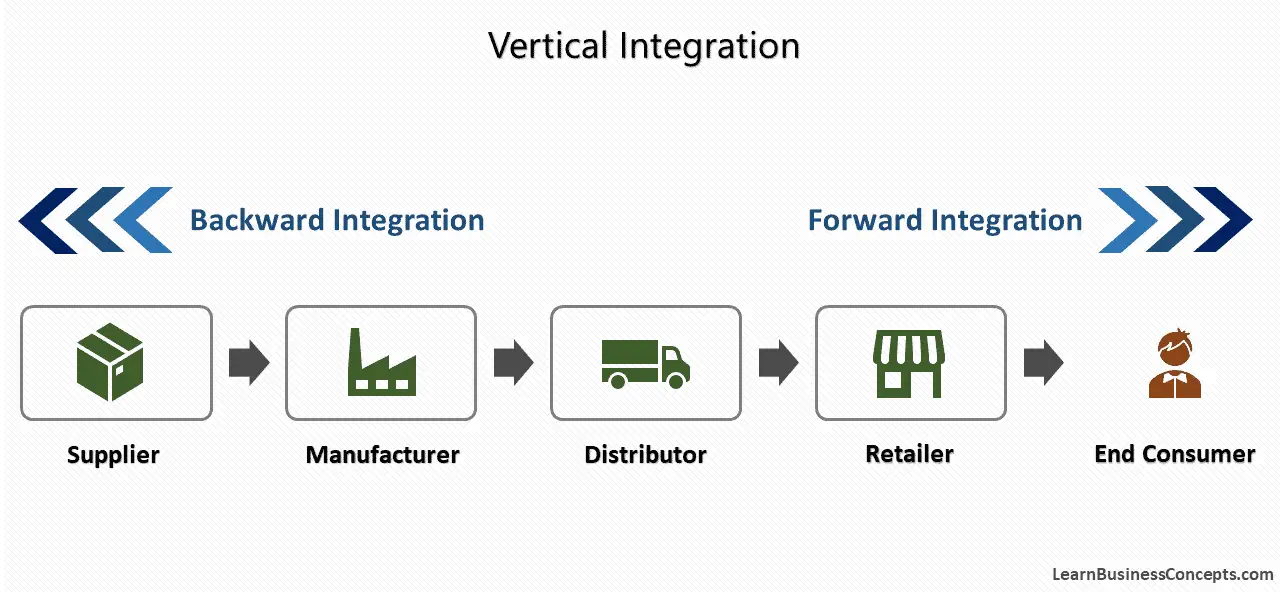
The formal definition breaks down into two directions. Backward vertical integration means a company moves upstream toward raw material sourcing, acquiring suppliers or distributors of its inputs. Forward vertical integration means moving downstream toward the end consumer, acquiring distribution channels, retail outlets, or logistics companies. A firm can do both simultaneously or pick one direction depending on its strategic needs. Historically, American vertical integration served three primary purposes. First, it eliminated the markup that independent suppliers or distributors would normally charge. Second, it provided supply certainty so the company wasn't hostage to shortages or price spikes from third parties. Third, it created barriers to entry for competitors who couldn't replicate that level of control. That last point is the one people often overlook because it's less obvious than cost savings. There's a common misconception that vertical integration is always about growth or ambition. It often isn't. Sometimes it's defensive, a response to a supplier refusing to honor contracts or a railroad charging outrageous freight rates because it had a monopoly on transport. The Pennsylvania Railroad's pricing practices in the 1870s pushed several large manufacturers toward owning their own shipping capacity rather than fighting an unwinnable battle with a monopolistic carrier.
How It Worked in Practice
The mechanics are straightforward but the execution was brutal. A company would identify the bottleneck in its supply chain, purchase or build the asset that controlled that bottleneck, and repeat until the entire chain was internal. This took time, capital, and often antagonized every competitor and labor group in the vicinity. Carnegie invested heavily in open-hearth furnaces alongside his railroad and mine acquisitions, which meant his overhead was enormous until production volumes justified it. He bet the company's solvency on volume, and it paid off, but barely. Rockefeller's approach was more ruthless. He didn't just buy his way into vertical integration, he used it to squeeze competitors out of the market. By controlling refining and distribution, he could offerrebates to railroads that rival refiners couldn't match, then underprice them until they folded or sold. The Sherman Antitrust Act of 1890 was partly a response to this kind of behavior, though enforcement was inconsistent for decades. Henry Ford's River Rouge Complex represents the extreme end of vertical integration. At its peak, it took iron ore and coal in one end and finished Model Ts out the other. The complex included its own steel mill, glass factory, rubber processing plant, and a vast network of rail lines and river barges. It was a marvel of industrial engineering and an enormous financial risk that only worked because Ford's production volumes were so high that fixed costs spread thin across millions of units.
Get the Full Details
The Downsides Nobody Talks About Enough
Vertical integration sounds efficient until you examine what happens when demand drops or technology shifts. When you own the entire supply chain, every stage becomes your problem. A downturn doesn't let you shed expensive capacity, you have to service debt on assets you can't sell quickly. During the 1920s, many vertically integrated firms struggled because they couldn't adjust production costs as fast as firms that outsourced. Another hidden cost is organizational bloat. Managing a steel mill requires different expertise than managing a retail network, and forcing the same management structure across both tends to create friction. I once worked with a mid-sized manufacturing firm in the 2010s that tried to vertically integrate into its own logistics network. They bought a fleet of trucks and a small warehousing operation. Within eighteen months, their delivery costs per unit were higher than what they'd been paying external providers, and their quality control complaints from drivers tripled. The external providers had scale, training programs, and union contracts that a fifteen-person internal team simply couldn't replicate. We reverted to third-party logistics after the initial excitement faded, but it cost us nearly two million dollars in sunk capital and three months of operational disruption. Antitrust risk is another major factor. The United States has a long legal history of breaking up or restricting vertically integrated firms, particularly when they use that integration to foreclose competition. The Justice Department's 1911 breakup of Standard Oil is the landmark case, but vertical integration scrutiny continued through the mid-20th century and resurfaced periodically. A company that integrates vertically needs to be aware that regulators may view those acquisitions differently than they view organic growth.
When Vertical Integration Makes Sense Today
Modern examples are more selective. IBM controlled hardware, software, and services for decades before breaking apart in the 1990s, a move many analysts argue improved its competitiveness. Apple's vertical integration is more subtle, focusing on chip design, operating systems, retail stores, and proprietary accessories rather than raw material extraction. The pattern that emerges from successful modern cases is that vertical integration works best when it targets specific bottlenecks rather than blanket control of the entire chain. If you're evaluating whether to pursue this strategy, the first question to answer is which stage of your supply chain creates the most variance in cost or reliability. That's the stage worth integrating. Beyond that, calculate the fixed cost increase against the variable cost savings and run scenarios for both high-volume and low-volume periods. Most companies that skip this step overestimate savings and underestimate the management complexity that follows. The historical record from the United States shows that vertical integration can be transformative, but it's also shown repeatedly that it fails when applied without precise targets and realistic capacity assumptions. The businesses that survived were the ones that integrated only where it mattered and stopped before overextension became a liability.