Working With a Veterans Mortgage Calculator in Practice
You grab a Veterans Mortgage Calculator and plug in numbers. The output looks reasonable on first glance, but that is where most people stop paying attention. The VA loan program has enough moving parts that a generic calculator will quietly give you a misleading monthly payment if you do not know what to watch. I have run hundreds of these calculations across different counties and lenders. The thing that trips people up most often is how VA funding fees interact with the loan amount, how residual income works, and what the certificate of eligibility actually locks in versus what the lender still evaluates on its own.
How the Veterans Mortgage Calculator Actually Works
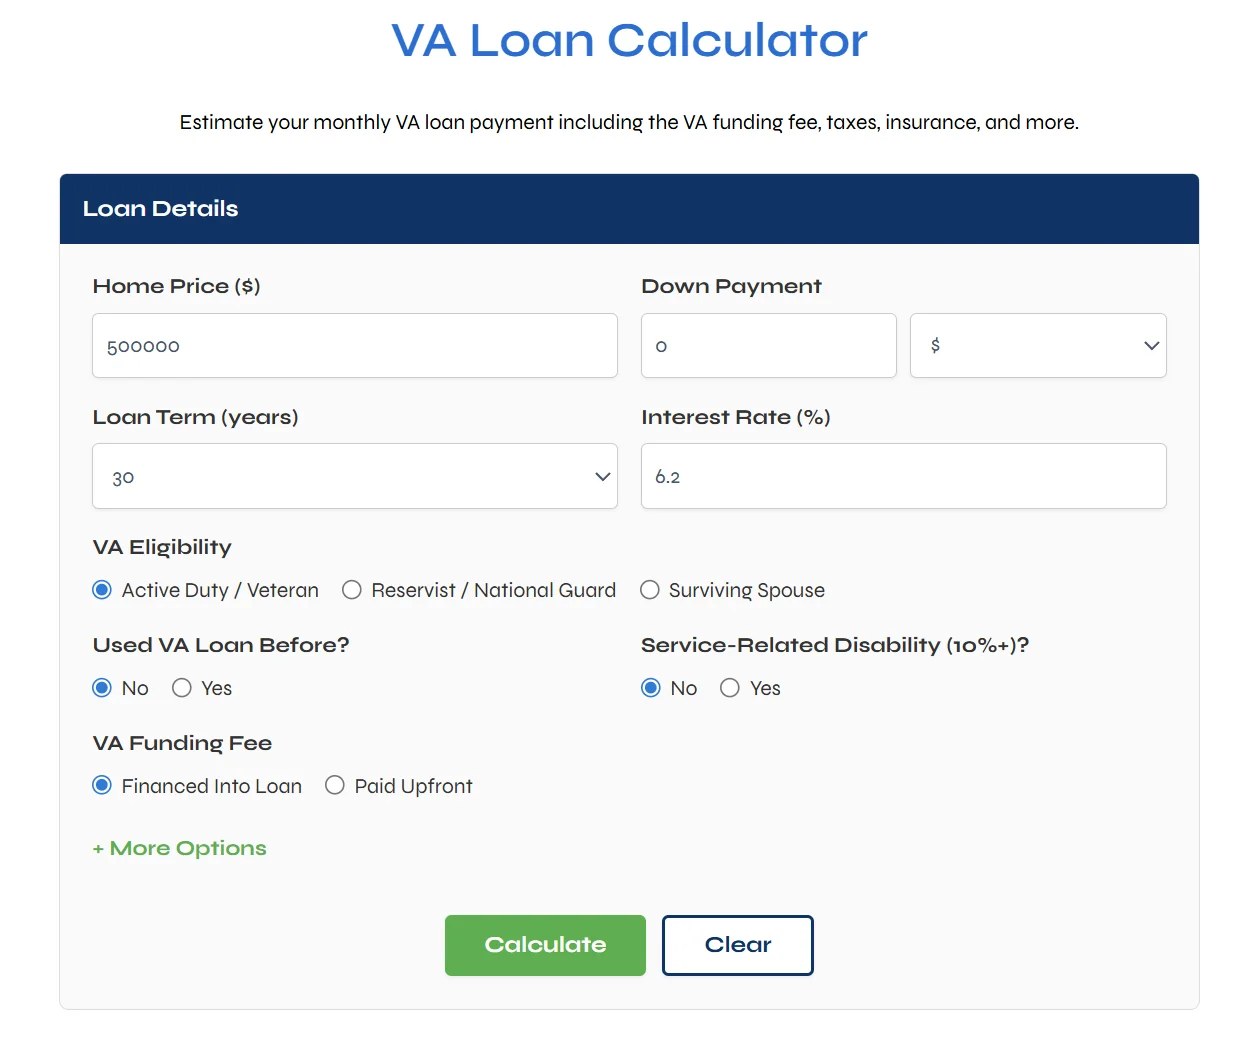
At the core, the calculator takes your home price, subtracts your down payment, pulls in your interest rate, and then layers on the VA-specific pieces: funding fee, possibly mortgage insurance if the VA ever applies it in a particular scenario, and property taxes and homeowners insurance if you choose to include escrow items. The resulting number is your total monthly housing payment, not just principal and interest. The tricky part is the funding fee. It is a one-time charge that the VA requires unless you are exempt due to a service-connected disability. The percentage changes depending on whether this is your first time using VA loan benefits, whether you put money down, and whether you are in the regular Reserve or National Guard. A first-use purchase with zero down currently runs around 2.3 percent. Second use with less than five percent down jumps to roughly 3.6 percent. You can roll that fee into the loan balance, which means you are paying interest on top of the fee, and that detail is easy to miss if the calculator does not make it explicit. Another piece that standard calculators fudge is residual income. The VA sets minimum residual income thresholds based on family size and county cost-of-living adjustments. Lenders use those numbers to decide whether you qualify. A Veterans Mortgage Calculator will rarely show you whether your income clears the residual test, so you should verify that separately before you get too attached to a payment number.
Step by Step Walkthrough
Setting Up the Inputs Correctly
First, confirm your certificate of eligibility. You can get it through the VA eLOD system or have your lender request it. Without a valid COE, the calculator is just a math toy. Enter your purchase price, your down payment if any, and make sure the calculator asks whether you have used VA loan benefits before. That question matters because the funding fee changes. Pick the right county for property tax rates. Some calculators let you skip it and assume a national average, which is fine for rough screening but bad for accuracy.
For the interest rate, do not guess. Get a current rate sheet from your lender or check live rates from at least two sources. VA rates tend to run slightly below conventional rates because the VA guarantees a portion of the loan, which reduces lender risk, but the spread varies by credit score, debt-to-income ratio, and market conditions on the day you shop. A properly configured Veterans Mortgage Calculator will show you a breakdown: principal and interest, property taxes, homeowners insurance, and the funding fee amortized into the monthly payment if you chose to finance it. If you do not see that breakdown, switch tools. You need to see each line item because property tax rates can vary by factor of three between counties, and skipping that detail will skew your budget decision. Look closely at the debt-to-income ratio. Most lenders want your front-end ratio under 41 to 45 percent and your back-end ratio under 41 to 50 percent, depending on the lender and your credit profile. The calculator may not enforce those limits, but the lender will. Run your actual debts through a quick DTI check before you treat the calculated payment as gospel.
Get the Full Details

I ran into a case recently where a borrower used a free online Veterans Mortgage Calculator, got a monthly payment that looked comfortable, and then hit a wall at underwriting because the lender added a VA funding fee that was higher than the calculator assumed. The borrower had used VA benefits before but selected the wrong funding fee tier in the tool. The payment jumped by nearly two hundred dollars a month once the correct fee was applied. It was an easy fix, but it cost him a day of rescheduling inspections and talking to the seller. Always double-check the funding fee tier before you move forward.
Edge Cases and Common Pitfalls
One common mistake is assuming the VA loan covers the full purchase price. It does not guarantee 100 percent financing in every case, especially for conforming loans above certain thresholds or in high-cost counties where the VA’s loan limit adjustments matter. The VA does not set a maximum loan amount, but lenders follow conforming loan limits set by Freddie Mac and Fannie Mae for the portion they might sell. If the purchase price exceeds those limits, you may need a down payment on the excess, and a basic calculator will not flag that automatically. Another edge case involves renovation loans. The VA offers the Iron Star program and certain refinancing paths that include repair costs. If you are using a Veterans Mortgage Calculator for a renovation loan, make sure it can handle the combined loan structure. Many standard calculators assume a clean purchase with no repair escrow, so the output will underestimate your actual obligations. Refinancing is also a common source of confusion. An Interest Rate Reduction Refinance Loan, or IRRRL, lets you refinance an existing VA loan with reduced paperwork, but you still pay a funding fee, usually lower than the purchase funding fee. If you plan to refinance later, do not bake the purchase funding fee into your long-term calculations. Use the IRRRL fee instead once you know the current rate.
When the Calculator Fails You
A Veterans Mortgage Calculator is a screening tool, not a substitute for underwriting. It cannot evaluate your credit history, verify your employment, check for significant gaps in income, or assess whether a large recent debt payment will raise red flags. It also cannot read local school district tax rates, special assessment overlays, or HOA fees that vary by neighborhood. Those items change the real monthly cost significantly, and if you are serious about a purchase, you need a lender quote that includes everything. If the calculator you are using does not ask about your prior VA loan usage, funding fee tier, county-specific taxes, and whether you have a disability exemption, it is too simple for anything beyond a rough ballpark. Look for a tool that lets you customize those fields or talk to a VA-approved lender who can run a formal estimate.
Practical Tips That Actually Help
Run the numbers at least twice, once with the funding fee rolled into the loan and once with it paid out of pocket if you can. The monthly payment difference is small, but the total interest paid over the life of the loan changes noticeably when you finance the fee. If you plan to sell within five to seven years, the break-even point for paying the fee upfront versus rolling it in may shift, so calculate both scenarios. Keep a spreadsheet of your actual monthly obligations: car payments, student loans, credit cards, child support if applicable. Lenders will count all of those toward your debt-to-income ratio. A Veterans Mortgage Calculator gives you the housing payment, but your ability to afford it depends on what else you owe. Do the math yourself, or ask the lender to show you the full underwriting picture before you submit an offer. Finally, remember that VA loans are flexible. You can reuse your entitlement multiple times as long as you pay off the VA loan or sell the property and restore your entitlement. That flexibility is valuable, but it also means you should track how much entitlement you have remaining and what your funding fee will be next time. A good Veterans Mortgage Calculator will let you model different entitlement scenarios, and if yours does not, find one that does.
The bottom line is straightforward: use the calculator to get in the ballpark, verify the funding fee and eligibility details yourself, check residual income against VA tables, and then get a lender estimate that reflects your actual situation. The difference between a rough estimate and a firm number is usually a few hundred dollars a month, which is enough to change your decision on a house.


