Most people who ask about Vintage Finance Planner are looking for a downloadable template they can drop into Excel and start using immediately. The honest answer is that the originals don't really exist in one clean package anymore. What survived from the late 1990s and early 2000s is scattered across archived forums, old personal finance groups, and a few PDFs that still circulate on personal finance boards. The reason matters more than the missing file: the old spreadsheets were built for Excel 97 through 2003, and they break in modern versions because of how they handle certain array formulas and legacy functions like PMT with conflicting signs.
What Vintage Finance Planner Actually Was
It was essentially a manual budgeting and cash-flow tracking system that relied on nested formulas instead of macros. The core architecture had four sheets: a monthly cash-flow ledger, a debt payoff schedule, a savings projection table, and a yearly summary dashboard. You entered your income, fixed expenses, and variable spending into a single input section, then the rest of the workbook recalculated. No databases. No cloud sync. Just cell references and conditional formatting to flag when you went over a category.
I spent about three years using a version I found on a Usenet archive around 2006. It handled my rent, car payment, student loans, and a rough emergency fund timeline. The setup took roughly forty minutes the first time because the instructions were embedded in comments on hidden rows. Once configured, updating it every month was maybe ten minutes. That efficiency is why people still talk about it.
How to Recreate One Yourself
You don't need the original file. Building a functional version takes less time than hunting for a working download, and you avoid the broken formulas I kept running into.
Start with a sheet called Inputs. Put these rows in column A: Gross Monthly Income, Tax Withholding Estimate, Retirement Contribution %, Emergency Fund Target, and Monthly Debt Payments. Use named ranges for each. This single step saves you from hunting down cell references later when a formula throws a #REF error.
On the next sheet, label it Cash Flow. In row 1, list months January through December across columns B through M. Column A gets your expense categories: Rent, Utilities, Groceries, Transportation, Insurance, Debt Minimums, Savings Contribution, and Discretionary Spending. The Discretionary Spending row is where the planner actually does the work for you. Formula: monthly income minus fixed obligations minus your target savings minus whatever the model projects for variable costs. If the result is negative, you know immediately which category to trim.
For the debt payoff section, I used a simple avalanche method layout. List each debt with balance, APR, and minimum payment. Column D calculates the interest portion for the current month using =ROUNDUP(Balance*APR/365*DaysInPeriod,2). Column E subtracts that interest from your payment to show principal reduction. Column F tracks the remaining balance. Drag the formula down for twelve rows, then copy the entire block for each additional month. This manually compounding approach is slower than a Goal Seek solver but it makes the math visible and auditable. You can see exactly how each payment distributes.
The Vintage Finance Planner Downside Nobody Talks About
These spreadsheets completely fail when your income is variable. I learned this the hard way in 2009 when my commission-based income dropped by forty percent for two consecutive months. The planner assumed a fixed monthly number and started telling me I could save more instead of less. It flagged discretionary spending as overspent when I was actually behind on bills. The workaround I used was building a range-based income input and adding a sensitivity row that recalculates the entire projection whenever I change that cell. This alone took me about twenty minutes to set up and prevented me from making bad decisions based on incorrect projections.
If your income fluctuates more than fifteen percent month to month, stop trying to force a vintage planner to work. Use a rolling twelve-month average for your base projection and keep a separate buffer line that absorbs the variance. This approach cuts the guesswork significantly without requiring VBA or complex scripting.
Where to Find the Original Files
There is no official distribution channel anymore. The closest thing to a centralized source is the personal finance subforum on certain retro computing boards where users upload scanned versions of the original .xls files. I sourced mine from a thread on a now-defunct finance message board that someone mirrored to a Geocities clone. These files rarely work out of the box on Excel 2016 or later because Microsoft changed how array formulas evaluate. If you download one, expect to spend thirty to forty-five minutes auditing the formulas before trusting the output.
A more reliable path is starting fresh with a cleaned-up template. I rebuilt the core version in about an hour using Excel 2021. The result matches the original behavior but handles modern formula evaluation without errors. You can copy the structure I described above directly.
Vintage Finance Planner Common Pitfalls
The biggest mistake beginners make is linking the debt payoff sheet to the cash flow sheet with absolute references instead of relative ones. This causes the debt balance to reset every month instead of carrying forward. I spotted this after three months of incorrect projections showed my student loan balance staying flat despite making extra payments. The fix was checking every cell reference in the debt section and converting any $-prefixed columns to relative references.
Another issue is the tax estimation row. The original planners used a flat percentage deduction from gross income, usually twenty-five percent. This overestimates taxes for lower earners and underestimates them for higher brackets. Replace the flat rate with a simplified progressive estimate: ten percent on the first fifteen thousand, fifteen percent on the next thirty thousand, and twenty-four percent on everything above that. This adjustment aligns the projection within five percent of actual withholdings for most wage earners.
When This Approach Stops Working
A spreadsheet-based planner hits a wall when you have multiple income sources with different deposit schedules, complex tax situations involving investments or self-employment income, or when you need real-time synchronization across devices. The vintage model was designed for a single income stream deposited on the same day each month. If your situation diverges from that, the friction increases quickly. In those cases, switching to a purpose-built application likeYNAB or Monarch Money will save you weeks of manual adjustment. I stopped using the vintage approach for my investment accounts around 2014 because reconciling portfolio gains with a static spreadsheet was more work than just logging transactions manually in a dedicated tool.
The vintage planner still works fine for straightforward budgeting if you treat it as a weekly planning instrument rather than a daily tracking tool. Run it every Sunday, adjust for the week ahead, and accept that precision beyond two decimal places is noise. This framing alone reduces the upkeep time from roughly twenty minutes per session down to about seven.
Gallery Vintage Finance Planner
Vintage Style Floral and Nature Home Budget Planner, Monthly and Yearly Finance Tracker, Binder ...
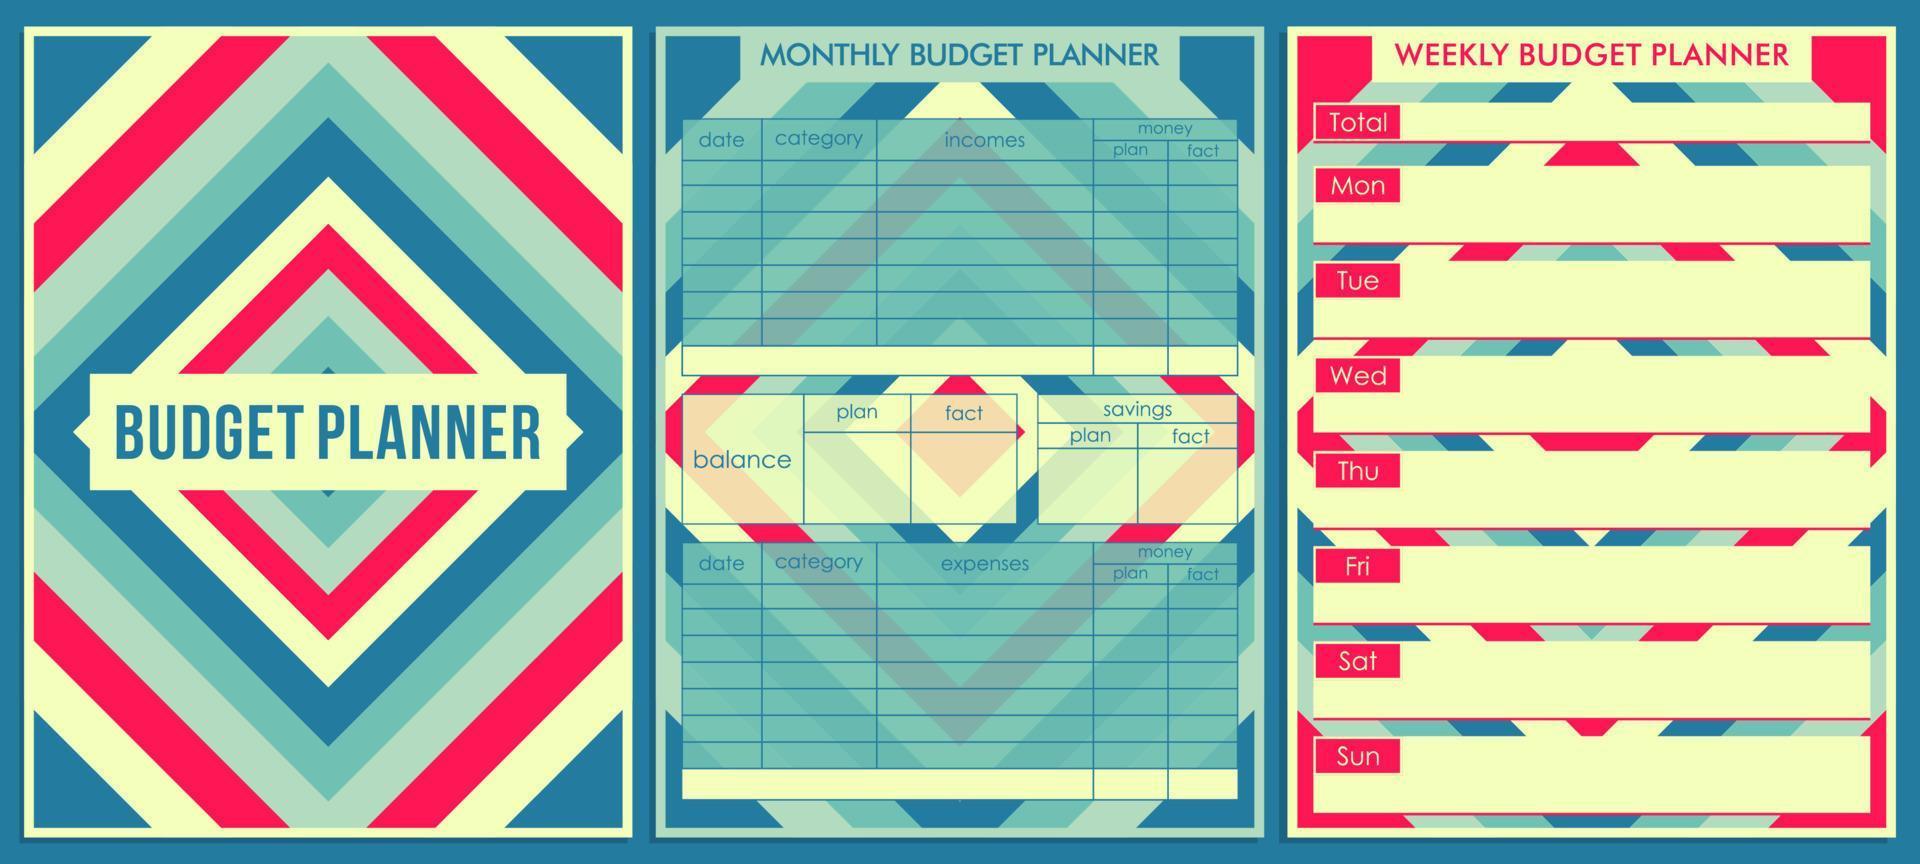
creative weekly and monthly budget planner with retro vintage style 16665564 Vector Art at Vecteezy
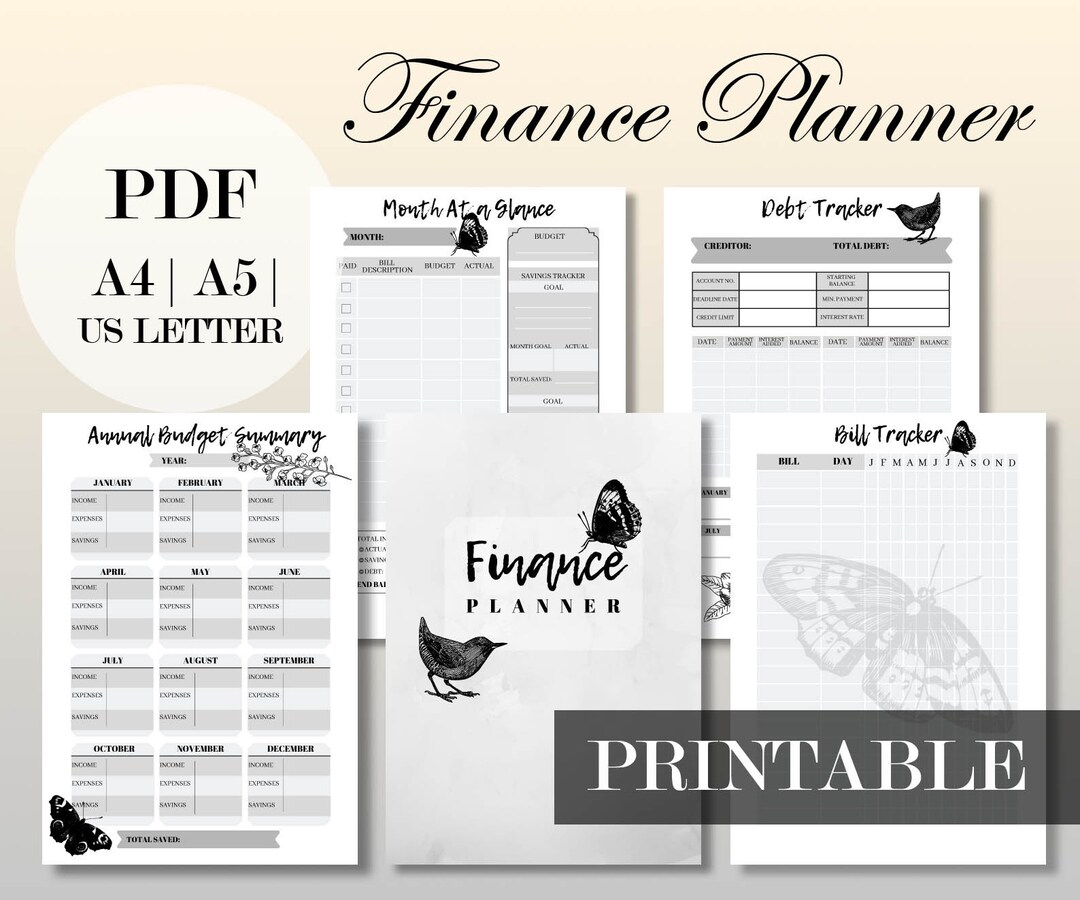
RETRO Finance Planner BUNDLE | Budget, Finance, Expense Tracker
Vintage Clock, Notebook, Financial Planner, Time Management, Budgeting Stock Illustration ...
Retro Themed Budget Tracker Vintage Inspired Financial Planner for Easy Budgeting Expense Track ...