What People Actually Mean When They Say "Vix Stock"
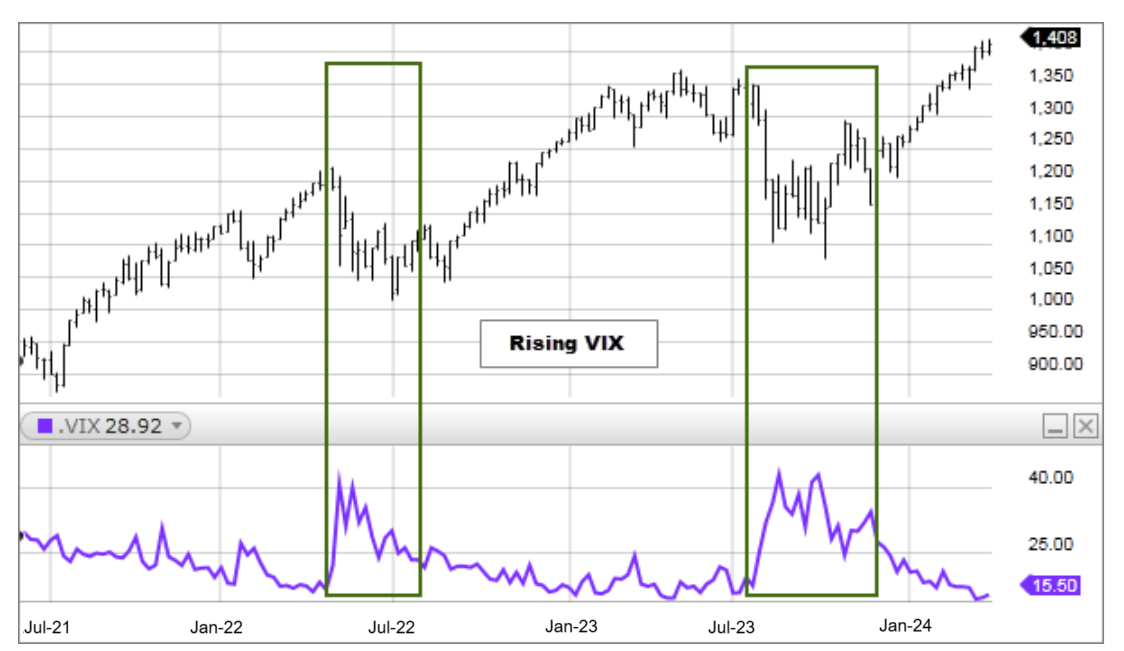
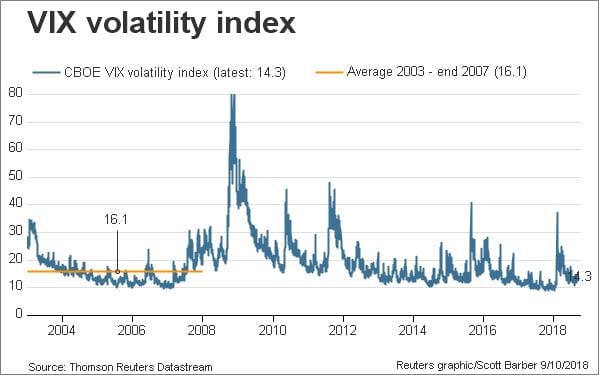
There isn't a single VIX stock. The VIX itself is an index calculated by the Chicago Board Options Exchange based on S&P 500 put and call option prices. It measures expected market volatility over the next 30 days. When retail traders talk about buying VIX stock, they're usually referring to one of three things: VIX futures, VIX-based ETFs, or equity volatility products. Getting that straight matters because the mechanics and tax treatment differ significantly between them. The most accessible products are ETFs like VXX, UVXY, and VIXY. These track short-term VIX futures rather than the spot index itself. I spent a lot of time explaining to clients why these aren't pure plays on VIX during the March 2020 crash. They're futures rolls. That distinction eats returns over time in contango environments, which is most of the time. The VIX futures curve sits in contango roughly 70-85% of the year. Each time these funds roll from one futures contract to the next, they sell low and buy high, creating a structural drag that averages around 15-20% annualized depending on curve steepness. I learned this the hard way in late 2021. A client had $40,000 in VXX expecting a volatility spike. Nothing happened. The S&P 500 went up steadily through November and December. His position lost about 35% purely from the roll decay, not from VIX moving against him. He was furious, rightfully so. I should have shown him the term structure before he bought. I didn't, and that was on me.
How to Actually Trade Volatility Exposure
The first step most people skip is checking the VIX term structure. You can pull this from CBOE's website or any decent data terminal. Look at the spread between the front-month and second-month VIX futures. If front-month is trading significantly below the deferred months, you're in contango and entering a long volatility position is gambling against the odds. If it's in backwardation, meaning front-month is higher than deferred, that's when VIX products tend to work for long positions. For actual execution, you have options depending on your account type and experience level. A standard brokerage account lets you buy VXX or similar products. An options-approved account opens up VIX call and put spreads, which are more capital-efficient and define your maximum loss upfront. A margin account with futures clearance lets you trade VIX futures directly, which avoids the fund expense ratio but adds roll management responsibility. Most people don't need that last tier unless they're doing this regularly. My standard recommendation for beginners is a long VIX call spread rather than outright ownership of an ETN. Say you buy the 30 strike and sell the 45 strike expiring in roughly 30 days. You cap your downside to the premium paid, and you avoid the tracking error that comes with holding a fund through multiple roll periods. It's not perfect, but it's honest about what you're buying.
The Problems No One Talks About
VIX products have several quirks that trip up experienced traders too. The first is that VIX futures are cash-settled with no physical delivery. That means you can't hold them to expiration without a roll, and the settlement price is based on a special open outcry calculation at 3:45 PM Central Time. During illiquid sessions or extreme volatility events, that settlement can diverge sharply from where you see the index trading minutes earlier. I saw this happen on a Tuesday morning in August 2022 when a Fed speaker spooked markets. The VIX futures settled nearly 8% below the closing index level because the calculation weighted early session prices during a period of chaotic trading. People who held through the close got burned. The second issue is convexity risk. VIX futures don't move 1:1 with the VIX index. They amplify moves in one direction and dampen them in the other. When VIX spikes, VIX futures can spike harder, which is attractive for short periods. When VIX grinds down, the futures grind down slower than the index, which feels fine until you realize you've been paying roll costs while also losing directional exposure. The third problem is tax treatment. VIX futures are regulated under Section 1256 of the Internal Revenue Code. That means 60/40 split for capital gains regardless of holding period, which is actually favorable compared to short-term ordinary income rates for many traders. But if you're holding VIX ETFs instead of futures, those are taxed as regular securities. The difference matters in a meaningful way if you're doing this year after year. I make sure every client understands which bucket they're in before they place the first trade.
Get the Full Details

When VIX Products Fail Completely
Here's the blunt part: VIX products are terrible long-term holds. They are event-driven instruments, not income vehicles or portfolio stabilizers. The structural roll decay means that even if the VIX stays flat for a year, you will lose money holding these products. I've seen people buy VXX as a "hedge" and wonder why their portfolio underperformed during calm years. It's not a hedge. It's a bet on volatility rising faster than the roll cost can erode your position. That bet wins less than half the time over multi-year periods. If you need actual portfolio insurance, buy S&P 500 put options or consider a tail-risk fund. Those are designed to pay off when markets drop and don't bleed value during normal conditions. VIX ETNs and futures are speculative instruments. They belong in a trading account, not a retirement strategy. I tell clients this directly because the alternative is watching them lose money for two years and then asking why I didn't warn them. The Vix Stock products exist because there's demand for volatility exposure, and there's demand because recessions and crashes hurt. But the gap between what people think they're buying and what they actually get is where most of the losses happen. Check the term structure. Size the position like it's speculative, not defensive. And roll or exit before expiration unless you understand exactly what you're accepting.