What Wall Street Prep's Financial Reports Course Actually Teaches
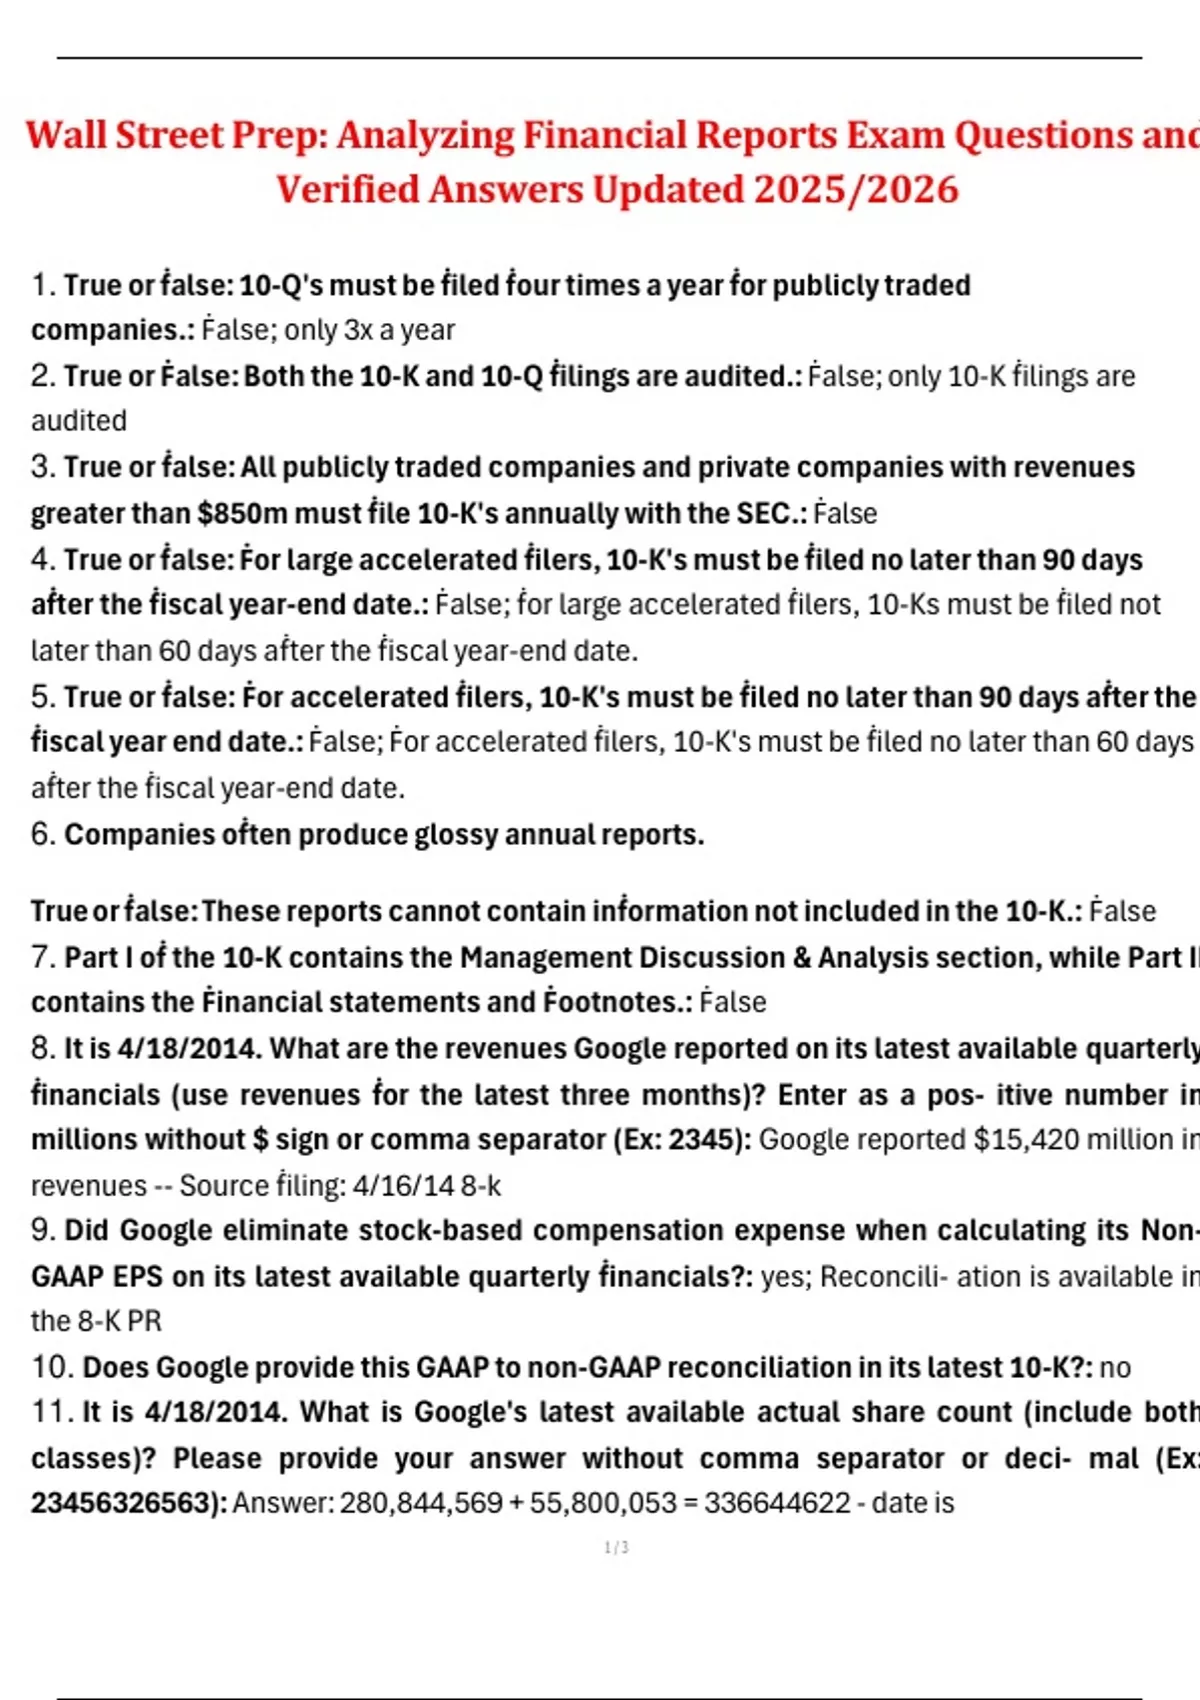
The Wall Street Prep Analyzing Financial Reports Exam is the final assessment in their financial statement analysis module. It tests whether you can read a 10-K, pull the right numbers from each section, and answer questions that mix recall with basic application. The exam itself is multiple-choice with a time limit, and it covers the income statement, balance sheet, cash flow statement, and how they connect. I went through this course about three years ago when I was prepping for an associate-level interview at a buy-side firm. The material is straightforward enough — it teaches you the standard way analysts handle financial statements in practice, not some academic framework. You learn how to reclassify operating leases under the old rules, how to adjust stock-based compensation in EBITDA calculations, and how to spot when a company is manipulating its cash flow presentation. The exam is roughly forty questions, takes about forty-five minutes, and you get two attempts. That second attempt matters more than people realize. The first time I took it I missed three questions on lease accounting because I conflated the old operating lease treatment with the new standard. On retake I spent extra time on that section and passed cleanly.
Wall Street Prep Analyzing Financial Reports Exam
Here is how the exam is structured in practice. The first quarter covers the income statement — revenue recognition patterns, non-recurring items, how to normalize earnings. The next section moves to the balance sheet, where they test your ability to spot differences between GAAP book values and economic reality. Working capital adjustments, goodwill impairment signals, and debt classification are fair game. The cash flow portion asks you to distinguish between operating, investing, and financing activities and to identify when a company is restructuring its cash flow presentation to look healthier. The final segment combines all three statements and asks you to answer questions that require moving between them. You might need to calculate free cash flow from net income, or determine how a change in depreciation policy affects both the income statement and the balance sheet simultaneously. These are not theoretical questions — they mirror the kind of adjustments you would make in a real equity research model. One thing beginners consistently underestimate is the speed required. The questions are not difficult if you know the material. The difficulty comes from having to read and process financial data quickly under time pressure. I timed myself while studying and found that I could work through a typical exam question in about ninety seconds. Anything slower meant I would fall behind.
The course provides sample financial statements for practice. I used the Amazon 10-K from 2019 as my primary drill document. It had everything — complex revenue recognition, significant lease obligations, stock-based compensation that was material but not obviously disclosed, and a cash flow statement that required careful reading to separate genuine operating cash generation from one-time items. Working through that document before the exam cut my preparation time significantly. There is a practical limitation worth noting. The exam focuses heavily on US GAAP. If your work environment uses IFRS, the course material will not fully prepare you. The differences in lease accounting, inventory valuation, and revenue recognition between the two frameworks are substantial. I knew this going in and supplemented the course with a separate IFRS reference guide, which added maybe four hours to my overall study time but filled the gap. Another common pitfall is over-relying on the practice quizzes. The practice questions are representative but not identical in format to the final exam. The real exam includes some questions that present financial data in a slightly different layout — tables without clear headers, notes buried in the text, numbers that require cross-referencing between sections. I learned this the hard way on my first attempt.
Get the Full Details
If you are struggling with a particular concept, the most efficient workaround is to skip ahead and return later. I spent about twenty minutes stuck on deferred tax asset recognition questions during my first study session. Moving on to the cash flow statement section and coming back after an hour made the deferred tax material click. The brain processes connected concepts better when it has had time to work subconsciously. The exam does not require advanced mathematical ability. Basic arithmetic, understanding of percentages, and comfort with reading tables are sufficient. What it does require is the ability to quickly identify which line item in a financial statement answers the question being asked. In practice, this skill translates directly to analyst work. Senior analysts often need to find a specific number in a dense annual report under time constraints, and the exam simulates that environment. For anyone preparing, I recommend taking the practice exam under actual test conditions — no notes, no pausing, strictly timed. The first time I did this, I scored around seventy-two percent. After two more weeks of targeted review focused on my weak areas, I scored eighty-nine percent on the actual exam. The improvement came from narrowing study to specific gaps rather than re-reading material I already understood.
The course itself costs money and the exam is included in the subscription. If you are evaluating whether to invest time in this particular module, the honest answer is that it covers foundational material well but will not prepare you for advanced valuation scenarios or complex M&A modeling. It is a solid starting point for someone building their financial analysis foundation, but it is not comprehensive by itself. I have seen people use this exam as a credential on their resumes. That is reasonable if you are early in your career and need something concrete to demonstrate competence. Beyond that, the knowledge it tests is baseline professional expectation, not a distinguishing skill.