The Walt Disney Company operates through four reportable segments: Parks, Experiences and Products; Media Networks; Studio Entertainment; and Direct-to-Consumer. That structure sounds clean on paper. The reality is messier, and understanding how these pieces actually connect requires looking past the press releases.
I used to work with a team that analyzed Disney's capital allocation for an investment fund. The first thing we learned was that the annual report numbers tell only half the story. The segment reporting lumps certain costs together in ways that make cross-segment comparison almost meaningless without adjustment.
The Core Walt Disney Company Business Strategy
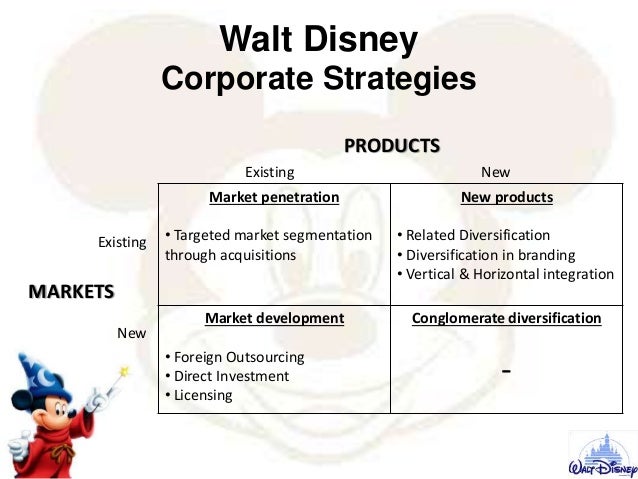
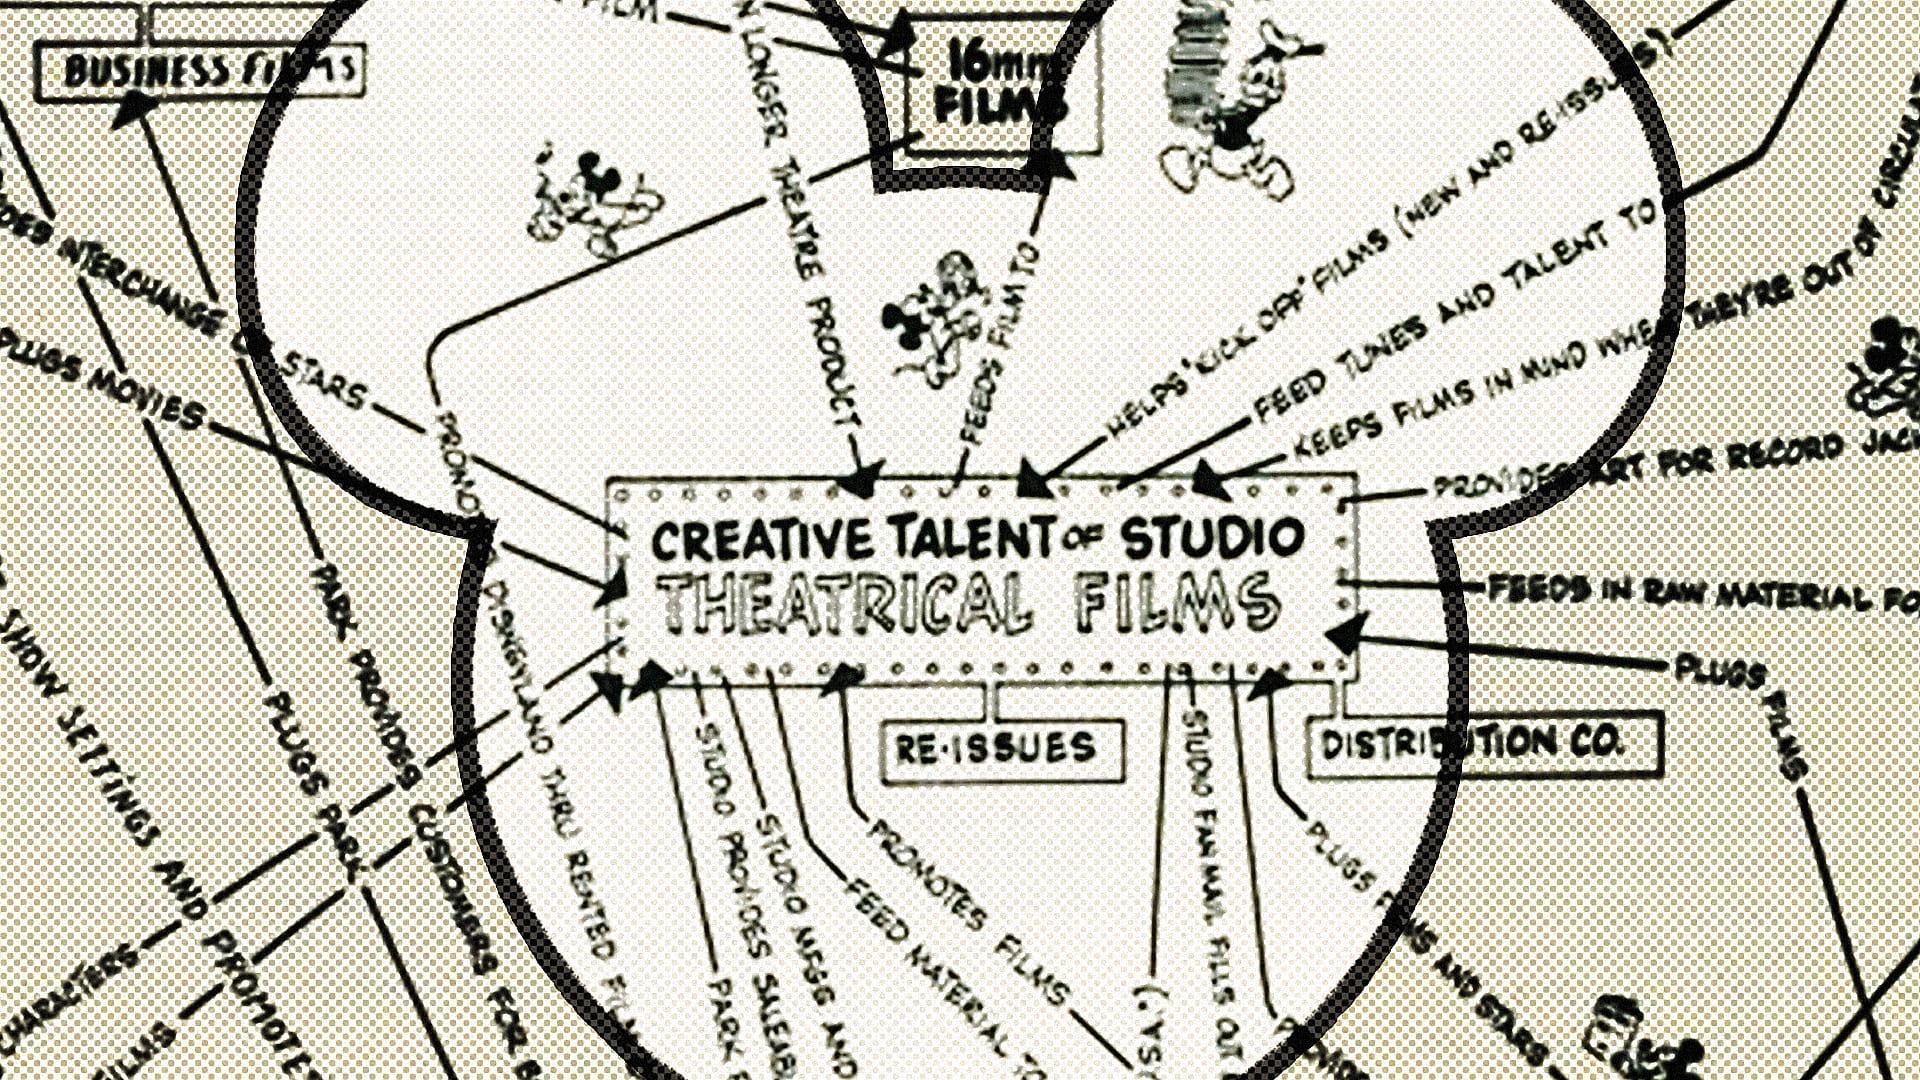
Disney's strategy centers on intellectual property ownership and vertical integration. They build franchises, then monetize them across multiple channels simultaneously. A single character or film can generate revenue through theatrical release, streaming, theme park attractions, merchandise licensing, and television syndication. The math only works if you control enough of those channels to capture meaningful margins on each one.
The acquisition strategy explains a lot. Buying Pixar, Marvel, Lucasfilm, and the 21st Century Fox entertainment assets wasn't random expansion. It was systematic IP portfolio building at scale. Before those deals, Disney had Mickey Mouse and a handful of franchise properties. After, they controlled something like 50 major film franchises spanning multiple demographics and age groups. That changes the entire economics of merchandise licensing and park development.
Here is where most people miss the point: the parks are the profit engine, not the content. Studio Entertainment frequently operates at thin margins or occasional losses, especially when accounting for production costs and marketing spend. The parks consistently deliver operating margins in the 25 to 30 percent range. That is a structural feature, not a temporary advantage.
I remember spending three weeks trying to reconcile Disney's reported operating income for Parks with the actual cash generation from resort operations. The segment includes both domestic and international parks, but the accounting treatment for pre-opening costs, real estate depreciation, and intercompany licensing fees varies by location. The workaround was pulling the 10-K notes on real estate and depreciation, cross-referencing them with quarterly visitor attendance data from industry sources, and adjusting for what we knew about per-capita spending trends. It took longer than it should have because Disney does not break out domestic versus international park margins in their standard reporting.
How the Segments Actually Work Together
Media Networks, which includes ESPN and ABC, has been declining for years but still generates significant free cash flow. Streaming subscriptions (Disney+, Hulu, ESPN+) have been growing but operating at a loss. That divergence is intentional in the short term and painful in the long term. The $28 billion Fox acquisition was partly justified by adding content libraries to feed the streaming services. Whether that calculation ultimately makes financial sense depends on subscriber growth rates and churn, which are opaque in Disney's reporting.
The products and licensing segment operates on a different model entirely. Disney collects royalty payments from licensees who manufacture and distribute consumer goods. That is high-margin, capital-light revenue. But the royalty rates vary significantly by category and region. Theme park merchandise and apparel typically command different rates than video game licensing or textbook publishing.
One counter-intuitive detail most analyses overlook: the studio segment's theatrical releases serve as marketing expenses for the broader ecosystem. A movie like Avatar may break even or lose money on theatrical distribution alone, but it justifies a decade of merchandise, park land development, and streaming engagement. The ROI calculation spans five to ten years and crosses multiple segments. Traditional financial modeling misses this because it attributes costs and revenues to single segments.
Another thing people get wrong about the park business is the capacity constraint model. Disney manages attendance through pricing, reservation systems, and seasonal adjustments rather than simply building more rides. The marginal cost of adding one more guest is relatively low after fixed costs are covered, which is why dynamic pricing and hotel revenue matter so much. Hotels drive the real profit in resort visits. People assume the park tickets are the main revenue driver. They are not.
Where This Strategy Breaks Down
The biggest vulnerability is over-reliance on franchise IP. When a new Marvel or Star Wars property underperforms, there is no quick pivot. Content development cycles are three to seven years. The pipeline cannot flex rapidly. During the 2023 to 2024 period, several major theatrical releases missed box office targets, and the streaming segment absorbed the full impact without park revenue to offset it.
Streaming economics also present a structural problem. Subscriber acquisition costs have risen significantly as competition increased, while average revenue per user remains relatively flat. The path to profitability requires either substantial price increases or membership bundle changes, both of which risk churn. Disney responded by cracking down on password sharing and introducing ad-supported tiers. That improved metrics but did not change the underlying unit economics.
The park strategy faces its own constraints. New land development takes five to eight years from announcement to opening. Regulatory approval, construction labor, and supply chain issues can extend timelines further. Disney experienced this with Avatar Land expansions and the Star Wars land delays during the pandemic. The backlog of committed projects is a real risk factor that shows up in forward guidance but not in quarterly operating results.
Practical Takeaways
If you are evaluating Disney's strategy for investment or competitive analysis purposes, focus on free cash flow conversion rather than reported operating income. The accounting treatments across segments make the latter difficult to compare period over period. Look at the debt schedule as well. Disney carried substantial leverage from the Fox deal and streaming investments, and refinancing risk becomes relevant if interest rates stay elevated.
The streaming segment should be tracked separately from the rest of the business until it reaches consistent profitability. Combined segment numbers currently obscure whether the core entertainment business is generating enough cash to fund the growth investment. Disney's management treats this as acceptable for now. The market will not.
Gallery Walt Disney Company Business Strategy
The Walt Disney Company: A Corporate Strategy Analysis – WATQVT
The Walt Disney Company THE RIGHT BOARD, THE RIGHT STRATEGY Disney’s Plan For Shareholder Value ...
Walt Disney Company: International Strategy by on Prezi
The Secret To Walt Disney's Corporate Strategy - Fast Company
The Walt Disney Company: Its Diversification Strategy in 2012 | PDF | American Broadcasting ...