How the Washington Mortgage Calculator Actually Works in Practice
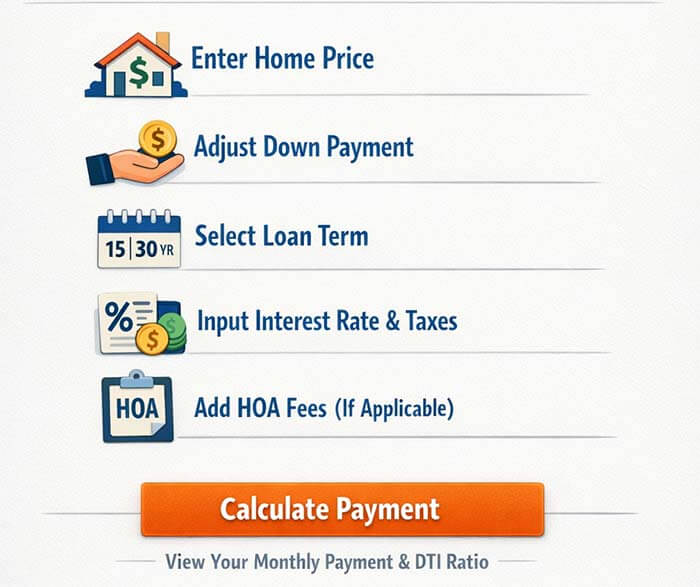
The Washington Mortgage Calculator takes a handful of inputs and spits out a monthly payment, but most people completely miss what's happening under the hood. You enter your home price, down payment, interest rate, loan term, and sometimes property tax and insurance figures. It computes the principal and interest portion using the standard amortization formula, then adds whatever line-item costs you provided. That's it. There's no magic involved. The formula behind the principal and interest calculation looks like this in plain terms: you divide the annual interest rate by 12 to get the monthly rate, multiply the number of years by 12 for total months, then apply the standard annuity formula. Most calculators do this silently. You just see the output. The real complexity isn't in the math, though. It's in getting the right inputs for Washington state specifically. I remember running into a situation last fall where a client was shocked that their calculated payment came in roughly $200 higher than what the lender actually quoted. We spent an hour tracking it down. The calculator had default county property tax rates from King County, but the property was in Pierce County, which has significantly lower mill levies. Once we swapped in the correct Pierce County estimate, the numbers aligned perfectly with the lender's Good Faith Estimate. Property tax variation within Washington is not something you want to ignore. The gap between King and Okanogan counties can exceed $1,500 annually on a comparable home, and that changes your monthly payment by around $125 to $130 with escrow included.
Washington Mortgage Calculator: What You Need to Know Before Using One
Washington doesn't have a state income tax, so some people assume their housing costs are straightforward. They're not. The state also does not have traditional mortgage recording taxes at the county level in the same way some states do, but there are still transfer taxes and documentation fees that affect your closing costs. A mortgage calculator won't capture all of that, and it shouldn't be expected to. These tools are designed for payment estimation, not full cost analysis. Here's something most online resources won't tell you: Washington is a recourse state for certain loan types. That doesn't change your monthly payment, but it fundamentally changes the risk profile if you ever walk away from the property. Non-recourse protection applies to purchase-money mortgages on owner-occupied residences, but refinance transactions and home equity lines of credit may expose you to deficiency judgments. A Washington Mortgage Calculator will never factor this in because it's outside the scope of payment computation. Still, understanding it matters enormously when you're making decisions about whether to refinance or pull equity out. Another counter-intuitive detail: Washington's document transfer tax is calculated at the county level and varies between $1.10 and $3.00 per $500 of the sale price depending on the county. Seattle has an additional municipal transfer tax on top of that. When you're using any mortgage calculator for a Seattle property, the difference between the city and a suburban county can add several thousand dollars to your closing costs, which then influences your required down payment and cash-to-close numbers. I had someone call me because their "monthly payment looked fine" but they showed up to closing with $8,000 less than they needed because the transfer tax estimate in their research was based on a county that charges half what King County charges.
The mortgage insurance question in Washington is also worth addressing directly. If you put down less than 20 percent, you'll likely encounter private mortgage insurance, which adds a meaningful line item to your payment. In Washington, PMI typically runs between 0.5 and 1.5 percent of the loan amount annually, depending on your credit score and loan-to-value ratio. A $350,000 loan with 5 percent down and PMI at 0.8 percent adds roughly $233 per month to your payment. Some calculators include this by default once you drop below 20 percent. Others don't, and they'll make your estimated payment look artificially low. HOA fees deserve the same blunt treatment. Seattle and Bellevue have a lot of condo and townhome inventory where HOA dues range from $300 to over $800 monthly. The Washington Mortgage Calculator won't know about these unless you input them. I've seen buyers approve an offer based on a calculator estimate that looked comfortable, then discover their HOA dues were $650 a month, pushing their debt-to-income ratio above what the lender would accept. Always verify HOA amounts before you rely on any payment estimate. One more practical point that trips people up: Washington's property tax year runs from July to June, and assessments are based on prior-year values. If you buy in March, you're typically paying taxes based on last year's assessed value, not the purchase price. This creates a discrepancy between what the calculator predicts and your first actual tax bill. The fix is to use the current assessed value of the property, which you can find through the county assessor's website, rather than relying on the purchase price as a proxy for taxable value. This is especially relevant in rapidly appreciating markets where assessed values lag significantly behind market prices.
Get the Full Details

When a Washington Mortgage Calculator Falls Short
No online calculator will accurately estimate your closing costs to within a reasonable margin of error. You need a loan estimate from a licensed lender for that. Calculators also cannot account for seller concessions, builder credits, or first-time homebuyer programs like Washington's Home Loan Programs that offer down payment assistance. These items materially change your effective costs and payment structure, but they don't exist in any generic tool. If you're working with jumbo loans, which are common in parts of Washington where prices exceed conforming limits, the interest rate environment is different and the underwriting requirements change. A standard mortgage calculator doesn't adjust for jumbo pricing. Your rate might be 0.125 to 0.375 percent higher than the conforming rate, which shifts your payment enough to matter. I've seen this catch people by surprise when they used a calculator showing conforming rates and then got a quote that was noticeably higher. The honest recommendation here is to use the Washington Mortgage Calculator as a starting point, not an ending point. Run a few scenarios with different down payments, interest rates, and tax estimates. Then take those numbers to an actual lender and request a loan estimate. The difference between a rough calculation and a binding loan estimate is the difference between guessing and knowing what your monthly payment actually is.