The Math Behind Splitting Your Auto Loan Into Smaller Chunks
Most people don't realize that changing how often you pay your car loan actually changes how much interest you pay over the life of the loan. It's not a loophole, but it is something lenders build into their amortization schedules, and understanding how it works matters more than most drivers think. Weekly car payments mean dividing your monthly payment amount roughly in half and paying it every week instead of once a month. A typical $400 monthly payment becomes two $200 payments each week, spread across the 52 weeks in a year. The result is 26 half-payments per year instead of 12 full payments, which works out to 13 months of payments compressed into a single calendar year. That extra monthly payment goes entirely toward principal after the first few months, and it shaves roughly one to two years off a standard 60-month auto loan while reducing total interest paid by anywhere from 8 to 15 percent depending on your rate and term length. I learned this the hard way when I refinanced my own truck loan from a biweekly setup back to a standard monthly schedule at 7.2 percent over six years. I had been making 26 half-payments a year without really tracking where the money was going, and when I switched gears I discovered I had already knocked nearly eight months off the original payoff date. The lender hadn't flagged it either. They just accepted the payments and let the extra principal eat into the balance silently.
The calculation itself is straightforward. Take your monthly payment, divide it by two, and pay that amount every seven days. Most modern lenders support this through automatic withdrawals from your checking account, so you set up a weekly recurring payment of the half-amount and walk away. Some older lender portals don't allow weekly scheduling and force you into biweekly instead, which is almost the same thing but slightly less aggressive because biweekly makes exactly 26 half-payments while weekly makes 52 full small payments. The difference is negligible for most borrowers, but if your lender only offers biweekly, confirm that it's being applied correctly and not sitting in a suspense account where it earns zero credit toward your balance.
How the Amortization Actually Shifts
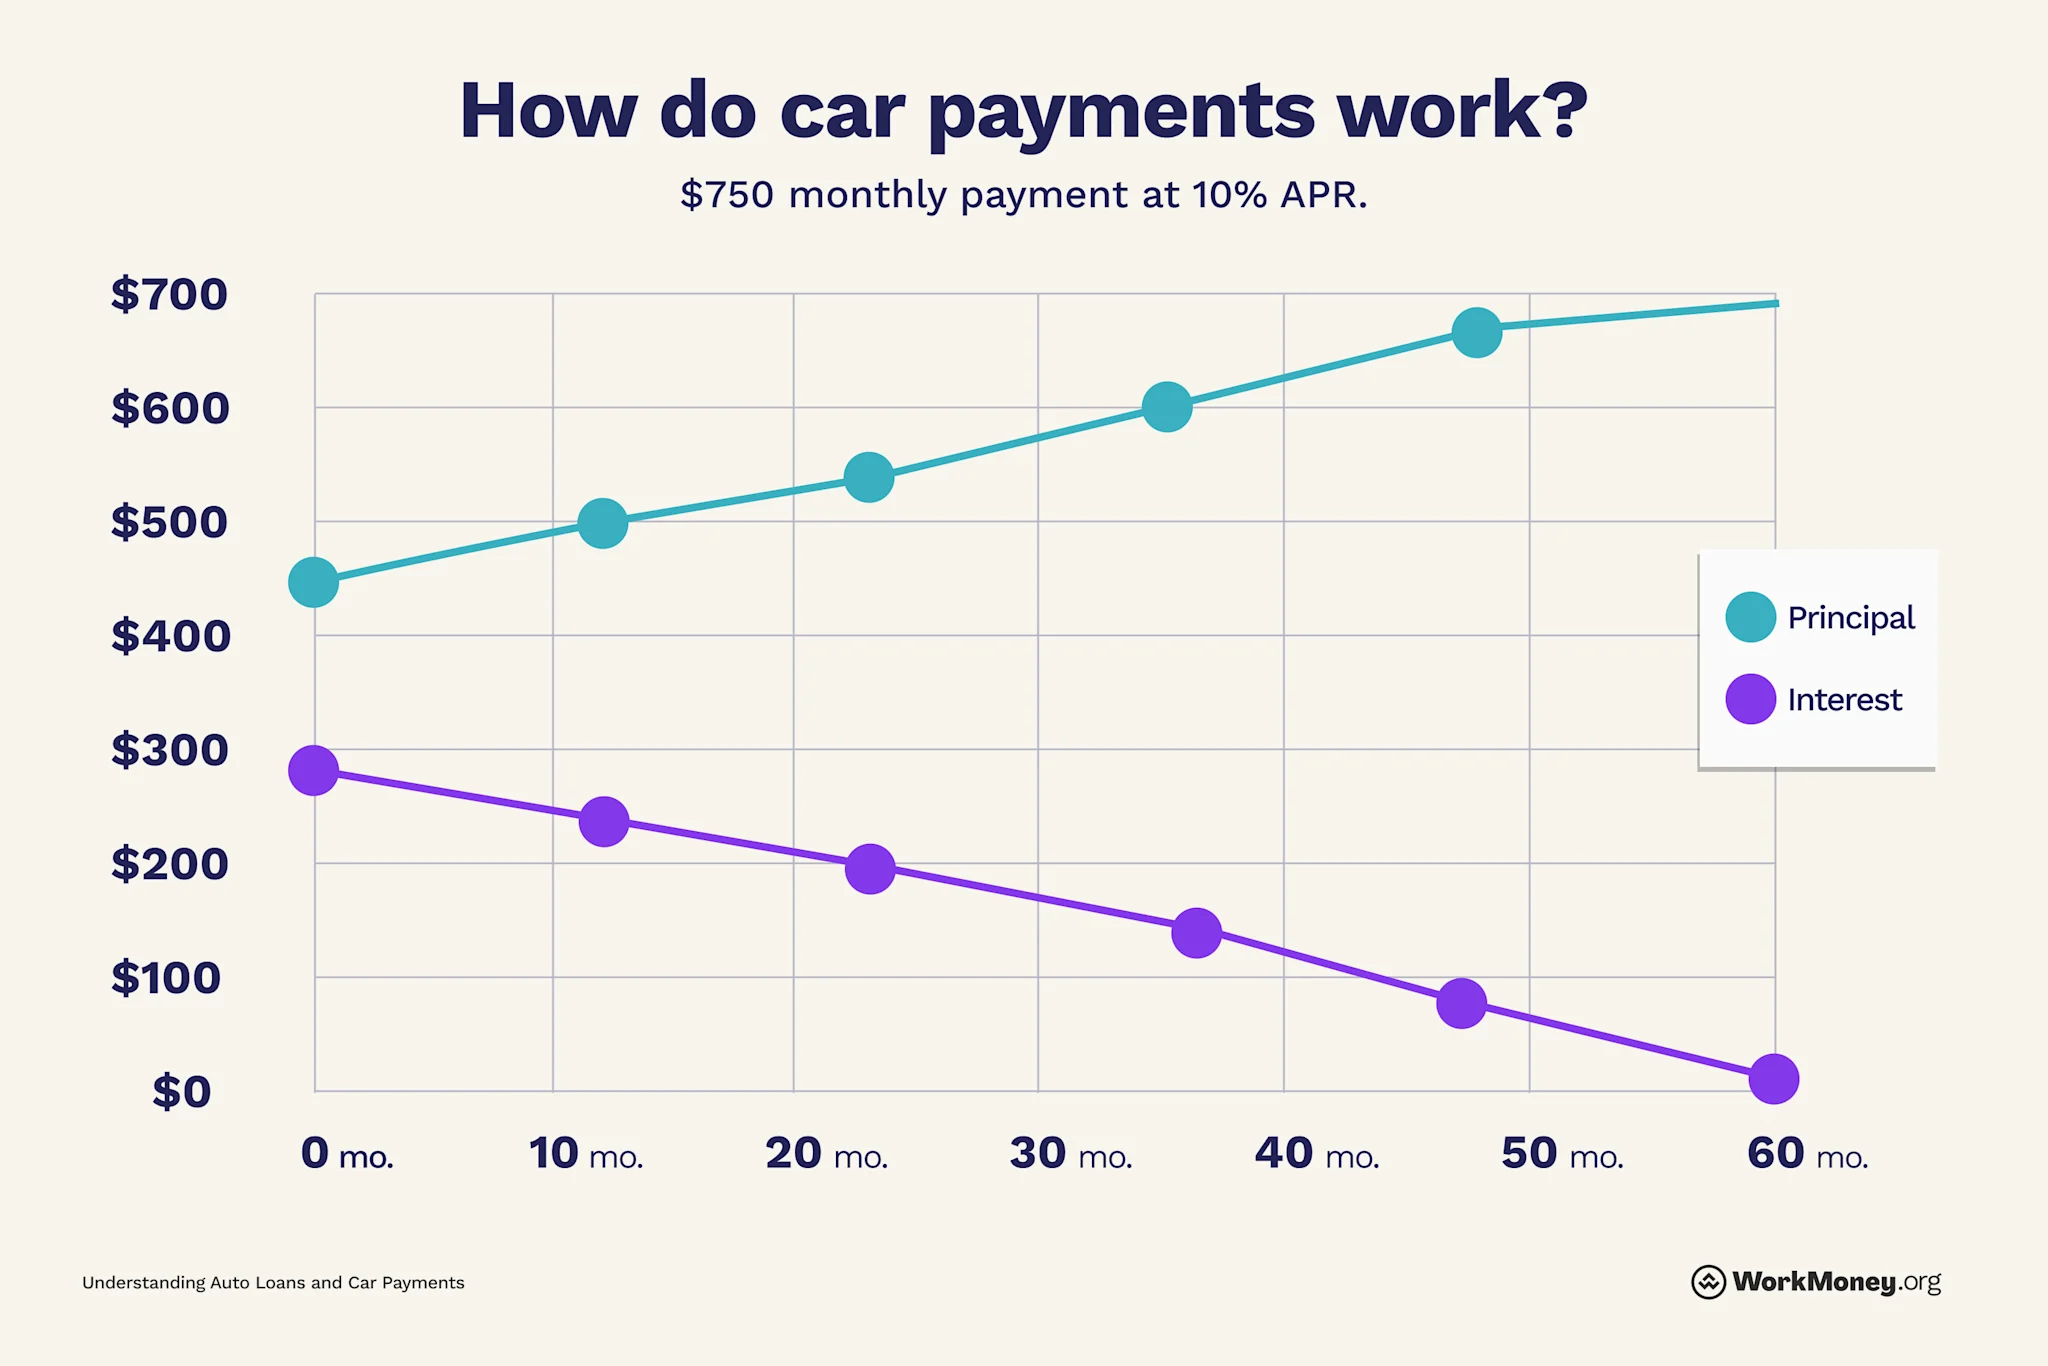
Here's the part most people skip. When you switch to weekly payments, the first payment you make doesn't just reduce your principal directly. It covers that week's accrued interest first, then whatever is left goes to principal. Because you're paying more frequently, the compounding window between payments shrinks. Instead of interest accruing for 30 days before your next payment, it's only accruing for seven. That's the mechanical reason why weekly payments cost less over time, even though the nominal interest rate never changes. Let me give you a real example. Say you owe $28,000 at 6.5 percent for 60 months. Your standard monthly payment comes to about $547. On a weekly schedule you'd pay roughly $273.50 every seven days. Over 60 months that adds up to 260 weekly payments instead of 720 monthly ones, but here's the thing. The lender counts weeks, not months, so you're actually making 60 payments per year if they structure it cleanly. The extra payment from the 52-week-to-13-month compression still happens, but the exact timing varies by lender because some use 52 divided by 12 and others use 26 half-payments per month. It sounds like nitpicking until you see a statement where one week's payment apparently didn't reduce principal at all because it fell on a day the system classified as a grace period overlap. I hit this exact problem once with a regional credit union. Their system would accept a weekly payment, but if the due date landed on a weekend or holiday, the payment would queue and the interest calculation would treat it as late. After three instances in a row I called them and asked them to lock in a fixed calendar day, like every Wednesday. That eliminated the floating due date issue entirely. The workaround was simple but took me four months and four phone calls to figure out on my own.
Get the Full Details

Practical Setup Steps
If you want to switch your current loan to weekly payments, start by logging into your lender's portal and looking for a payment frequency setting. It's usually somewhere under account settings, payment methods, or loan management. Not every lender exposes this option. Some hide it behind a phone call to customer service, and a few don't support weekly payments at all, only monthly or biweekly. When you find the option, select weekly and enter the amount. Use your monthly payment divided by two as the baseline. Some lenders will auto-calculate the correct split, others require you to type it in manually. Either way, double-check that the amount matches. I've seen borrowers accidentally enter their full monthly payment as the weekly amount, which doubles their payment and destroys their cash flow without meaning to. After you confirm the change, verify it on your next statement. Look for a line item that shows the payment was applied to principal and interest separately. If your statement only shows a flat payment amount with no breakdown, call the lender and ask for a detailed amortization schedule updated to reflect weekly payments. Without that schedule you're flying blind and you won't know whether the extra payment is actually happening.
Where This Breaks Down
Weekly payments don't work well for everyone. If your income comes on a monthly basis, like most salaried employees, splitting a payment across four weeks creates a mismatch. You might pay in week one, week two, week three, and then miss week four because your paycheck hasn't arrived yet. That misses payment lands on your credit report just like any other late payment, and one missed weekly payment is easier to overlook than one missed monthly payment because the dollar amount feels smaller. Another scenario where this fails is loans with prepayment penalties. Some subprime lenders charge a fee if you pay down principal faster than the schedule allows, regardless of whether that acceleration comes from weekly payments or a lump sum. Check your original loan agreement for a clause about prepayment penalties or yield maintenance fees. If it exists, the weekly payment savings could be eaten entirely by the penalty on the extra principal you're pushing forward. I ran into this with a previous vehicle I bought from a buy-here-pay-here lot. Their contract had a prepayment penalty that triggered after the first 24 months. I switched to weekly payments after month ten thinking I was saving money, and within three months I'd paid about $400 in penalty fees that wiped out most of the interest savings. The lender didn't warn me about it either. It was buried in section 14, subsection C of a 38-page contract.
Alternatives That Might Fit Better
If weekly payments aren't viable for your situation, there are other ways to get the same result. You can make one extra full payment per year on your existing monthly schedule. The math is nearly identical to weekly payments, except you lose the benefit of more frequent compounding reduction. You'll save a bit less interest, maybe 2 to 4 percent over the life of the loan compared to weekly, but the administrative hassle is zero. Another option is rounding up. Set your monthly payment to the nearest hundred and direct the excess toward principal. If your payment is $547, pay $600 and designate the $53 as principal-only. Most lenders will apply it correctly as long as you specify it in writing or through their portal. This avoids the weekly complexity entirely while still compressing your payoff timeline. The clearest alternative is refinancing into a shorter term. Switching from 60 months to 48 months at the same rate means higher monthly payments but significantly less total interest. Whether this beats weekly payments depends on your rate environment. If rates have dropped since you originated your loan, refinancing could lower your rate AND shorten your term, which usually outperforms weekly payments on a purely mathematical basis. But if your credit has slipped or rates are higher now, the refinance option vanishes and weekly payments remain the cheapest path forward without a lump sum available.

The Numbers in Practice
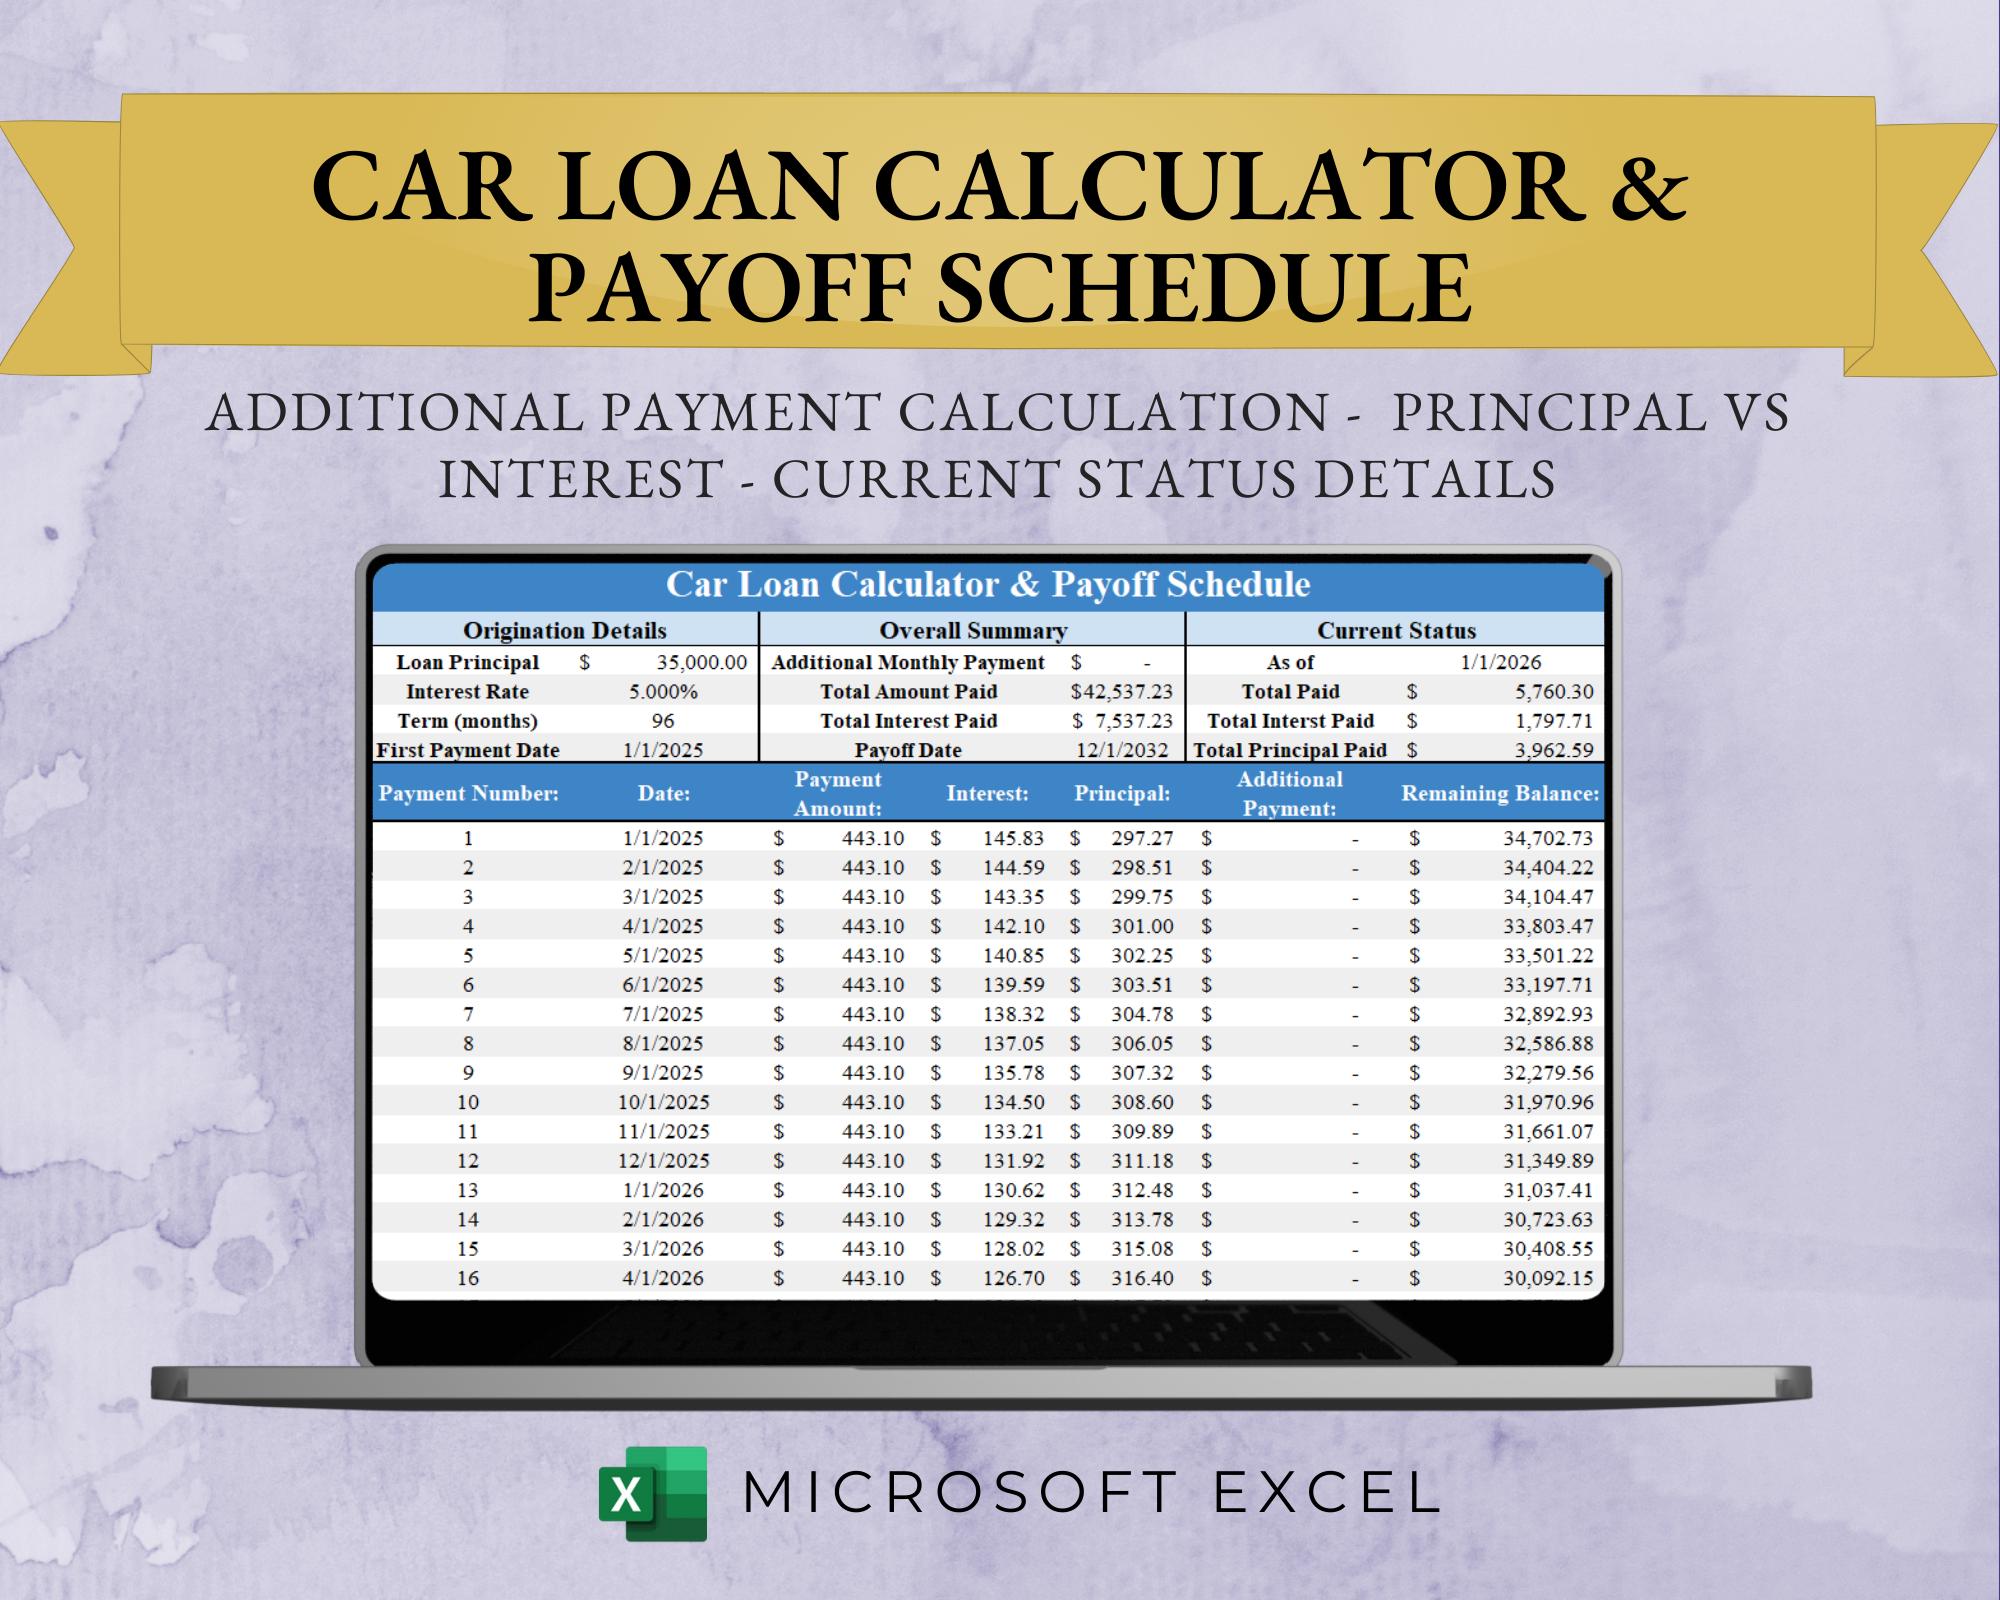
For a $32,000 loan at 7 percent over 60 months, the standard monthly payment is about $634. Weekly payments of roughly $317 cut total interest from about $6,040 down to roughly $4,820. That's a savings of $1,220 and a payoff that lands around month 54 instead of month 60. For a $18,000 loan at 5.5 percent over 72 months, weekly payments save about $980 in interest and shorten the term by roughly 11 months. The larger the balance and the longer the term, the more weekly payments matter financially. On a very short loan, like a 36-month term at a low rate, the savings shrink to maybe $200 or $300 total. At that point the administrative overhead of managing weekly payments isn't worth the marginal gain. Weekly payments pay for themselves on medium to long-term loans with rates above 5 percent. Below that threshold, the math gets thin enough that either approach works fine.
Setting It Up Without Getting Dropped
The biggest risk isn't the payment amount. It's the funding side. Automatic weekly withdrawals from a checking account mean your balance gets hit four times a month instead of once. If you miscalculate your budget and the account runs dry mid-cycle, you get NSF fees on top of a potentially reported late payment. I once overdrafted my account on a Thursday because I forgot two of the weekly payments had already cleared that week. The bank charged $35, and the lender charged a $25 late fee because the payment hadn't fully settled before the grace period expired. That $60 in fees wasn't covered by the interest savings for about two months. To avoid this, set up a separate savings buffer of one full monthly payment amount before switching to weekly. Deposit it once and treat it as a permanent cushion. The weekly payments draw from your operating account, the buffer covers any gap. It's an extra step but it eliminates the random fee cascade that comes with more frequent automated withdrawals. Also confirm with your lender that they're using the standard daily simple interest method and not some compound-interest scheme disguised as weekly payments. Most legitimate lenders use daily simple interest for auto loans, which means each payment reduces the principal balance and the next day's interest calculation uses the new lower balance. A few smaller lenders or subprime originators use different methods that can work against you if you're not reading the fine print. Ask specifically about their interest calculation method and get it in writing if you can.
The bottom line is that weekly car payments are a legitimate, proven way to reduce interest cost and shorten your loan term, but they only work when your cash flow supports the frequency and your loan terms allow it. Check for prepayment penalties, confirm the interest method, set up a buffer, and verify on your next statement that the payments are being applied correctly. Skip any of those steps and you're more likely to lose money than save it.