Financial Intermediaries and What They Actually Give You
Most people think of brokers, mutual funds, and banks as gatekeepers. They're more like filters. You bring raw capital and vague goals to them, and they return something closer to a portfolio. Whether that return is worth the fees is the actual question. I spent years watching retail investors bypass intermediaries to save on commissions, then lose more in execution errors, tax missteps, and emotional decisions. The math rarely works out in their favor. Let me break down what these middlemen actually provide, what they don't, and where they fall apart.
What Advantages Do Financial Intermediaries Offer An Investor
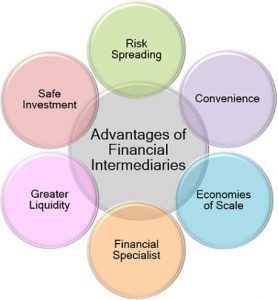
Liquidity access is the first real advantage. If you own shares of a small-cap stock directly, selling it can take days. Through a brokerage intermediary, you have instantaneous access to an order book. That speed comes at the cost of fees and sometimes wider spreads on illiquid names, but for most investors, the ability to exit a position within seconds matters more than the two-basis-point spread. Risk pooling is the second structural advantage. A mutual fund or ETF bundles hundreds of investors' money to achieve diversification you couldn't replicate on your own without enormous capital. Holding twenty-five stocks across different sectors costs you in both transaction fees and management time. A single mutual fund share gives you that exposure instantly. The tradeoff is the expense ratio, which typically runs between 0.03 percent for index funds and over 1 percent for actively managed ones. I've seen investors who couldn't justify the difference, and I've seen the opposite. Context matters. Information processing is where intermediaries earn their keep most directly. A financial advisor isn't just picking stocks. They're monitoring your tax situation, rebalancing your allocation, suggesting changes when life events occur, and filtering market noise. The best ones do this quietly without selling you something new every quarter. The worst ones treat your account like a revenue center. Distinguishing between them takes effort on your part.
Custody and settlement are the boring advantages that matter most during a crisis. When a broker-dealer fails, SIPC insurance covers up to $500,000 per account, including a $250,000 limit for cash. It's not perfect coverage, but it's the alternative to losing everything to a counterparty failure. I watched a firm in 2022 that failed to properly segregate client assets, and several customers lost access to their holdings for three weeks while regulators sorted it out. That's not hypothetical anymore.
Get the Full Details

The Mechanics of How This Actually Works
When you deposit money into a brokerage account, the intermediary becomes the legal owner of the securities on record. You are the beneficial owner. This separation exists for operational reasons, not deception. Clearing houses need a single point of accountability. The downside is that you never directly hold the certificates. You hold a claim against the intermediary, which is why custody arrangements and asset segregation matter more than most investors realize. Order routing is another mechanism that deserves scrutiny. Many retail brokers route orders to market makers like Citadel Securities or Virtu Financial rather than sending them directly to exchanges. This practice, called payment for order flow, generates revenue for the broker and typically results in slightly worse execution prices for the investor. The difference is often two to five cents per share on equity trades. On a large order, that adds up. On a small one, it's negligible. The real question is whether your broker discloses this arrangement and whether the price improvement they occasionally receives through internalization exceeds what direct exchange routing would produce. I once had a client who was switching brokerages and asked me to pull her execution quality reports. Her previous broker was routing eighty percent of orders to a single market maker. The fill prices were consistently one tick worse than the national best bid and offer. Switching to a broker that used direct exchange routing improved her average execution by roughly twelve basis points annually. She didn't notice it in her statement, but over three years on a four-hundred-thousand-dollar portfolio, it translated to roughly two thousand dollars in drag. Small, but compounding.
Where Intermediaries Underperform
The fee structure of intermediary services is where the model breaks for a significant number of investors. A typical financial advisor charges between zero point five and one percent of assets under management annually. On a hundred thousand dollars, that's five hundred to one thousand dollars per year regardless of whether the portfolio goes up or down. A brokerage commission structure based on per-trade fees favors infrequent traders. Active traders pay more. Both models reward the intermediary more than they reward the investor in flat or declining markets. Diversification through intermediaries creates a false sense of security. Index funds give you market exposure, which is diversified in theory but concentrated in practice because the largest cap stocks dominate the benchmarks. The S&P 500's top ten holdings represent roughly thirty-five percent of the index. If those ten companies stumble simultaneously, your supposedly diversified fund takes a direct hit. The intermediary hasn't protected you from concentration risk. They've just disguised it. I encountered a specific edge case recently involving a client who held a large position in employer stock through a 401(k) plan administered by a major intermediary. The plan offered daily pricing at net asset value, which seemed straightforward. However, the intermediary's valuation methodology for certain illiquid alternative investments within the same plan used stale pricing from the previous quarter. When the market dropped sharply, the fund's reported NAV lagged reality by approximately eight percent. The client would have sold at an artificially high price if they hadn't checked the underlying holdings independently. The workaround was simple: request the fund's current holdings list directly from the provider rather than relying on the intermediary's summary statements. Most intermediaries won't volunteer this, but they're required to provide it on request.
Common Pitfalls Beginners Miss
The biggest mistake investors make with intermediaries is confusing access with advice. Just because a platform lets you buy any security doesn't mean you're making informed decisions. Robo-advisors are excellent for basic asset allocation and tax-loss harvesting, but they cannot meaningfully address concentrated positions, estate planning complexities, or tax bracket management. If your financial situation involves more than three asset categories, a robo-advisor becomes a constraint rather than a solution. Another pitfall is not understanding who the intermediary's fiduciary duty actually belongs to. Registered investment advisors have a fiduciary obligation to act in your best interest. Broker-dealers operate under a suitability standard, which means they only need to recommend products that are suitable for you, not necessarily the best option available. The distinction matters most when products with higher commissions overlap with products that have lower fees but similar characteristics. I've seen this play out repeatedly. The suitablity standard allows the intermediary to steer you toward the higher-fee product without technically breaking any rules. The third common error is underestimating the operational risk of using multiple intermediaries. An investor might hold stocks with one broker, bonds with another, and a retirement account with a third. Each platform has different reporting formats, different login systems, different tax documentation timelines. At tax time, this fragmentation becomes a real problem. Consolidating accounts with a single intermediary typically reduces annual administrative time by several hours and eliminates the chance of missed tax forms. The convenience gain is often undervalued.
Alternatives Worth Considering
Direct indexing has emerged as a viable alternative for investors with portfolios above one hundred thousand dollars. Instead of buying an S&P 500 ETF, you purchase the individual underlying stocks yourself through a brokerage that supports this feature. The result is the same market exposure plus the ability to customize tax lot harvesting and exclude specific companies for ESG reasons. Some brokerages now offer this without additional fees. Others charge a small percentage on top of standard trading commissions. The math works in your favor once the customization benefit exceeds the incremental cost. For investors who primarily want diversification without active management, low-cost index funds through a discount broker remain the most efficient path. Vanguard, Fidelity, and Schwab all offer expense ratios below point zero five percent on their core index funds. The intermediary's role here is purely transactional. You select the fund, buy the shares, and hold them. Any advisory layer on top of this is optional and usually unnecessary unless you need tax optimization or retirement planning guidance. The reality is that financial intermediaries exist because markets are complex and most investors don't have the time or expertise to navigate them alone. The advantages are real but unevenly distributed. Liquidity, risk pooling, and custodial services benefit nearly everyone. Information processing and personalized advice benefit only those who can identify competent intermediaries and avoid those who prioritize their own revenue over your outcomes. Fees erode returns predictably. Operational risk is unpredictable. Understanding which category your situation falls into determines whether an intermediary adds value or simply adds cost.