How Automatic Stabilizers Actually Work in Practice
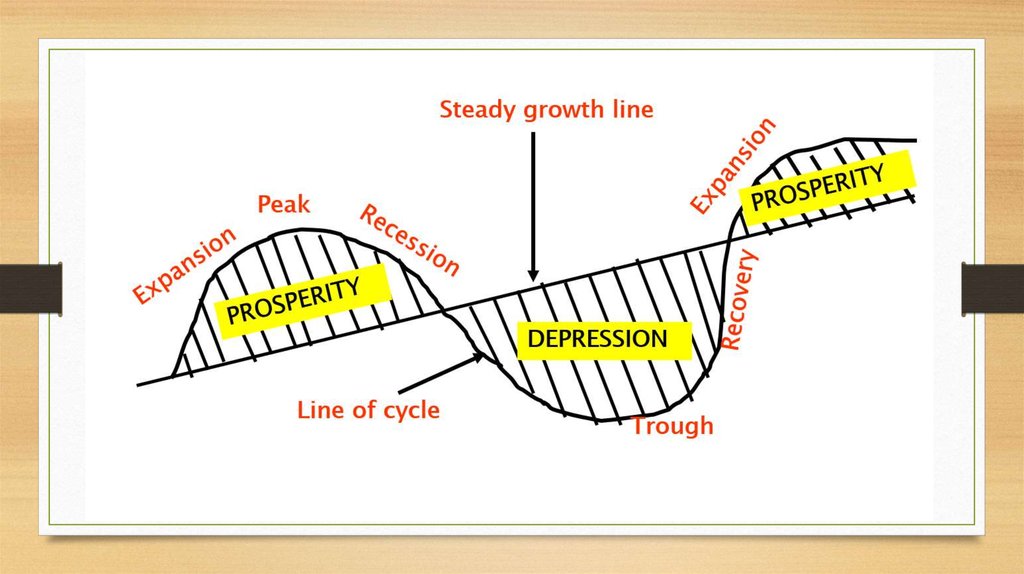
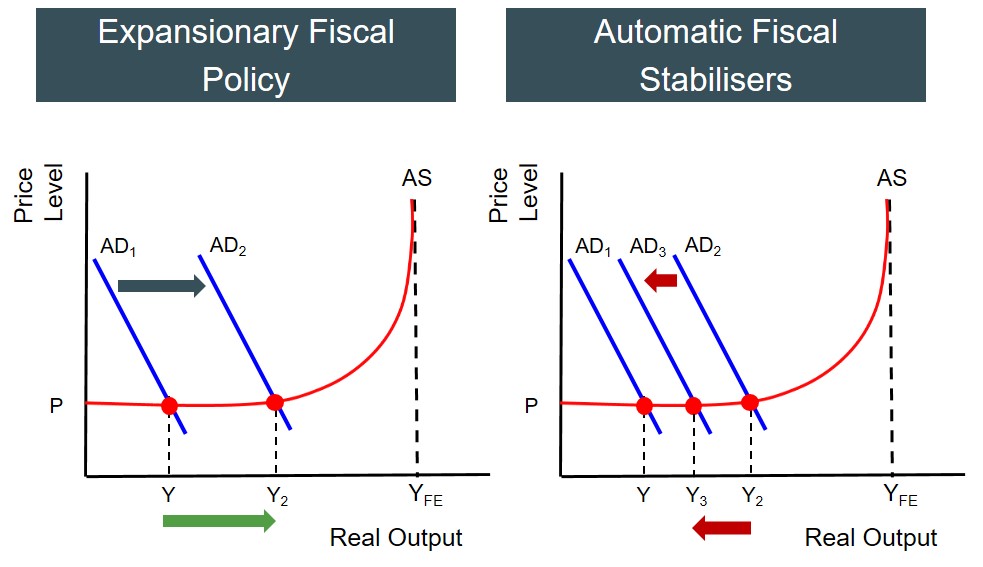
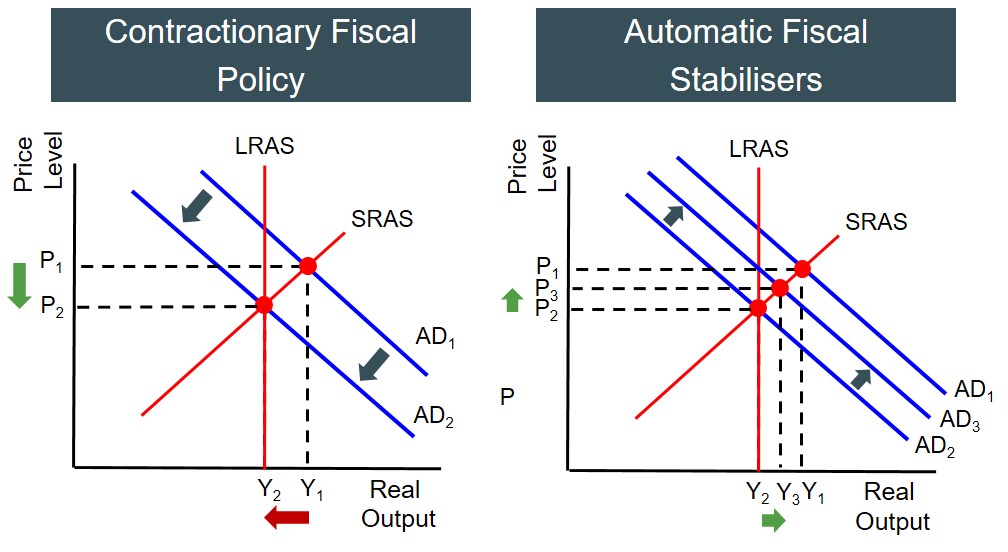
Most people understand the basic idea—government spending goes up and taxes go down during recessions without any new legislation—but the mechanics are where things get interesting and, frankly, frustrating if you're trying to model them. Automatic stabilizers are built-in features of the fiscal system that respond to economic conditions without requiring new legislative action. Progressive income tax brackets, unemployment insurance, food stamps, welfare payments. When GDP contracts, fewer people pay the same amount of tax and more people qualify for transfers. The reverse happens during expansions. It's counter-cyclical by design, not by accident.The key thing beginners miss is that these stabilizers don't work evenly across all downturns. They depend heavily on the structure of your economy. A country with a large informal sector gets almost zero stabilization from its automatic mechanisms because those workers aren't paying income tax and aren't covered by unemployment insurance. I spent weeks trying to reconcile fiscal impulse data for a Southeast Asian economy last year and kept getting contradictory results. The OECD multiplier estimates just didn't fit. Turned out roughly 40 percent of their labor force was informal, so the tax-and-transfer channel was dramatically weaker than textbook models assumed. My workaround was to adjust the effective tax base downward using household survey data rather than relying on official revenue statistics. Took me three weeks of data cleaning but the results finally made sense. There are a few nuances that trip people up. First, the size of automatic stabilizers depends on the elasticity of tax revenues and transfer programs to output. If your corporate tax base is narrow and flat, revenue doesn't fall much when GDP drops, so the stabilizer effect is weak. Second, there's a lag problem. Unemployment benefits might take six to eight weeks to flow through to households after a job loss. By the time the fiscal boost hits aggregate demand, the worst of the downturn may already be over. Third, during shallow recessions the stabilizers barely register. They're designed for meaningful contractions, not mild slowdowns where GDP dips a fraction of a percent. Another issue that doesn't get enough attention is the asymmetric nature of some stabilizers. Unemployment benefits ramp up quickly when jobs are lost, but they don't ramp down symmetrically when jobs return. There's hysteresis in the system. People who lose long-term employment don't immediately re-enter the tax-paying workforce, so transfer payments stay elevated well past the official end of a recession. This creates a persistent structural deficit that's often misattributed to discretionary spending choices rather than the delayed decay of automatic mechanisms. I've seen this confuse budget analysis several times—people blaming new programs for what was actually the tail end of old automatic stabilizer effects.
You also need to understand what's driving the numbers. Discretionary stimulus and automatic stabilizers both improve the budget balance during a contraction, but they send very different signals about future policy. Automatic stabilizers will reverse on their own as the economy recovers. Discretionary measures stick around. This matters for debt sustainability analysis and for forward-looking fiscal surveillance. The European Semester framework tries to separate these components explicitly because blending them together produces misleading assessments of fiscal stance. The bottom line is that automatic stabilizers are the fiscal system's shock absorbers. They're not a suspension setup. They prevent the worst impacts but they don't eliminate the bumps, and they stop working effectively if the road ahead is fundamentally broken. Strong institutions, broad tax bases, and adequate social safety nets are what make them functional in the first place. Without those, you're just running the same old machinery with nothing underneath it to catch the fall.