Most people walk into retirement planning with a vague sense of dread and a spreadsheet full of gaps. They ask about 401(k) match percentages and Roth conversions but skip the parts that actually determine whether they sleep at night at 72 instead of gasping for money at 58. I spent roughly eight years doing this for clients before I stopped needing a CFP label to know what was missing from the conversation.
The hardest part isn't the math. It's figuring out what you actually need to know before you hand your life over to a financial planner or, worse, your own optimism.
What Are Good Questions To Ask About Retirement
Let's start with something most people don't consider until it's too late: sequence of returns risk and your actual withdrawal floor. You know the 4% rule. What you don't know is that in a bad market right before or during the early years of retirement, that 4% becomes 2.8% before you even realize your portfolio is underwater. I had a client in 2021 who was set up perfectly on paper—60/40 split, clean withdrawal plan, everything looked textbook. Then the market corrected hard the next year. His numbers held on average, but his psychological number cracked. He pulled out early and locked in losses because no one had asked him what happens when the market drops 30% before he retires, not after.
The workaround wasn't fancy. We shifted about 18 months of expenses into cash equivalents and shortened his equity glide path by five years. It cost him roughly 0.4% annually in expected returns but kept him from liquidating shares during a drawdown. The question to ask isn't what rate of return you need. It's what happens to your plan if returns are below inflation for three straight years and you're still 12 years from Social Security.
Then there's the healthcare gap question. Medicare doesn't start until 65. If you retire at 58 and your spouseretires at 62, you're looking at anywhere from three to seven years of expensive private insurance depending on where you live. I once worked with a couple who budgeted for Medicare premiums and forgot the ACA marketplace entirely. Their actual annual healthcare cost in those bridge years was about $28,000 combined. Not catastrophic, but enough to shift their withdrawal strategy significantly if it wasn't planned for.
Ask about Medigap vs. Medicare Advantage tradeoffs too. The standard answer from planners is sometimes oversimplified. In practice, Medigap Plan G gives you far more flexibility if you travel or have specialists across state lines, but the premiums are higher and the underwriting can reject you if you have pre-existing conditions when you first become eligible. Medicare Advantage sounds cheaper until you need specialty care and your plan denies it or sends you out of network. This isn't theoretical. I've seen retirees spend weeks navigating denials because they chose the cheaper option without reading the restrictions.
Your tax bracket question is another area where people get it wrong. Everyone asks what tax bracket they'll be in retirement. Nobody asks which brackets they'll accidentally trigger by pulling too much from traditional accounts in a single year. RMDs kick in at 73 now. Combined with required Social Security claims and any lump-sum distributions, you can find yourself pushed into the 22% or 24% bracket without meaning to. The fix is often strategic Roth conversions in low-income years between retirement and RMD age, but that requires knowing exactly how much space you have under the 22% threshold each year.
Here's a question that catches people off guard: what happens to your estate if something goes wrong mid-retirement? Not death. Divorce, incapacitation, or a lawsuit. I had a guy in his late 50s who was divorced twice and had kids from each marriage. He had no updated beneficiary designations because his first wife's IRA went to her name back in 1998. The account sat there growing tax-deferred with an outdated designation. When he remarried, the old beneficiary was still on file. He needed an affidavit of dependency and a court process to fix it, which tied up the assets for nearly a year and cost about $4,000 in legal fees. The question he should have asked wasn't about tax planning. It was about what happens if your personal situation changes after you set your accounts up.
Capital gains harvesting is something I see planners skip or bury in appendices. If you're in a lower tax bracket during early retirement years, you can realize long-term capital gains at 0% up to a certain income threshold. For a single filer in 2024, that's about $47,000 of taxable gains. For married couples filing jointly, it's roughly $94,000. This is free money if you have appreciated assets sitting in a taxable account. The catch is you need to know your exact income situation each year, which means tracking every dollar of withdrawals, Social Security taxation, and any other income streams precisely. I use a simple spreadsheet that projects this annually and flags the window each year. It saves maybe 30 minutes a year but can shave thousands off lifetime tax liability.
Another practical question nobody asks: what is your actual monthly burn rate, not your annual number? Most people calculate retirement using annual expenses and assume they'll spend evenly throughout the year. They don't. There are big lump-sum costs—property taxes, insurance premiums, car replacements, medical deductibles—that come at specific times. I track my clients' annual expenses by quarter and month. This reveals patterns. One client had $14,000 in annual property taxes that hit in March and September. Another had $3,200 in car insurance every six months. These aren't emergencies. They're predictable. But when you model retirement with just an annual number, you miss the cash flow timing issues that cause real problems.
The inflation assumption is another place where standard advice fails. Planners often use 2.5% to 3% for inflation. That works fine for consumer goods but not for healthcare, which historically runs 4-5% annually over long periods. If your healthcare costs make up more than 15% of your retirement budget, using 3% inflation underestimates your future needs significantly. I adjust healthcare costs to 4.5% and education costs for grandchildren to 3.5%. The difference sounds small but compounds dramatically over a 30-year retirement.
There's also the spousal coordination problem. If you and your spouse have different retirement ages, different Social Security claiming strategies, and different health expectations, your combined plan needs to account for all of it. The survivor benefit question matters here. If one spouse dies first, the surviving spouse often loses a significant portion of income unless proper planning was done. Maximized survivor benefits through delayed claiming can add tens of thousands in lifetime value, but only if you understand how the calculation works before you claim.
Here's an edge case I encountered that probably won't make it into any planning software: what happens if you need to reverse a withdrawal due to a temporary market downturn? Say you pull $50,000 from your portfolio in year two and the market drops 20% that year. You could technically recharacterize that contribution to a Roth IRA within one year, but the recharacterization rules have changed and they're confusing. What actually works better is having a bucket of cash set aside specifically for this scenario. Instead of selling down equity in a downturn, you use cash. This is called cash flow management and it's one of the most under-discussed aspects of retirement planning. It's also something I've seen save clients from irrecoverable losses multiple times.
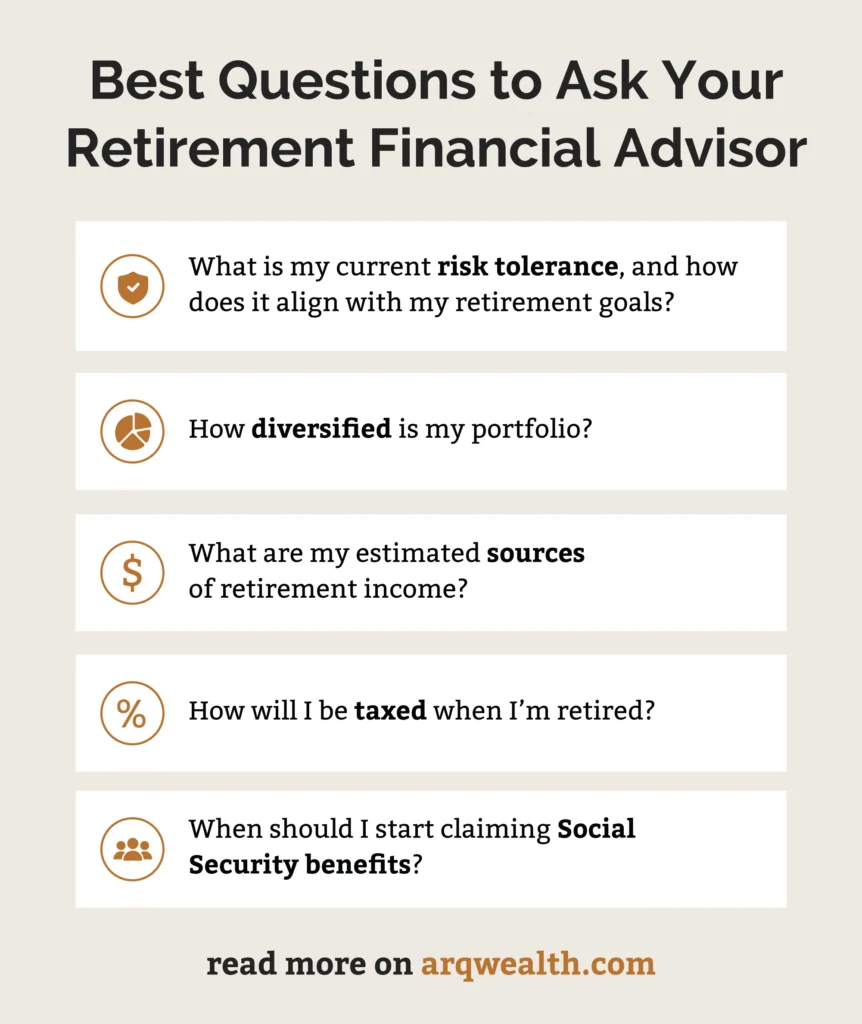
If you want a practical list of questions to bring to your first planning session, here's what I'd prioritize:
- What is my monthly income floor and how does it change if my market returns are below expectations?
- How will healthcare costs change from now to Medicare eligibility, and what's the actual premium I should budget?
- What tax brackets am I likely to fall into between retirement age and RMD age, and how much Roth conversion space do I have each year?
- What happens to my accounts if my beneficiary designations are outdated or my situation changes?
- Can I harvest capital gains at 0% during low-income years, and how do I track that window?
- What are my largest quarterly or annual expenses and when do they hit?
- How does my spouse's Social Security strategy affect our combined income in later years?
- Do I have enough liquidity to avoid selling equity during a market downturn without derailing the plan?
These questions don't come from a template. They come from watching people who followed the standard advice and then hit edges that no spreadsheet caught.
Gallery What Are Good Questions To Ask About Retirement
14 Questions About Retirement You Need To Answer - Finance Over Fifty
Top Questions for 'Who Knows the Retiree Best' Game at Your Retirement Party! | How to memorize ...
The 250 Retirement Questions Everyone Should Ask eBook by David Rye - EPUB | Rakuten Kobo United ...
Are you ready to retire? If you are struggling to determine if you are ready for retirement ...
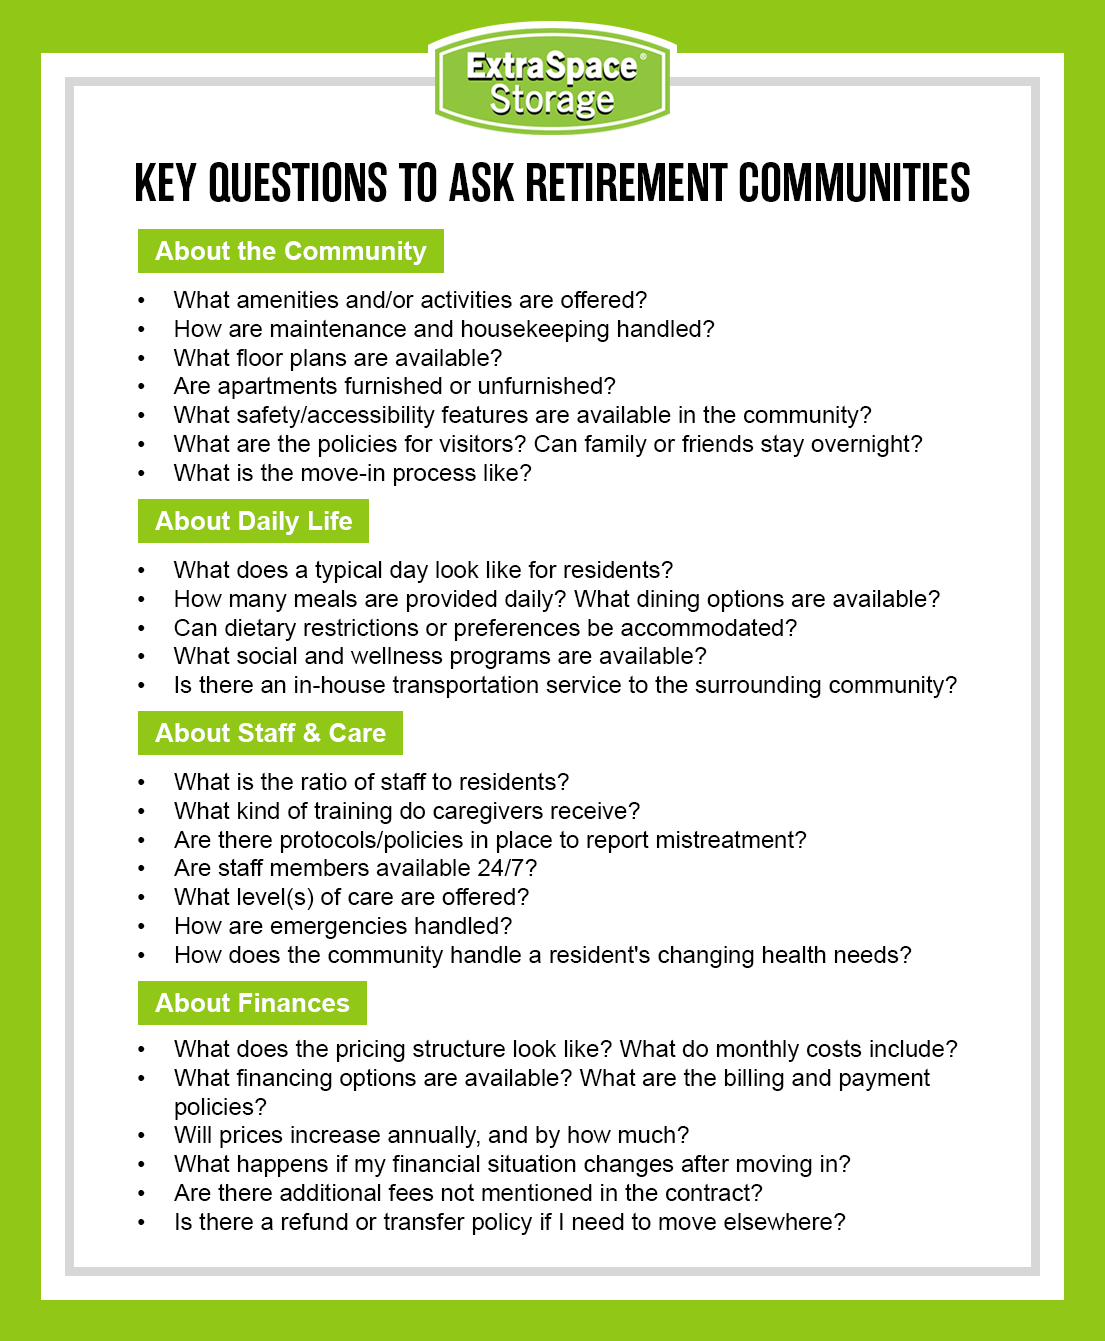
How to Choose a Retirement Community